Showing posts with label Mudajaya. Show all posts

Friday, December 31, 2010

Belated Comments Received Regarding Mudajaya

Ah.. here's a reply to a OLD post, SC Article On Mudajaya Reveals Serious Allegations Made Against Mudajaya

Best I highlight it.

  • Eric said...

    The cost of IPP depends on the specifications and quality so as motocar. All cars with same cc will cost differently. Just compare proton 1.8 litre with continental car with 1.8 litre. The price difference is huge. Using cost per/MW as argument is just lame justification.

    By the way, has anyone considered the possibility of Indian Partner reducing their investment price in order for Mudajaya to increase theirs. Then there will be no inflation of cost for the plant. CIMB, pls do your homework!

    Companies recover their investment thru profit from contract awarded back is to a certain extend normal but must be arms length and it must be done without round tripping. I mean investment must be paid up first then only recover your investment over time. In Mudajaya's case it is earn a bit from procurement contract and then pay for the capital in IPP also by a bit. The process is repeated over and over. Any donkeys also can raise capital in that manner.

    How much Mudajaya was given profits to recover their basic/original investment cost is unknown. However, it is certain that they are given the profits to pay for portion of investment that has been inflated, the same portion of investment value that the Indian partner has deflated, I guess.

Do see also last month's posting Quick Look At Mudajaya's Earnings

Wednesday, November 24, 2010

Quick Look At Mudajaya's Earnings

Here's the updated numbers.


The receivables again increased. (See posting: SC Article On Mudajaya Reveals Serious Allegations Made Against Mudajaya )

The cash is depleting and the main reason is the 'investment in associates'.


Friday, October 08, 2010

SC Article On Mudajaya Reveals Serious Allegations Made Against Mudajaya

Blogged on August 2010: Regarding MudaJaya

It was a long posting and I made the following remarks.


  • The allegations made in the so-called poison letter is rather interesting but as it is, I believe that there's no much to be said.

    The only concern is perhaps the receivables which had increased significantly since its fy 2007 and needless to say, if the allegations were indeed true!

As back then, there was nothing much to be said because there was not much that could be seen from its earnings notes. Yes, perhaps it's a concern that the receivables had increased significantly since fy 2007.

On today's papers, on Business Times:

  • SC raps Mudajaya for inadequate disclosures

    By Adeline Paul Raj Published: 2010/10/08

    The Securities Commission yesterday took Mudajaya Group Bhd to task for having failed to make adequate disclosures on its independent power plant project in India.

    The SC, in a press release, said it viewed “seriously” the builder’s failure to provide adequate information on the IPP prior to August 30 this year and cautioned that it must ensure compliance in future.

    The regulator had looked into Mudajaya’s (5085) affairs some months ago after receiving an anonymous complaint about the builder’s investment in the Indian project.

    It had required Mudajaya’s auditor, Ernst & Young, to come up with a report on the project, which the latter did. The report was dated September 9 this year.

    The SC said it had reviewed the transactions relating to Mudajaya’s investment in the IPP, in particular the transfer of funds between related entities.

    “Ernst & Young’s S320 report had also revealed movement of funds between Mudajaya and related entities ... that is characteristic of the practice known as “round-tripping”.

    “The practice of round tripping has been raised as a concern in several jurisdictions. In this regard, the SC will conduct a separate exercise to review the use and disclosures associated with the “round-tripping” practice,” it said.

    An SC spokesperson clarified that it is studying the practice of round-tripping in general, not specifically Mudajaya.

    A quick Internet search on the term “round-tripping” revealed that it is a creative practice that is intended to wrongly inflate revenues.

    Mudajaya’s involvement in the Indian power project started in April 2006 when it agreed to build and operate a 1,2000-megawatt coal-fired plant in Chhattisgarh together with its Indian partner RKM Powergen Pvt Ltd.

    Among the issues brought up in the anonymous complaint letter was the high price Mudajaya paid for its 26 per cent stake. Mudajaya paid RM871 million for it compared with the RM273 million that RK Powergen paid for its 74 per cent stake.

    Mudajaya has since clarified that the premium it paid was justified as it included approvals, the IPP's contracts, coal cost-savings and a chance to enter India's power industry.

    But there was also criticism that its 80 per cent-owned company, MIPP International Ltd, which had been awarded a RM3.4 billion equipment and procurement contract for the plant, had unusually high profit margins.

    The SC, from its review, concluded that Mudajaya had failed to make adequate disclosures on pertinent matters relating to the IPP project.

    It then asked Bursa Malaysia Bhd to issue a directive to Mudajaya for additional information. This was then provided by the builder on August 30.

    Source: here

Now this sounds rather serious. Inflating revenue is DEAD WRONG!

It is cheating!

Let's refer to the posting Regarding MudaJaya again (Yes, I am aware that Mudajaya had since reported a 'newer' set of quarterly earnings but I will ignore that because it's rather irrelevant to this issue ) and look at this two tables again.


In fy 2007, Mudajaya's sales revenue was 273.981 million.
In fy 2008, Mudajaya's sales revenue surged to 422.382 million.
In fy 2009, Mudajaya's sales revenue surged again to 719.971 million.
TTM earnings as at Aug 2010, showed Mudajaya's sales revenue at 833.950 million.

Leaving out the TTM numbers, since fy 2007, Mudajaya's sales revenue surged some 445.990 million. In the space of just 2 years, Mudajaya's sales revenue increased by 261%.

In fy 2007, Mudajaya's net earnings was 30.140 million.
In fy 2008, Mudajaya's net earnings was 45.117 million.
In fy 2009, Mudajaya's net earnings was 116.897 million.
TTM earnings as at Aug 2010, Mudajaya's net earnings was 172.928 million.

Net earnings REALLY exploded in proportion to its sales revenue growth. Which would be logical.

However, since now allegations is saying that Mudajaya could be 'round-tripping'.

Now this would require a more stringent look at the cash. Does the cash balances shows the wealth creation?

In fy 2007, Mudajaya's had 84.767 million cash.
In fy 2008, Mudajaya's had 69.776 million cash.
In fy 2009, Mudajaya's had 116.074 million cash.
TTM earnings as at Aug 2010, Mudajaya's had 295.086 million cash.

Now that would appear fair but since Mudajaya had a placement exercise which generated some 176.902 million, I would DISCOUNT this 176.902 million from the latest cash balance of 295.086 million. Which means Mudajaya's cash balances for reference should be around 118 million. (Not forgetting Mudajaya fy 2007 cash was boosted by another share placement that generated some 56 million)

Now remember fy 2007, Mudajaya had 84.767 million. And after all this sales revenue growth and profit growth, Mudajaya's cash only increased to 118 million.

Hmmm..... how?

Could Ernst & Young’s S320 report that suggest 'round-tripping' between Mudajaya and related entities be true?

How?

On Star Business: What is ‘round tripping’ and why is the SC reviewing its use and disclosure?

  • According to Investopedia, round tripping artificially inflates volume and revenues, but in reality adds no profit. Enron was said to be a company that engaged in round-trip trading, and, by doing so, was able to increase revenues (and expenses) without changing its net income

Here's Mudajaya's latest earnings update:


By itself, TTM sales revenue is extremely impressive at an incredible 859.852 million. Earnings is also very impressive at 200.541 million. The sales revenue and net earnings growth since fy 2007 is truly incredible, yes?

But if look at the cash, cash balances as at fy 10 Q2, is now only 243.990 million. And if you discount the share placement exercise which generated some 176 million, Mudajaya's cash balances actually weakened!

Yes, that's rather peculiar, yes?

Record sales revenue growth and record profit growth but yet, cash balances actually decreased!

My makcik would ask 'Macam mana ni?'

And needless to say... look at the trade receivables!!!!!!

Receivables is now at an incredible 359.422 million!!!

Why the sudden drastic increase?

Hey.. if one wants to be an investor, a long term investor, one better find out yes?

However.... now we are reading about the allegations about 'round tripping'!!

How?

Here's Mudajaya's latest cash flow:


Some 148 million in cash was generated from its profits.

The 'cash generated from operations' is interesting....

The trade receivables increased by 124 million! And the trade payables decreased by some 46 million. ( Ah.. if I am not wrong, it appears to me that the bulk decrease in cash went to pay off Mudajaya's creditors!)


How?

But some would be quick to point that for its fy 2009 earnings the less cash is easily explainable...

Quarterly rpt on consolidated results for the financial period ended 31/12/2009


Yes, for fy 2009, a huge chunk of Mudajaya's cash went into the entry 'investment in associates'. Amount shown in its Q4 cash flow statement is 149 million!

Which probably explains why the 'investor' does not see the 'creation of wealth' in Mudajaya's cash flows.

Case closed?

But.... but............. if one open Mudajaya's fy 2009 Q3 notes, MUDAJYA2009Q3.xls, one would see the entry of 'investment in associates' totals 86.600 million.

And if one opens Mudajaya's previous quarter cash flow notes, MUDAJYA2009Q2.xls. one would see the entry of 'investment in associates' totals 25.553 million.

Hmm... every quarter... a huge chunk goes into this 'investment in associates' and so far, this fiscal year to date, Mudajaya has dumped another 15.881 million!

Yeah.. so the data from Midajaya is saying that sales revenue growth is incredible and the earnings growth is explosive. But with it.. trade receivables growth was just as incredible. So was the trade payables. And of course, the bulk of the cash went into this 'investment of associates'.

How?

Now given the allegations of 'round tripping', the chunk of money that went into 'investment of associates' becomes rather significant, yes?

Who are these associates?

What are these investments?

How much more 'investments of associates' are we going to see in the immediate future?

-----------------------------------------------

Reply from David Koay

  • Investment of associates should be the IPP project in India :) The money earned from the construction of the project is plowed back into the IPP project as part of its 26% equity stake commitment. So, can't really say there's no wealth creation as Mudajaya is bound to reap its harvest from India once the IPP starts operation. The question is whether the earnings from IPP could justify the RM871 million being plowed into the IPP project. Mudajaya will be putting another RM671 million over the next two years into investment of associates. That will equal about RM80 mil per quarter.

    As for valuation of Mudajaya, I will not put its construction earnings from IPP together with its 26% stake in IPP like what is done by CIMB. Instead, valuation should only include its 26% stake in IPP and exclude its earnings from IPP construction as construction profits are channeled back to the IPP anyway. By excluding IPP construction earnings, its earnings should be halved, probably about RM140-160m.

    Simple valuation: RM1800m (Construction earnings PER 12x) + RM800m 26% stake in IPP + RM30m properties. Work out to be RM6.40 per share. Hope this helps :)

Thursday, August 05, 2010

Mudajaya Shares Plunges!

On today's Edge Financial Daily: RM1b worth of new jobs in FY10 for Mudajaya (Apparently OSK released that report yesterday)


  • RM1b worth of new jobs in FY10 for Mudajaya
    Written by Financial Daily
    Thursday, 05 August 2010 11:23

    Mudajaya Group Bhd
    (Aug 4, RM4.93)
    Maintain buy at RM5.08 with a target price of RM7.33: Based on our estimates, Phase 1 (RM762 million) hit 41.9% completion as of June versus 23.2% in January. We understand that deliveries for the key plant components are slightly delayed to August from June as scheduled earlier due to minor specification changes. Nonetheless, management reaffirms that the entire project is on track for completion by end-2012.

    We expect the bulk of the revenue recognition for Phase 1 to take effect this year. There are also plans to expand capacity by another 2x360MW when the existing four plants near completion.

    This means Mudajaya could land another EP contract estimated to be worth RM1.7 billion.

    The Indian government intends to set up nine Ultra Mega Power Plants (UMPPs), three of which have been awarded. The next two up for grabs are located in Chhattisgarh and Orissa, for which the prequalification of tenders will be conducted by end-August.
    Evaluation is expected to take two to three months before the final tenders are called, which could then take another six to seven months before the results are known. Each UMPP will have a capacity of 4,000MW and cost about US$5 billion. Mudajaya intends to bid for both UMPPs via a consortium.

    During its AGM, Tanjong said it intends to bid for the UMPPs together with Mudajaya. We gather that an Indian-listed contractor, IRB Infrastructure, could potentially be the consortium’s local partner.

    Management did not provide details on the shareholding structure, but we think Mudajaya may take up a 20% to 25% stake. We believe that if successful at the bid, Mudajaya could grab a slice of the EPCC contract, expected to be worth US$3.75 billion.

    Locally, Mudajaya will be submitting its tender for the civil works portion of the LRT extension, which will close by month-end. Recall that Mudajaya constructed some stations for the existing line.

    The company is also looking at the seven highway projects planned under the Public Private Partnership (PPP).

    However, it intends to participate in those jobs as a pure contractor instead of a concessionaire.

    It is also eyeing some PFI projects comprising education facilities and power plants. Overall, management is guiding for RM1 billion worth of new jobs for FY10. —
    OSK Investment Research , Aug 4


    This article appeared in The Edge Financial Daily, August 5, 2010.

As you know, Mudajaya shares plunged!


And OSK had a report with a recommendation of "Maintain buy at RM5.08 with a target price of RM7.33".

The next day stock plunges 20%!!

Ouch!!!

Saturday, May 22, 2010

Errata Made On The Posting "What Do I Think Of Mudajaya's Earnings Performance..."

Just for the record...

I made the following statement in the posting
What Do I Think Of Mudajaya's Earnings Performance...

  • Do you see the wealth created?

That question was asked in light of Mudajaya's balance sheet, which showed its cash balance increased to 295 million ( refer snap shot here ) and Mudajaya carried no debts.

Well... it's a crooked way to present the company to say the least because I failed to show why and how the cash increased substantially. By not pointing how these money came about, I was painting the wrong picture and insinuated that there was massive wealth created within the company.

The following comments from that posting corrected me. :)

  • Choong Wai said...

    Hi Moola,

    the cash increase could it be possible of the share placement?below is the extract from their annoucement."

    The Company has on 6 January 2010 proposed for the placement of up to 10% of its issued and paid-up share capital (net of treasury shares) to investors to be identified ("Proposed Placement"). The Proposed Placement was approved by BMSB on 12 January 2010. On 28 January 2010, 37,238,500 ordinary shares of RM0.20 each was allotted to identified investors at RM4.80 per share and these shares were subsequently listed at BMSB on 29 January 2010.

    The net cash proceeds of RM176.90 million arising from the Company's share placement of 37,238,500 ordinary shares of RM0.20 each will be utilized as follows: -"

That was absolutely spot on!

I failed to show the following announcement. Sorry. :/

MUDAJAYA GROUP BERHAD (“MUDAJAYA”) PRIVATE PLACEMENT OF 37,238,500 NEW ORDINARY SHARES OF RM0.20 EACH IN MUDAJAYA ("PLACEMENT SHARES") AT AN ISSUE PRICE OF RM4.80 PER PLACEMENT SHARE (“PRIVATE PLACEMENT”)

That money was accounted and credited in the quarterly announcement made this month.

Many sorry for the misinterpretation.

Thursday, May 13, 2010

What Do I Think Of Mudajaya's Earnings Performance...

On the Edge Financial Daily: OSK Research raises target price for Mudajaya to RM7.33


  • KUALA LUMPUR: OSK Investment Research has maintain call on MUDAJAYA GROUP BHD at RM5.09 and raised its target price for the stock to RM7.33 (from RM6.48) after the company posted 1QFY10 earnings of RM51 million (+260% y-o-y, +23% q-o-q), which the research house said was above its own and consensus expectations.

    It said Mudajaya remains its top pick in the sector and that it sees stronger showing in the subsequent quarters once Phase 2 gains further momentum.

    "Forward prospects include India's UMPPs, LRT extension, domestic power plants, Saudi jobs and PFI projects. We raise our FY10-11 earnings by 13%-14%," it said.

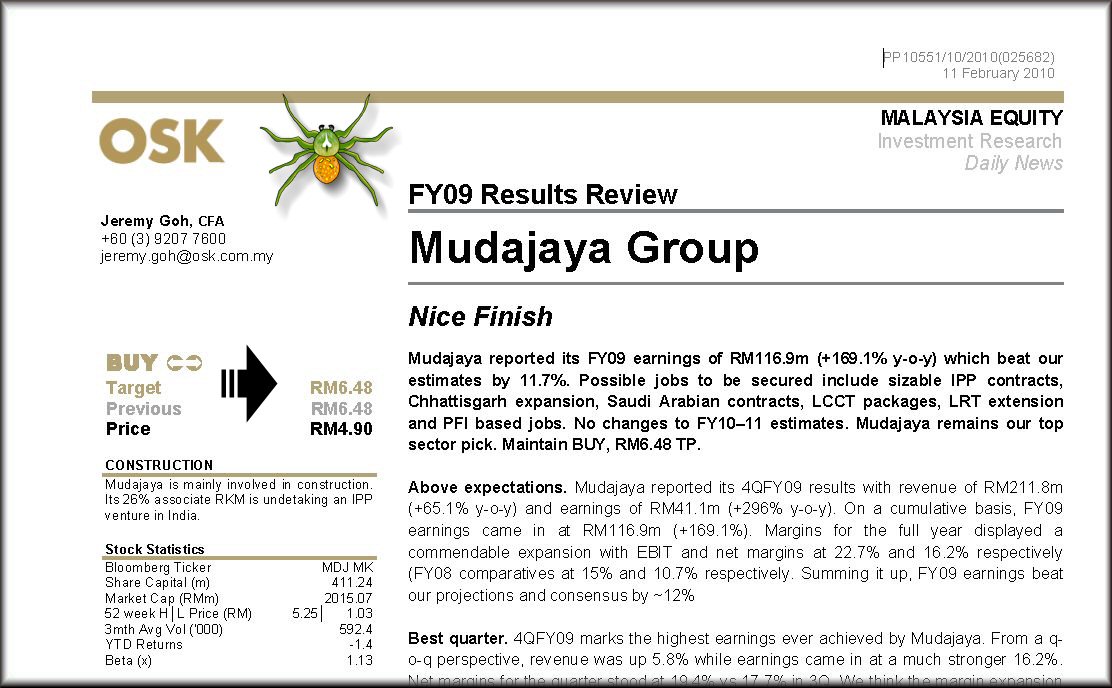
On 11th Feb 2010, OSK wrote the following...

So today, what OSK did was increased Mudaya's target price to 7.33 (LOL! So precise eh?) from rm 6.48.

But if I compare with say CIMB, OSK valuation was rather low. :P


CIMB was already giving Mudajaya a TP of 7.52 back in Feb 2010.

Here's Mudajaya earnngs in Feb 2010. Quarterly rpt on consolidated results for the financial period ended 31/12/2009

It made a very impressive 41 million.

  • Mudajaya 4Q net profit surges two-fold to RM41m
    Written by The Edge Financial Daily
    Wednesday, 10 February 2010 17:51

    KUALA LUMPUR: MUDAJAYA GROUP BHD []'s fourth quarter net profit surged two-fold to RM41.05 million from RM10.36 million a year ago increased level of activities.

    It said on Wednesday, Feb 10 that revenue rose 65% to RM211.76 million from RM128.22 million while earnings per share were 11.02 sen versus 1.50 sen. It declared 10% dividend per share or two sen per share.

    For FY09, net profit surged to RM116.9 million from RM45.12 million while revenue rose to RM719.98 million from RM422.38 million. Of the RM719.98 million, CONSTRUCTION [] accounted for RM604 million.

    "Barring any unforeseen circumstances, the financial performance of the group for 2010 is expected to improve further," it said

( ps: here is its Nov 2009 earnings: Quarterly rpt on consolidated results for the financial period ended 30/9/2009 - It made 'only' 35 million. And if you do a q-q-q quick comparison, this is not too shabby yes?)

Anyway, here is Mudajaya balance sheet taken from its previous quarter (ie from the earnings announced in Feb 2010. Link: here )


Mudajaya has no borrowings.

Here's Mudajaya balance sheet taken from its earnings reported last night.


How?

Do you see the wealth created? ( ERROR! Please see this: Errata Made On The Posting "What Do I Think Of Mudajaya's Earnings Performance..." )

Yes? No?

And the company's segmental explains where and why the company is doing well.


Again I asked how?

This company is not doing too shabby, yes? Compare to those other construction stocks, how?


Oh yeah.. this is a randomly dedicated posting, which means I cannot guarantee that you will lose money if you blindly follow and assume that this is a stock tipsy.

And just for the record, the stock is now trading at 5.11.

*********************

IMPORTANT

Please read this: Errata Made On The Posting "What Do I Think Of Mudajaya's Earnings Performance..."