Showing posts with label Transmile. Show all posts

Saturday, January 10, 2009

Detecting Companies' Malpractices

Excellent article posted on Star Business: How to detect companies' malpractices

  • Saturday January 10, 2009

    How to detect companies' malpractices

    Investors have lost thousands and millions due to companies’ malpractices but there are ways to detect the warning signals

    Following the revelation of the shocking Bernard L. Madoff’s US$50bil Ponzi scheme, there has been much uproar over the US regulator’s incompetence in failing to uncover a swindle of such mammoth proportions.

    Madoff’s Ponzi scheme is possibly the largest financial fraud in US history. Questions have been raised as to how this could escape the eye of the Securities and Exchange Commission.

    Thousands of enraged investors have accused Maddoff of stealing their life savings.

    Here in Malaysia, while not of that magnitude or of the same nature, investors have found their investments dwindle due to significant accounting-related mishaps.

    Transmile Group Bhd, a once-upon-a-time darling, rattled investors by its accounting fraud. Then, there was optical disc producer Megan Media Holdings Bhd which incurred huge debts and losses over “massive collusive fraud”. When discovered in August 2007, Megan Media was grappling with losses and debts to the tune of over RM1bil.

    The dramatic exposure of Transmile came to light in mid-2007, when auditors discovered fake receivables sitting on Transmile’s books.
    From a market cap of RM3.89bil at its high of RM14.40 on Jan 3, 2007, the company has now been reduced to a dismal market cap of RM155.32mil.

    Since then, Transmile shareholders have collectively lost billions. Not surprisingly too, Transmile has been announcing losses in its quarterly earnings since.

    There were, however, some shrewd fund managers who managed to escape unscathed from the Transmile episode. Trusting his gut, a fund manager from a local firm sold his Transmile shares at the peak, just before the issue erupted. He tells how he was already feeling uneasy with management’s consistent evasiveness during analyst briefings.

    “Management was avoiding some of the questions we asked. They could not give me a straight answers,” says the fund manager.

    What are the signs?

    Investors who have been victims of fraud are probably angry and want retribution. Before that happens, maybe watching out for red flags would be more helpful.

    When choosing to invest in a stock, MIDF Amanah Asset Management Bhd chief executive officer Scott Lim says a key criteria is honesty in management.

    He is wary of companies, which during company visits, tell fund managers one thing but announce a different thing altogether. He believes the company should be totally transparent and try their best to explain their actions to all shareholders.

    “Whether the fund manager is a majority or small shareholder, they should have total access to information. If the company is beating around the bush, and not being direct in their answers, I think it is time to sell their shares,” he says.

    A fund manager who had the bad experience of being deceived by a second board Malaysian-listed company,
    says investors should be careful when management promises unrealistic returns.

    Looking at the character of captain of the company is also important.
    “If they are the sort who veils everything, very tight lipped, won’t give much information to analysts or shareholders, and are combative in nature, it’s time to be careful,” he says.

    He says another red flag is when companies are unable to articulate a clear strategy or are vague on how it gets its returns.

    Kumpulan Sentiasa Cemerlang head of stock research and partner, Choong Khuat Hock, admits that it is not easy to spot a fraudulent company, but there are a few signs one can watch out for. “I would still look at the balance sheet. If the company has a very high debt level, or has a business model that relies on a lot of capital expenditure to grow, then I would be wary,” he says.

    He adds that companies that are trying to boost their earnings to maintain their past track record, could also fall prey to fraud as there could be attempts to manipulate their books. “This was probably what happened to India’s Satyam group. They needed to increase earnings to meet analyst expectations,” he says.

    Recently, Satyam Computer Services Ltd chairman Ramalinga Raju resigned after saying he falsified accounts and assets. Raju unsuccessfully tried to sell two companies to Satyam last month in a final attempt to plug 50.4 billion rupees of “fictitious assets” on the company’s balance sheet.

    Choong also advises investors to
    invest in companies which possess a consistently good corporate governance track record.

    “Avoid companies that have dabbled with related party transactions or have been involved in buying over family-related companies. The company may do it again. Sometimes a leopard doesn’t change its spots,” he says.

    The local fund manager tells shareholders not to be complacent even when the captain behind the company appears to have a lot of integrity. “You have faith in the person. You see good profits and hence, may abandon common sense. But when the company guarantees a certain level of performance, be suspicious. Be very doubtful if his track record looks too good to be true, because it probably is,” he says.

    He adds that if the investment manager’s record seems remarkably steady over a long period of time, it ought to provoke scepticism. After all, markets fluctuate between good and bad times. If returns continue to be good despite market fluctuations, it doesn’t make sense.

    Like a Ponzi scheme, a pyramid scheme depends on keeping its volatility low, so that victims don’t start thinking of cashing in en masse. The moment that happens, the game is over, and shareholders get burnt.

    Nonetheless, there are many times too that shareholders fall for financial scams simply because of their own gullibility.

    This can be explained by the “irrational exuberance factor”. This is the tendency of humans to model their actions, especially when faced with affairs they don’t entirely comprehend, on the behavior of other humans.

    So, if a stock is deemed solid and full of potential by most fund managers, then the investment must be good and most people flock to buy the stock. Still, and as many bitter episodes have shown, it is no guarantee of capital preservation.

Wednesday, November 26, 2008

Transmile Again

It's been a while since I wrote on this stock. Transmile reported its earnings last night and it was not pretty. This morning, Business Times carried the following article on it.


  • Transmile reports lower Q3 net loss

    Published: 2008/11/26

    LOCAL air cargo carrier Transmile Group Bhd (7000) reported a narrower third-quarter net loss, helped by cost reduction and higher charter revenue and general freight sales.

    Net loss for the quarter ended September 30 2008 narrowed to RM26.3 million, compared with a net loss of RM84.8 million during the same period a year ago.

    In a statement issued yesterday, Transmile, controlled by Hong Kong-based billionaire Tan Sri Robert Kuok,
    said the net loss included an unrealised foreign exchange loss of RM24.6 million on US dollar loans taken by a subsidiary company.

    If the unrealised foreign exchange loss were excluded, the group's net loss for the quarter would have been RM1.7 million.

    However, revenue slid 35 per cent to RM68.1 million from RM104.8 million, due to the lower flight hours as a result of the cessation of unprofitable routes flown by its four MD-11 planes since end-March 2008.

    Transmile managing director Liu Tai Shin said the group will continue to look for new business opportunities, including having discussions with prospective strategic partners on the possibility of flying new regional routes.

    He added that discussions were ongoing with the lenders on the proposed restructuring of its outstanding debts totalling RM554.1 million.

    "We are optimistic that a mutually agreed settlement will be reached and the restructuring of the outstanding debt will allow Transmile to pay all the debts that are due and payable in the next 12 months," he said.

    It is also pursuing the disposal of its MD-11 aircraft to raise cash for the repayment of its outstanding borrowings, which were raised to purchase the said aircraft.

    The net loss for the nine months through September 30 2008 also narrowed to RM94.9 million from RM149.3 million.

    Revenue was RM237.2 million, down 42 per cent from RM408.7 million.

So I decided to have a look at its Balance Sheet.

Ok, the receivables has corrected significantly ( but it's still a bit high in my opinion.) and the cash balances has diminished quite a bit (if one compares it to the same period, previous fiscal year)

And the borrowings remains high.


Here are past postings on the Transmile saga:

  1. Transmile Receivables,
  2. How about TransMile?,
  3. TransMile,
  4. More on TransMile,
  5. 50 Million Adjustment for TransMile?
  6. The Full audit Statement on Transmile!
  7. Reviewing the events at TransMile
  8. Cooking And More Cooking!!

Tuesday, May 13, 2008

Hefty Fines Imposed on Transmile Directors?

Published on the Edge: Transmile case jolts auditors on governance issues

  • KUALA LUMPUR: Actions such as hefy fines on Transmile Group Bhd directors have jolted many audit committee members and auditors into paying greater attention to corporate governance issues, said consulting firm Columbus Circle Governanance chairman Navin Pasricha.

    “There is a big breakthrough in the actions of regulators when policing corporate governance. In the past, limited policing and action were barriers to getting real corporate governance improvement,” he said in a statement released here yesterday in conjunction with the forthcoming 4th Asia Pacific Audit & Governance Summit (APAGS).

I am so puzzled!

Are the fines imposed on the Transmile Group Bhd directors really hefty?

Have a look at this Bernama news clip on May 5th: SC Drops Charge On Ex-Chief Financial Officer Of Transmile

  • KUALA LUMPUR, May 5 (Bernama) -- The Securities Commission (SC) Monday withdrew the charge against former chief financial officer of Transmile Group Bhd after he paid a compound of RM700,000.

    Sessions Court Judge S. M. Komathy Suppiah allowed the charge against Lo Chok Ping, 39, to be withdrawn after SC's Deputy Public Prosecutor Foo Lee Mei told the court that the Attorney-General's Chambers had allowed a representation by Lo's counsel N. Sivananthan.

    Lo was charged with the company's former chief executive officer Gan Boon Aun and executive director Khiudin Mohamed on July 12 last year with abetting the company in making a misleading statement in its quarterly report.

    Lo, Gan, 47, and Khiudin, 51, had claimed trial to committing the offence at Bursa Malaysia Securities Bhd here between Feb 28, 2006 and Feb 15, 2007.

    According to the charge, the alleged statement was made in the unaudited consolidated results for the fourth quarter of the financial year ending Dec 31, 2006, and it was likely to induce purchase of securities of Transmile Group by other people.

    SC had issued a statement that the misleading statement was related to Transmile's revenue of RM338.473 million.

    Komathy fixed May 26 for mention of the case against Gan and Khiudin.

A compound fine of rm700,000 was paid and SC withdrew the charges.

Is a fine of rm700,000 enough?

Transmile was trading as high as rm14.00. It now trades at around rm1.50.

Do you think this fine is just for investors who had purchased the stock based on the misguided figures at around rm14.00?

Yeah, some would simply argue that the stock market is simply a cruel, cruel world but this simply isn't correct!

The so-called misleading statement had caused the market to rate the stock at a much, much higher valuation. There was growth, the stock was going places.

It made the justifications required for the stock to trade above RM14.00.

The market was valuing the stock with a market capitalisation of as much as rm3.7 billion!

As it is, without these so-called misleading statements, Transmile is making losses. Now there is no growth and the company has heaps of massive problems.

And the stock is sinking into the abyss.

And currently the market capitalisation of the stock is only around 400 million!

What a difference the so-called misguided statement had on the stock market capital.

So tell me, is rm700,000 hefty?

We shall see what happens next.

Poor Martha!

Tuesday, June 26, 2007

Cooking And More Cooking!!

Two articles posted on The Edge Weekly on TransMile and Megan.

Quote: In a nutshell, it was a well-designed scheme running for years involving some customers and suppliers and the company's top management.
Quotes:
  1. "If everyone writes off their loans completely, the banks will still stand but there will be a substantial impact on earnings. It's a problem," says a bank executive last week
  2. "It's like a house of cards. All you need is for one bank to pull the credit line and the whole company will collapse," he says.
  3. Megan Media seems to worry the lenders more. As at January, its borrowings total RM888 million, of which RM320 million is in the form of Islamic bonds that have defaulted. Megan's principal bankers are Citibank, CIMB, DBS, HSBC, Malayan Banking and RHB. "
  4. Each bank's exposure to Megan ranges from as low as RM10 million to RM250 million. So the size of the hit will vary," says the bank executive.
  5. "For now, it's generally agreed among the creditors that there's no point pulling back credit lines or calling for the company to be liquidated. But some are wary of Citibank because its head office may decide to pull the plug," notes the bank executive.

Monday, June 04, 2007

The Danger of These Accounting Woes

Posted on Reuters, Malaysian accounting woes could hurt market surge - Reuters

KUALA LUMPUR, June 4 (Reuters) - Malaysia leads the pack in a rally of Southeast Asian stock markets, but concern over a rash of accounting irregularities at some listed firms could hurt sentiment and thwart further gains, investors say.

  • "Transmile was a highly credible company with a credible board and credible shareholders that was doing very well and all of a sudden, this happens," said Abdul Wahab Jaafar Sidek, chief of Malaysia's Minority Shareholder Watchdog Group (MSWG)

    "This affects not just the credibility of the company and its directors but also Malaysia's capital markets."
  • State-controlled Bumiputra-Commerce Holdings Bhd (BUCM.KL: Quote, Profile , Research), Malaysia's second-largest lender, was in the spotlight after it commissioned a review of the 2005 financial statements of its newly-bought Southern Bank Bhd unit.

    The review showed up inappropriate accounting treatment that resulted in an overstatement of Southern's net assets by some 160 million ringgit.

    Last week, Bumi said the offending statements had been corrected by June 30, 2006, and no more amendments were needed.
  • Small technology firm Wimems Corp Bhd (WIME.KL: Quote, Profile , Research) recently said its external auditors had quit, it wanted more time to submit its 2006 accounts and that its financial sponsors, CIMB Bhd (BUCM.KL: Quote, Profile , Research), had resigned.

    As in the case of Transmile, shares of Bumiputra and Wimems took a beating. But unlike Bumiputra, shares of Wimems haven't staged a fight back: mired at 12 sen a share, the firm is worth just a fifth of the value of its October high.

What I would really like to know is the issue intent!

Was there an attempt to deceive the minority shareholders?

If so.. logically speaking, who wants to invest in companies one cannot trust?

I do hope that those who were found guilty of wrong doing to be prosecuted!

Thursday, May 31, 2007

Reviewing the events at TransMile

My dearest Moo Moo Cow,

Here is a summary of what was written on this blog on Transmile.

I first did a posting on TransMile back on Nov 18th 2005.

  • X We like Transmile for: (1) Its unique product, i.e. point-to-point express air transportation service; (2) Its ability to secure traffic rights for lucrative routes; and (3) Its EPS that is expected to grow at a CAGR of 67% between FY12/04 and FY12/07, backed by two full-fledged US-bound services. Maintain OUTPERFORM with a DCF-derived indicative fair value of RM12. In our DCF model, we apply a discount rate that is equivalent to Transmile’s WACC of 10.1% (based on a 20-year risk free rate of 6%, an equity premium risk of 7.5%, Transmile’s Beta of 1.07x, a target debt-equity ratio of 0.7x, and an average before-tax borrowing cost of 6% per annum).
A CAGR of 67% between fy12/04 and fy12/07? See how the Mile game was set back then in 2005! (This posting has an update here: Update on Transmile )

  • Note: Malaysian air cargo firm Transmile Group Bhd said on Wednesday a special accounting audit had found there may have been an overstatement in its revenue by 30 percent in 2006 and by 36 percent in 2005.
TransMile and its receivables was blown wide open here: Transmile Receivables

  • Validity of Transmile's 87 per cent higher pre-tax profit of RM206.7 million for the 12 months to December 31 2006, was questioned following the logistics group's failure to furnish its auditors with required data to substantiate the figures, Transmile told Bursa Malaysia yesterday.

Here's the 4th quarter report of the fiscal year earning, Quarterly rpt on consolidated results for the financial period ended 31/12/2006

Below is a snapshot of Transmile's balance sheet!


Fiscal year 2006 receivables were reported at 381.247 million, which is much more than the previous year fiscal year 2005 receivables of 111.113 million!

WOW!

I can understand why the auditors want to see more data!

Transmile opened limit down at 9.10 this morning. It is now trading at 9.95. A crisis buying opportunity? This is really risky because at this moment we do not know how drastic this issue is!

I was then asked, How about TransMile?

  • Any chance of light for transmile?? I still like the biz model despite the recent hoopla..

Given what is happening, from an investing perspective, what I believe we have is a whole bunch of unknown factors. At this moment of time, we do not know exactly what is happening and neither do we know the extent of the troubles, if any.

So frankly, I do not see how I would want to invest in Transmile at this moment of time because there is no way I could make a rational investing decision.

But the greatest risk is if TransMile is guilty of wrong doing. IF. And if that happens, one cannot really treat TransMile as a quality stock anymore. For the issue of integrity is then gone. Ah yes, the business model will still have value. But then it becomes a case where one is forced to value a company whose integrity has been shot to pieces!

Of course, if forced to, I could speculate and I could guess but all I am doing is I am speculating what would happen.

And frankly, this is simply beyond me and it's certainly beyond me to speculate if there is a chance of light for TransMile now.

On May 14th, I did the following posting, TransMile

The following table is taken without that quarterly earnings reported on Feb 2007. Have a look.

1. Clear built up in receivables.

2. nett debt kept on increasing!

Now the most important thing I would ask is where is the wealth generated?

From 04 Q3 to 06 Q3, the company said it generated sales of 1.476 billion ringgit and it said it earned 200.881 million.

Good numbers but look at the cash position. For a company earning 200.881 million, this company went from a nett debt of 123.861 million to 680.819 million!

The following table showed the inclusion of 06 Q4 earnings.

Quarterly rpt on consolidated results for the financial period ended 31/12/2006

Profits and cash increased substantially. nett debt decreased. Somehow.. the numbers do not tally... And given such data... perhaps... an investment in transmile could be questionable!

And then I wriote this other posting More on TransMile

  • ......there is speculation that management was perhaps under pressure to keep its numbers high to please investors and possibly facilitate a placement of shares completed in November last year that was largely taken up by foreigners.

In all honesty, all I can do is speculate what has had happened. And most of it is based on quoted stuff from news.

Which is really not intelligent at all.

Which is why the main grouse so far is perhaps best said by the Spore Btimes reporter saying why had the management not saying anything at all. And why had Bursa and SC remained silent?

That it had dragged on for so long indicates something was wrong in their accounts.

Right now, the issue would be, two things.

  1. How badly stated was their account?

  2. Was there intent?

Now those two issues would have a huge barring.

1. Transmile has had been priced for a growth stock. If their accounts were badly overstated then would it mean that the status of it being a growth stock is tarnished? And if so, then Transmile would probably not command the higher price earnings multiple it had enjoyed previously. And as noted, Transmile had done several placement issues in recent times. The POS placement was done around 30% and several various form of placement has been done. All of which will have an impact if one were to use the pe multiple as an indicator.

2. The issue of intent. This is by far more serious. The fact that Transmile went limit down on the first day and as mentioned by the press, foreign funds sold out. Damage has been done. If the allegations of intent were proven, I would seriously believe that these foreign funds would avoid Transmile like plague. So how much can our kampung fund do? And also, a lot of other investors would avoid this stock simply because it makes no sense to be an investor of a company whose owner/manager has been proven guilty in an attempt to cook their books. The issue of trust is but gone.

And if one adopts the rational approach, perhaps it simply makes no sense trying to be a hero in a hard place. Market is hot. Perhaps there is much better investment around for our hard earned money.

And what is the flipside of such a safer approach?

Well one missed an opportunity, that's all.

Does it hurt?

Nope.

The Market is always there, my friend. Other much better opportunities will arise in the future.

And then there was the question of a 50 Million Adjustment for TransMile?

So the Edge Weekly is suggesting that perhaps a 50 million adjustment is required.

Let's do some simple calculations.

The following table shows TransMile earnings.

\

So a 50 million adjustment could see fy 2006 earnings adjusted from rm157 mil to rm 100mil.

Now TransMile current number of shares is extremely tricky since it is ever expanding.

So as it is today, there are 270.118 million shares.

This means that TransMil eps 'could' be adjusted to a mere 37 sen, IF its earnings is adjusted by rm50 million to rm100 million.

So what PE multiple do you reckon TransMile could command after the adjustment?

Do you reckon it could command a pe multiple of 20x after this adjustment?

But if market take the adjustment poorly, TransMile could trade as low as a simple 15x multiple.

20x on an eps of 37 sen = 7.40

15x on an eps of 37 sen = 5.55!

How? Me? Honestly, I would rather not guess in such a fashion for I do not really know what is happening but a 50 million adjustment, could do some damage on TransMile in my opinion.

Last night:
  • Malaysian air cargo firm Transmile Group Bhd said on Wednesday a special accounting audit had found there may have been an overstatement in its revenue by 30 percent in 2006 and by 36 percent in 2005.
See The Full audit Statement on Transmile!

It's one terrible mess and I do not think it is advisable to hunt for value in such a stock!

Wednesday, May 30, 2007

The Full audit Statement on Transmile!

My Dearest Moo Moo Cow,

Here it is.

  • On 4 May 2007, the Directors of the Company received a letter from the Company's auditors, Messrs. Deloitte & Touche ("D&T") stating that D&T was unable to obtain the supporting documents from the management to satisfy D&T as to the fairness of the trade receivables and related sales to 18 companies identified by D&T. D&T also informed the Directors that they were unable to obtain satisfactory supporting documents for purchases of property, plant and equipment which amount was correspondingly credited to the unpaid balance owing by the 18 companies identified by D&T.

    As a result, the Board of Directors of the Company ("Board") expressed its concerns through the announcement dated 7 May 2007 as to the reliability of the unaudited consolidated results for the financial year ended 31 December 2006 announced on 15 February 2007, in particular, the items highlighted by D&T.

    On 7 May 2007, the Board appointed Moores Rowland Risk Management Sdn Bhd ("MRRM") to carry out a special audit on the issues mentioned above.

    This announcement is made in view of the Board's intention to maintain transparency of the findings by MRRM.

    1. FINDINGS OF SPECIAL AUDIT

    On 25 May 2007, MRRM issued a first interim report on its findings, a copy of which was submitted to the Securities Commission following a request by the Securities Commission.

    In the interim report, MRRM reported that:

    · In the financial year ended 31 December 2006,
    invoices were issued and recorded for purported services to 20 companies (comprising the 18 companies identified by D&T and 2 additional companies identified by MRRM) totalling RM333 million and representing 30% of the consolidated revenue stated in the unaudited consolidated results announced on 15 February 2007. This may result in an overstatement in the consolidated revenue by RM333 million;

    · Based on the unaudited consolidated financial statements as at 31 December 2006, the trade receiveables from the above 20 companies totalled RM236 million; and

    · In the course of the special audit, MRRM also noted that in the financial year ended 31 December 2005,
    invoices were issued and recorded for purported services to 19 companies (including 17 of the 20 referred to above) totalling RM197 million and representing 36% of the audited consolidated revenue of the Company for the financial year ended 31 December 2005. This may result in an overstatement in the consolidated revenue by RM197 million.

    For the purposes of illustration based on the above findings,
    on the assumption that TGB makes full provisions relating to the revenue recorded in respect of the companies mentioned above, the unaudited consolidated profit before taxation of the Company will be reduced by RM333 million for the financial year ended 31 December 2006, from RM207 million profit before taxation to a loss before taxation of RM126 million and the audited consolidated profit before taxation of the Company will be reduced by RM197 million for the financial year ended 31 December 2005 from a profit before taxation of RM120 million to a loss before taxation of RM77 million.

    The above illustration of the impact to profit before tax is subject to changes that may arise from the on-going special audit and the statutory audit for the financial year ended 31 December 2006 and does not take into account tax implications.

    The special audit by MRRM is still on-going in respect of the financial statements arising from the above.

    2. ON-GOING AUDIT

    The Company wishes to highlight that the special audit of MRRM is presently still on-going. Updates of any further material findings will be made in due course.

    In conjunction with the special audit, the Company will work towards finalising the annual statutory audit of the financial statements of the Company for the financial year ended 31 December 2006. With the findings of MRRM, the audited financial statements of the Company for the financial year ended 31 December 2006 are likely to include prior year adjustments.

    3. OPERATIONAL FRAMEWORK

    The Board has instituted the following:

    (a) A formation of an Executive Committee ("Exco") which assumes the authority of the Chief Executive Officer, arising from governance issues relating to the release of the announcement on the unaudited consolidated results for the financial year ended 31 December 2006, dated 15 February 2007 by the Board. The Executive Committee will be chaired by Mr Kuok Khoon Ho, and will comprise two other members of the Board, namely, Tan Sri A. Razak bin Ramli and Datuk Abu Huraira bin Abu Yazid. All of the Directors on the Exco are non-executive Directors of TGB;

    (b) The appointment of Mr Ong Teng Ping as the acting Chief Financial Officer. Mr Ong has been seconded from Chem Quest Sdn Bhd (a subsidiary of PPB Group Berhad), where he is a Director and the Group General Manager; and

    (c) On-going review of the systems to strengthen operations and internal controls of TGB and its subsidiaries ("TGB Group").

    4. CONTINUITY OF BUSINESS

    The TGB Group is keen to ensure the continuity of its business in providing express air cargo transportation services comprising international express freight services, chartering of aircraft, aircraft leasing and general freight services. The other services that are provided by the TGB Group include aircraft ground handling, aircraft maintenance, supply of aircraft parts, equipment and warehousing. In this respect, the TGB Group is presently actively engaging various stakeholders for its businesses including its principal customers, who are multinational cargo integrators, freight forwarders and courier companies, as well as its bankers, its shareholders and regulators, through appropriate channels.

    The TGB Group has in excess of 600 people with 49 managerial staff. It has its operational head office at Subang Airport and corporate head office in Damansara Heights.

    The Board is confident that the day-to-day business and service levels of the TGB Group will remain uninterrupted with the help of Group Chief Operating Officer, Robert Hyslop and the management team. With its landing rights and fleet of aircraft, the TGB Group is expected to continue to benefit from its niche within the express air cargo transportation market by providing its express air cargo transportation services.

Friday, May 18, 2007

What Kind of Warning is This?

My Dearest Moo Moo Cow,

I was just told about this newsclip on Star Biz.
Bursa Malaysia cautions investors on Transmile

  • Friday May 18, 2007

    Bursa Malaysia cautions investors on Transmile

    KUALA LUMPUR: Bursa Malaysia has warned players to be cautious of their investment decisions on Transmile Group Bhd's securities in view of the non-availability of reliable financial information on the latter.

    In a statement yesterday, the exchange said it viewed this seriously and had reminded the company to make necessary disclosures on its actual financial position to the market as soon as possible.

    On Feb 15, 2007, the company announced an unaudited pre-tax profit for the year ended Dec 31, 2006 of RM206.73mil.

    Subsequently, on May 7, the board expressed concern on the reliability of the unaudited consolidated results.

    Transmile is involved in providing air-freight, aircraft engineering and maintenance services. – Bernama

TransMile receivables issue was known on May 7th. ( See Transmile Receivable. )

A warning to the investors only on May 18th?

Seriously my dearest, I wonder for whom this warning serves?!

Really!

Tuesday, May 15, 2007

50 Million Adjustment for TransMile?

My Dearest Moo Moo Cow,

So the Edge Weekly is suggesting that perhaps a 50 million adjustment is required. Let's do some simple calculations.

The following table shows TransMile earnings.


So a 50 million adjustment could see fy 2006 earnings adjusted from rm157 mil to rm 100mil.

Now TransMile current number of shares is extremely tricky since it is ever expanding.

The follow screen shot shows TransMile current number of shares today.


So as it is today, there are 270.118 million shares. This means that TransMil eps 'could' be adjusted to a mere 37 sen, IF its earnings is adjusted by rm50 million to rm100 million.

So what PE multiple do you reckon TransMile could command after the adjustment? Do you reckon it could command a pe multiple of 20x after this adjustment?

But if market take the adjustment poorly, TransMile could trade as low as a simple 15x multiple.

20x on an eps of 37 sen = 7.40
15x on an eps of 37 sen = 5.55!

How?

Me?

Honestly, I would rather not guess in such a fashion for I do not really know what is happening but a 50 million adjustment, could do some damage on TransMile in my opinion.

More on TransMile

My Dearest InvestBullbear,

You wrote the following.

......there is speculation that management was perhaps under pressure to keep its numbers high to please investors and possibly facilitate a placement of shares completed in November last year that was largely taken up by foreigners.

Extracted from the Edge this week:


  • Extracted from the Edge this week:

    On Monday, May 7, while the counter was suspended, it announced that the unaudited results showing a pre-tax profit of RM 206.734 million for last year were unreliable.

    The clues for solving Transmile’s mystery lie in the company’s announcement, particularly in the part where the auditors state that “they have not been able to get hold of supporting documents from the management on certain transactions relating to trade receivables and related sales and additions to property, plant and equipment”.

    What exactly is the “accounting relation between trade receivables and related sales, and additions to property, plant and equipment” that the company is talking about?

    “Some amount of trade receivables was paid not in cash, but in the form of property, plant and equipment where the documents are not available. That is the problem,” a source says.

    The said amount is about RM 50 million.

    An accounting official says there could be a related party transaction with Transmile, for example, in which it provided a service to the related party. The payment for the service may have been made later in the form of property, plant and equipment. However, the absence of proper documentation to substantiate the transaction could have prompted the auditors to refuse to sign off the accounts.

    This begs the question: Are the accounting woes of Transmile simply a matter of poor record-keeping or a scheme to obliterate the paper trail, which could raise doubts about the legality of those transactions?

    There is also another view that the problem could have started in FY2005, which explains why the documents cannot be found.

    More importantly, is the amount so big that it will impact Transmile significantly?

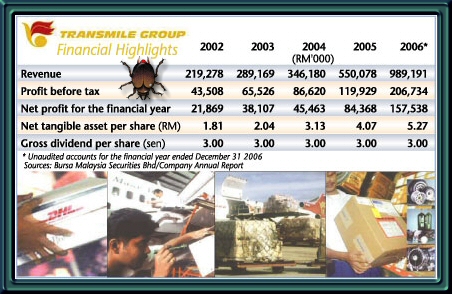
    To get an idea of the quantum of the amount in dispute, analysts are looking at Transmile’s trade receivables, which ballooned to RM381 million in FY2006 from RM111 million the previous year. This is despite an 80% increase in revenue to RM 989.2 million in FY2006 from RM550.1 million the previous year.

    The point to note here is that the receivables accounted for much of the company’s sales growth. Hence, if a large part of the figures has to be provided for, Transmile’s net profit of RM157.5 could be revised down significantly.

    With no guidance from the company on the worst-case scenario, analysts are looking at a complete wipe-out of Transmile’s profits for FY2006 amounting to RM157.5 million.

    JP Morgan’s Lucius Chong believes that a 5% restatement of Transmile’s earnings is the best- case scenario.

    In FY2006, Transmile’s cash and bank balance almost doubled to RM417.7 million from RM261.2 million in the previous year. Its property, plant and equipment figures showed a slight decrease to RM 1.55 billion from RM1.57 billion a year ago.

    But in FY2005, Transmile’s property, plant and equipment revealed an increase of RM1 billion due mainly to the purchase of aircraft, parts and equipment. (In May 2005, Transmile took delivery of four MD11 aircraft. In the same year, it also acquired two Boeing 727 aircraft, which were supposedly delivered in 2006.)

    The facts and figures are at the disposal of investors. Still, it may not be easy to detect any discrepancies due to the lack of information on the accounts.

    Another point to note is that if it is a matter of unsubstantiated transactions, how can the appointment of another accounting firm help solve the matter in about a month?

In all honesty, all I can do is speculate what has had happened. And most of it is based on quoted stuff from news.

Which is really not intelligent at all.

Which is why the main grouse so far is perhaps best said by the Spore Btimes reporter saying why had the management not saying anything at all. And why had Bursa and SC remained silent?

That it had dragged on for so long indicates something was wrong in their accounts.

Right now, the issue would be, two things.

  1. How badly stated was their account?
  2. Was there intent?
Now those two issues would have a huge barring.

1. Transmile has had been priced for a growth stock. If their accounts were badly overstated then would it mean that the status of it being a growth stock is tarnished? And if so, then Transmile would probably not command the higher price earnings multiple it had enjoyed previously. And as noted, Transmile had done several placement issues in recent times. The POS placement was done around 30% and several various form of placement has been done. All of which will have an impact if one were to use the pe multiple as an indicator.

2. The issue of intent. This is by far more serious. The fact that Transmile went limit down on the first day and as mentioned by the press, foreign funds sold out. Damage has been done. If the allegations of intent were proven, I would seriously believe that these foreign funds would avoid Transmile like plague. So how much can our kampung fund do? And also, a lot of other investors would avoid this stock simply because it makes no sense to be an investor of a company whose owner/manager has been proven guilty in an attempt to cook their books. The issue of trust is but gone.

And if one adopts the rational approach, perhaps it simply makes no sense trying to be a hero in a hard place. Market is hot. Perhaps there is much better investment around for our hard earned money.

And what is the flipside of such a safer approach? Well one missed an opportunity, that's all.

Does it hurt?

Nope.

The Market is always there, my friend. Other much better opportunities will arise in the future.


rgds,


**** this blog posting is reproduced from a Sahamas posting. please feel free to voice your opinions. ****

Monday, May 14, 2007

TransMile

My Dearest Smart Investor,

The following is a compiled quarterly tables on TransMile. Data is taken from Bursa Website.


The following table is taken without that quarterly earnings reported on Feb 2007.Have a look.

1. Clear built up in receivables.

2. nett debt kept on increasing!

Now the most important thing I would ask is where is the wealth generated?

From 04 Q3 to 06 Q3, the company said it generated sales of 1.476 billion ringgit and it said it earned 200.881 million.

Good numbers but look at the cash position. For a company earning 200.881 million, this company went from a nett debt of 123.861 million to 680.819 million!

The following table showed the inclusion of 06 Q4 earnings.


Quarterly rpt on consolidated results for the financial period ended 31/12/2006

Profits and cash increased substantially. nett debt decreased.

Somehow.. the numbers do not tally...

And given such data... perhaps... an investment in transmile could be questionable!

Tuesday, May 08, 2007

Transmile Receivables

My Dearest Moo Moo Cow,

Published on today's Business Times,
Transmile to audit latest financial figures .

Highly interest because the auditors are seeking more data!

  • Validity of Transmile's 87 per cent higher pre-tax profit of RM206.7 million for the 12 months to December 31 2006, was questioned following the logistics group's failure to furnish its auditors with required data to substantiate the figures, Transmile told Bursa Malaysia yesterday.

And the data required were linked with certain transaction relating to trade receivables and related sales and additions to property, plant and equipment.

  • "The company's auditors have not been able to obtain relevant supporting documentation from the management on certain transactions relating to trade receivables and related sales and additions to property, plant and equipment," Transmile said.
Here's the 4th quarter report of the fiscal year earning, Quarterly rpt on consolidated results for the financial period ended 31/12/2006

Below is a snapshot of Transmile's balance sheet!


Fiscal year 2006 receivables were reported at 381.247 million, which is much more than the previous year fiscal year 2005 receivables of 111.113 million!

WOW!

I can understand why the auditors want to see more data!

Transmile opened limit down at 9.10 this morning. It is now trading at 9.95. A crisis buying opportunity? This is really risky because at this moment we do not know how drastic this issue is!

Anyway, this reminds me of The Receivales Issue and Megan once more!

Wednesday, February 15, 2006

Update on Transmile


I wrote the following blog posting on Transmile last year.

Transmile reported it's earnings today:


TABLE: Malaysia's Transmile 4Q Net MYR43.7M Vs MYR18.2M


Transmile Group Bhd (7000.KU) - Malaysia
4th quarter ended Dec. 31:
Figures are in Ringgit (MYR).
2005 2004
Revenue MYR306,687,000 MYR128,124,000
Pretax Profit 64,005,000 39,329,000
Net Profit 43,740,000 18,160,000
Earnings Per Share 19.96 Sen 10.61 Sen
Dividend 3.00 Sen 3.00 Sen
12 months ended Dec. 31:
Revenue 606,210,000 346,180,000
Pretax Profit 120,959,000 86,620,000
Net Profit 85,852,000 45,463,000
Earnings Per Share 39.19 Sen 26.55 Sen
Dividend 3.00 Sen 3.00 Sen


~~~~~~~~~~~~~~~~~~~~~~~

Now that's really a nice result... which means Transmile last 4 quarterly net earnings displayed a strong earnings growth per quarter like this below...

Q1 net profit = 10.816 mil, Q2 net profit = 13.206 mil, Q3 net profit = 18.090 mil, Q4 net profit = 43.740 mil

Impressive?

Slight problem... cos if you look at the blog posting again Mile High Projection , I wrote the following issue...

Now this one tiny-little-itsy-bitsy-problem.

Ze market sifus is EXPECTING and PROJECTING (some call it assuming - LOL - making ze ass-out-of-u-and-me mah) a net profit of over 105 million for the current fiscal year.


Transmile did a very impressive 85.852 million, however as impressive as the earnings is, this set of earnings numbers is way BELOW the so-called sifu's estimates!

Oh.... oh... how?

Makes you wonder... did Transmile did so poorly or did the sifu itself did so poorly!!!!!

Here's a newsclip on Transmiles earnings: Transmile's net profit up 88.8% in FY05

Friday, November 18, 2005

Mile High Projection.

In today's Star Biz, there is a piece on Transmile down on worries over 2005 result .

Makes me wonder cos i do know that Transmile performance for its current fiscal year 2005 has been rather decent.

The following is Transmil net earnings this fiscal year.

Q1 net profit = 10.816 mil, Q2 net profit = 13.206 mil, Q3 net profit = 18.090 mil.

As can been seen its net earnings has been improving each quarter.

Beh pai mah. Tiok boh?

And its current nine-month net profit total of 42.112 million is much more than its last year nine-month profit for the same period of 27.296 million.

Now this one tiny-little-itsy-bitsy-problem.

Ze market sifus is EXPECTING and PROJECTING (some call it assuming - LOL - making ze ass-out-of-u-and-me mah) a net profit of over 105 million for the current fiscal year.

LOL!!!

Comeon.... isn't such projection way too rosy? Way too optimistic?

Look at simple maths.

3 quarters done and Transmile has managed only 42.112 mil.

Soooooo.... in order to meet ze market sifus projections of 105 mil... and with only ONE quarterly earnings left in Transmiles current fiscal year.... what ze market sifus are saying is that they expect and they ASS-U-ME dat Transmile will make 62.888 mil (105 minus 42.122 = 62.888) for that remaining Q4 earnings.

Aisehhhhhhhhhhhh lah..... like dis can meh?

From
10.816mil -> 13.206 mil -> 18.090 mil -> 62.888 mil??

Comeon...... be a bit more realistic lah.... !!!!!

Tiok boh???

And here is a snippet (in blue italic) of their write-up...

X We like Transmile for: (1) Its unique product, i.e. point-to-point express air transportation service; (2) Its ability to secure traffic rights for lucrative routes; and (3) Its EPS that is expected to grow at a CAGR of 67% between FY12/04 and FY12/07, backed by two full-fledged US-bound services. Maintain OUTPERFORM with a DCF-derived indicative fair value of RM12. In our DCF model, we apply a discount rate that is equivalent to Transmile’s WACC of 10.1% (based on a 20-year risk free rate of 6%, an equity premium risk of 7.5%, Transmile’s Beta of 1.07x, a target debt-equity ratio of 0.7x, and an average before-tax borrowing cost of 6% per annum).

Can see onot?

A CAGR of 67% between fy12/04 and fy12/07?

!!!!!!!!!!!!!!!!!!!

Gosh..... now that's a mile high projection lah!

Ohhh.... and when the stock does not meet such lofty projections assigned by these market sifus... those stock are considered to be performing below market expectations!

Gee.... so what is ur expectation?

Mine?

I think its still rather dark in my ninja-turtle-shell lah!

:D