Showing posts with label Notion Vtec. Show all posts

Monday, October 04, 2010

Notion VTec Denies Article Published On The Edge Financial Daily

On today's Edge Financial Daily: Notion Vtec to gear up after shelving share placement

  • KUALA LUMPUR: Hard disk drive (HDD) component manufacturer Notion VTec Bhd plans to gear up after shelving a plan to place out a 10% stake in the company following the fall in its share price.

    Chairman and executive director Thoo Chow Fah told The Edge Financial Daily that the company is in the process of securing a bank loan of around RM80 million to finance the expansion of a new plant, after seeing its share price plunge 30% over the last two months to RM1.65 last Friday, close to its 15-month low of RM1.50 on Sept 1.

    For 3Q2010 ended June 30, both the group’s long- and short-term borrowings stood at RM91.32 million, while cash and bank balances stood at RM32.51 million. With shareholders’ equity of RM224.96 million, its net gearing stood at 0.26 times.

    Thoo expects the group’s gearing to rise to around 0.4 time when the bank facility is approved, of which he is confident because Notion has “a good credit line with the bank”.

    In April, Notion announced a plan to place out a 10% stake to raise RM45.9 million, to be used to buy equipment and machinery for its new 2.5-inch HDD manufacturing plant in Klang.

    At that time, Notion’s shares were trading at a much higher level of RM3.50.

    The entire new plant is to be rolled out in three phases and will cost RM150 million over two years. The plant is expected to significantly boost its current production level of baseplates.

    But due to unfavourable market conditions and lower demand for HDD, which have affected Notion’s share price recently, Thoo said the private placement exercise had to be cancelled.

    In January, the company placed out a 10% stake to Nikon Corp to raise RM33.78 million to expand its single lens reflex (SLR) camera parts manufacturing plant in Thailand.

    The RM150 million, 2.5-inch HDD plant is already facing setbacks with a high rejection rate of baseplates due to a steeper than expected learning curve.

    High rejection rates at the die casting and machining stage have been reported, resulting in delays in reaching production targets.
    It was also reported that Notion has set a turnaround deadline by next March to resolve its manufacturing issues.

    Thoo had said recently that the learning curve at the new plant is longer than expected.

    But he described these as short-term setbacks and was optimistic that the 2.5-inch baseplate project will eventually bear fruit.

    For 3QFY2010 ended June 30, Notion’s revenue rose 36% year-on-year (y-o-y) from RM44.71 million to RM60.81 million, while net profit fell 73% y-o-y to RM2.97 million from RM11.09 million.

    This was attributed to initial start-up costs such as R&D, depreciation, materials and labour, and foreign exchange movements. EPS, meanwhile, dropped from 7.88 sen to 1.92 sen.

    Thoo said that demand for HDD is weak at the moment, so the company is expecting lower revenue for 4QFY2010 compared with 3Q due to lower HDD orders.

    “We also expect minimal contribution from the 2.5-inch baseplate project as we tackle the problems of casting, machining and ED coating and getting the stator assembly into operation.

    The higher than anticipated rejects arising from this baseplate project are to be finalised and the loss will be taken up in 4Q.

    We therefore do not expect the net margins to improve in the quarter,” the company said in a statement.


    This article appeared in The Edge Financial Daily, October 4, 2010.

Cancellation of the private placement is a huge deal, yes?

When asked by Bursa Malaysia, Notion Vtec gives the following reply:

  • We refer to the above article which appeared in The Edge Financial Daily, Home Business Section, page 4, on 4 October 2010.

    Referring to the statement "...Thoo said the private placement exercise had to be cancelled", we wish to clarify that Mr Thoo Chow Fah, the Executive Chairman of Notion VTec did not make such statement to The Edge Financial Daily as implied in the article.

    The Board of Directors of Notion VTec, after due inquiry with all the directors and major shareholders of the Company as well as all such other persons reasonably familiar with the matter, wishes to clarify that as at to-date, the proposed share placement has not been cancelled.

    This announcement is dated 4 October 2010.

So what's up?

Thursday, August 05, 2010

Update On Notion Vtec's Earnings

Notion reported its earnings and as 'suspected' it was ARGGGGGLEEEE!

Here's my updated earnings table for Notion Vtec.


In the posting
Is The Downgrade From RHB On Notion Vtec Fair? , I said the following:

  • If I have to throw in a dart, I would say perhaps an earnings of 32 million for Notion for its fiscal year 2011. LOL! Yes, that low. :P

With an earnings of just 2.969 earnings... looks like my dart throw could be extremely optimistic at this moment of time!

Anyway, from Notion earnings notes, the company said the following:

  • For 3Q of FY2010 the Group recorded revenue of RM60.8 million (2QFY2010 : RM56.7 million) and PAT of RM3.1 million (2QFY2010 : RM12.2 million) and earnings per share of 1.92 sen (2QFY2010 : 8.06 sen). The lower earnings is mainly attributable to initial start up cost of new projects such as R&D, depreciation of machineries, materials and labour whereas the earnings will only come on stream in the following quarters. There were quality issues for one of our HDD components which resulted in rectification and compensation cost. The Group were also affected by the weaker USD and Euro for the quarter under review.

    The Group recorded PBT of RM3.9 million as compared to the immediate preceding quarter of RM15.5 million, a decrease of 74.8%.

    For the current year todate, total revenue was RM173.9 million and PAT was RM29.3 million compared to the corresponding period of the preceding year of RM118.2 million and RM22.9 million respectively. Yoy the revenue and profit after tax was 47% and 28% higher respectively. The better performance is mainly attributable to higher revenue.

The profit guidance.... WAS MOST WORRYING!

  • The Group did not issue any profit guarantee and profit forecast during the current financial period to date. However, the Company has in November 2009, provided internal management targets for revenue of between RM220 million to RM240 million and profit after tax of between RM50 million to RM55 million for the financial year ending 30 September 2010, barring unforseen circumstances. The guidance is an internal management target and is not an estimate, forecast or projection. The internal targets has not been reviewed by the external auditors.
    The Board after considerable deliberation wishes to advise that the management target for profit after tax will be revised downwards to between RM33 million and RM35 million for the year ending 30 September 2010 due to reasons set out below. The revised guidance has not been reviewed by the external auditors.

WOW!

Notion is revising its earnings 'guidance' for 2010 to just 33-35 million! (huhu! My dart target for 2011 is 32 million. Huhu! Not too bad after all!)

Currently, 3 quarters earnings is already 29 million.

Which means... next quarter earnings won't be nice also!

ps: Aha... I guess from the earnings notes, it was Notion who guided the analyst with earnings around 50-55 million!

Now let me paste from my earlier posting...

  1. RHB's 2011 net earnings forecast for Notion is 56 million. (LOL! Downgraded since then)
  2. Kenanga's 2011 net earnings forecast for Notion is 62 million.
  3. CIMB's 2011 net earnings forecast for Notion is 80.8 million.
  4. 4. And here comes the champion... OSK... OSK's 2011 net earnings forecast for Notion is 95.0 million.

So Notion guidance was already high.. but somehow folks from Kenanga and CMB were even more optimistic than Notion itself!

And OSK? LOL! Those guys are just in a league of their own! LOL! 95 million!

In the posting Stocks Are Flying To The Orbit But Investors Keeps Cashing Out!, I received the following comments:

  • The Emperor said...
    What happened to Notion today ? The share price was half dead until about 4.30pm. Trading below its overnight price of RM2.10. At 4.36pm, the share price went ballistic. It moved from RM2.05 at 4pm to RM2.20 at 4.50pm. Half the day's volume was traded at RM2.20 !!! Please explain as I am stupid.

Yup the stock did went ballistic at 4.36!!!


Now that Notion's earnings is soooooo poor... that late show from Notion has a whole new meaning eh?

Yeah.. me also stupid. :D


Anyway on the Edge: Notion VTec 3Q earnings slip to RM2.97m, cautious on 4Q
  • KUALA LUMPUR: NOTION VTEC BHD [] posted net profit of RM2.97m in its third quarter ended June 30, 2010, down sharply from the RM11.1 million a year ago as earnings were impacted by the initial start-up cost of new projects and it is cautious about the fourth quarter

    It said on Thursday, Aug 5 revenue for 3Q rose 36% to RM60.8 million from RM44.71 million a year ago but expects the 4Q revenue to be lower due to lower orders from the hard disk drive (HDD) components sector. Earnings per share shrank to 1.92 sen versus 7.88 sen.

    "The lower earnings is mainly attributable to initial start up cost of new projects such as R&D, depreciation of machinery, materials and labour whereas the earnings will only come on stream in the following quarters," it said.

    Notion VTec said there were quality issues for one of its HDD components which resulted in rectification and compensation cost. The group were also affected by the weaker US dollar and euro for the quarter under review.

    "The group recorded pre-tax profit of RM3.9 million as compared to the immediate preceding quarter of RM15.5 million, a decrease of 74.8%," it said.

Now some of Notion's minority shareholders are not going to be happy. Apparently they were told of a bright future just last month during the company's EGM! Yes, in exactly one month, suddenly the managment is telling that earnings is going to be poor!

How can? How is this possible?

Now on the EdgeMalaysia, on the 7th July, they published the following article: Notion Vtec to kickstart ops at RM150m HDD plant

  • Notion Vtec to kickstart ops at RM150m HDD plant
    Written by Aishah Mustaphah
    Wednesday, 07 July 2010 11:33

    KUALA LUMPUR: Notion Vtec Bhd is poised to begin the first-phase operations at its largest hard disk drive (HDD) manufacturing plant in Klang by early next month, the entire development of which will cost RM150 million over the next two years.

    Under a three-phase development, the new 200,000-sq ft facility will eventually have a total production capacity of 84 million 2.5-inch HDD baseplates annually, a significant boost from the current four million baseplates.

    The rollout of the first phase entails production of 24 million pieces a year, with Samsung as a major client.

    The first phase will be partly funded through the company’s latest proposed private placement of new shares of up to 10% of the company to institutional investors.

    The placement proceeds are expected to total RM45.9 million and will be used to buy new equipment and machinery costing up to RM78 million and renovation of RM2 million. The remaining capital expenditure for the first phase and for the second and third phases will be generated from internal funds and bank borrowings.

    Last January, Notion Vtec raised RM33.78 million from placing out a 10% stake to its client, Nikon Corporation, towards expanding its single lens reflex (SLR) camera parts manufacturing plant in Thailand.

    Speaking after the group’s EGM here yesterday, Notion Vtec’s executive chairman Thoo Chow Fah said its current placement would not go towards another client. “We are looking at a few institutional investors to come in,” he said.

    For its second quarter ended March 31, 2010 (2QFY10), the group’s revenue growth was flat at RM56.7 million versus RM56.3 million in the preceding quarter. Revenue contributions are currently derived from HDD (48%), SLR camera (36%), and industrial/automotive (16%).

    2QFY10 net profit fell to RM12.2 million from RM14 million a year earlier due to the initial start-up costs of new projects in Thailand and the baseplate project, earnings from which would only come onstream in the following quarters.

    For the six months to March 31, 2010, Notion Vtec’s revenue totalled RM113 million and net profit was at RM26.2 million. Year-on-year, revenue and net profit were 54% and 122% higher, respectively. The strong growth is attributed to recovery in all its business segments.

    As at March 31, 2010, its long-term borrowings stood at RM52.28 million while short-term borrowings came up to RM25.9 million, while shareholders’ equity amounted to RM224.12 million, giving a gearing of 0.35 times. Cash and cash equivalents stood at RM56.85 million.

    For this year’s outlook, Thoo expects strong growth from the SLR camera segment, after last year’s economic downturn.

    “I see Nikon’s growth as very strong, especially coming to the end of this year,” he said, adding that the production of the new facility will have much of a positive impact on its bottom line this year, but that would be seen next year instead.

    As solid state drives (SSD) are making headway towards replacing some usage of HDD, Thoo believed that HDD would have a shelf life within the next 10 years.

    “As we go along, we are always aware of disruptive technologies. As for SSD, I believe there will be a complementing space for both of them. HDD is still one of the cheapest and reliable sources of storage for another 10 to 15 years. We are also moving into the 2.5” HDD as well as 3.5” HDD,” said Thoo.

    The 2.5” HDD is typically used for mobile devices such as laptops while the 3.5” HDD is pervasive in personal computers.

    Thoo said the group was constantly looking at cost-cutting measures. He said it was looking at recycling scrap aluminium that could serve as raw materials for its HDD baseplates. “We have found a site for it and we are now waiting for approval,” said Thoo.

    This article appeared in The Edge Financial Daily, July 7, 2010.

Wednesday, August 04, 2010

ECM Now Says Sell Notion With A Target Price Of 1.85!

So I featured RHB dramatic reversal in recommendation for Notion Vtec in the posting: Is The Downgrade From RHB On Notion Vtec Fair?

Now get a load of this.

In the posting
Some Comments On Notion Vtec, I remarked that ECM Libra made the following posting ECM Libra ups target price for Notion Vtec

Now this same posting can be seen on the Edge Financial Daily.
ECM Libra ups target price for Notion Vtec

  • ECM Libra ups target price for Notion Vtec
    Written by Financial Daily
    Tuesday, 27 July 2010 10:41

    Notion Vtec Bhd
    (July 26, RM2.65)
    Maintain buy at RM2.74 with higher target price of RM3.74 (from RM3.63):
    We hosted a corporate luncheon recently for Notion VTec which was attended by a good crowd of buy-side analysts and fund managers. Management gave some good insights and outlook for the HDD business which will be the main growth driver in the coming years.

    We understand from management that due to pricing issues, debt financing will be used instead. Nonetheless, the 1-for-5 free warrants exercise will proceed as planned.

    Management believes the 2.5-inch HDD segment is where growth is due to (i) the explosive growth of data, (ii) high growth of external HDDs and (iii) high growth of mobile PCs against desktop PCs.

    By year-end, Notion expects capacity for the 2.5-inch HDD components (base plates, spindle motor hubs) to reach two million per month under its first phase. Notion currently produces 400,000 to 500,000 per month for Samsung. Subsequently, the second and third phases will proceed with each phase requiring about six months each for total capacity to reach four million per month and eventually seven million per month. Management hinted that due to political uncertainties in Thailand and the need to oversee the new plant in Klang, any major expansion in the Thai plant will likely be completed only sometime in 2011. Notion is looking to expand floor space from 25,000 to 225,000 sq ft.

    Orders for HDD business have been very positive so far though there was a slowdown in June. It is difficult to tell if the slowdown is simply temporary. Also, Notion is working to bring down rejection rates in its new Klang plant from 10% to 12% to 5%. In the interim, margins may be affected.

    We raise FY2010/12 EPS forecasts by 3% to 5% to account for (i) the aborted private placement, (ii) higher interest costs, and (iii) dilution from the in-the-money warrants. Hence, we revise our target price from RM3.63 to RM3.74 based on an unchanged PER multiple of nine times on mid FY2010/11 earnings. We are positive that progress in the new Klang plant is on track, and believe once quality issues are ironed out, margins should improve and earnings growth should accelerate. —
    ECM Libra Investment Research, July 26


    This article appeared in The Edge Financial Daily, July 27, 2010.

That was just last Tuesday.

Now today, ECM Libra downgraded Notion to a mere 1.85!

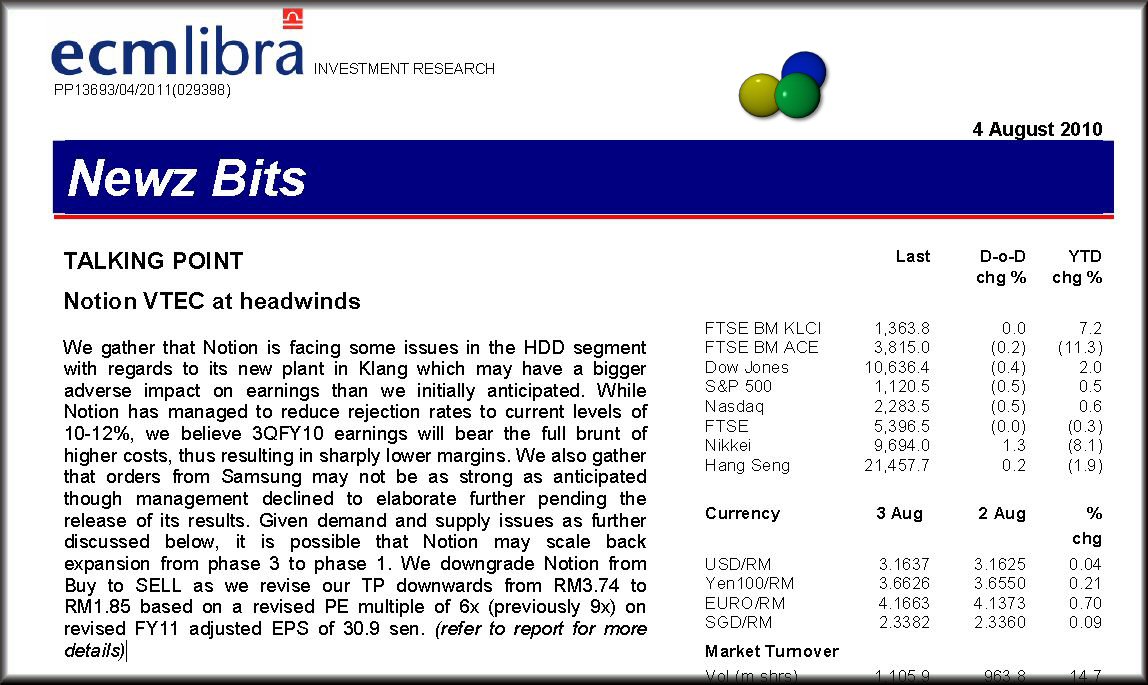
  • Notion VTEC at headwinds
    We gather that Notion is facing some issues in the HDD segment with regards to its new plant in Klang which may have a bigger adverse impact on earnings than we initially anticipated. While Notion has managed to reduce rejection rates to current levels of 10-12%, we believe 3QFY10 earnings will bear the full brunt of higher costs, thus resulting in sharply lower margins. We also gather that orders from Samsung may not be as strong as anticipated though management declined to elaborate further pending the release of its results. Given demand and supply issues as further discussed below, it is possible that Notion may scale back expansion from phase 3 to phase 1. We downgrade Notion from Buy to SELL as we revise our TP downwards from RM3.74 to RM1.85 based on a revised PE multiple of 6x (previously 9x) on revised FY11 adjusted EPS of 30.9 sen.

Holy cow!

That's even faster and a bigger downgrade than RHB Research!

Reasoning aside... think about it... think about the implication here on the investing public who relies on such research reports for their investing decisions.

On 27th July, ECM comments were accessible to all via the broadcast on the Edge Financial Daily: ECM Libra ups target price for Notion Vtec

Price then was 2.65. Now including 27th July, six trading days has passed since.

6 trading days.

That's all it took for ECM to downgrade Notion from a TP of 3.74 to a mere 1.85!

Holy cow!

Is The Downgrade From RHB On Notion Vtec Fair?

Yesterday I blogged on Notion Vtec because the stock price had been falling rather dramatically in the posting Some Comments On Notion Vtec and apparently RHB had downgraded Notion Vtec.

And the Edge Financial Daily even highlighted this issue yesterday:
Notion VTec top loser on downgrade

Here's the link to RHB's report:
Notion Vtec Berhad : Not As Good As Hoped - 03/08/2010


  • ♦ Warning for 3Q results. The market yesterday beat us to the punch, de-rating Notion’s share price by 10.3%. We believe 3QFY9/10 results (to be announced on 5 Aug) are likely to be worse than expected due to higher costs incurred from the RM80m expansion of the 2.5” Hard-Disk Drive (HDD) baseplate capacity and lower revenue after adjusting for the weaker US$ vs. RM. Conditions are not expected to improve in 4QFY9/10.

    ♦ Outlook dimmed due to competition and weak demand. The outlook for 4QFY9/10 and beyond now appears more negative compared to the more bullish view after our visit to the company in May. We note that major HDD manufacturers including Western Digital and Seagate recently guided that lower-than-expected HDD demand caused by EU debt problems and slow US recovery has been compounded by capacity oversupply in the industry. Aggressive competition has thus resulted in falling prices and diminishing margins. The upside from Samsung’s aggressive expansion plans in the 2.5” HDD segment also appears to have evaporated

    ♦ Forecasts cut. We have cut our FY9/10-12 EPS forecasts by 21.1%, 36.2% and 47.4% respectively, after factoring in 25-35% lower sales and lower margins. We had originally expected baseplate capacity to rise from 350-400/month currently to 1m/month by end-FY10, 5m/month in FY11 and 7m/month in FY12, but the likelihood now is that the company will stop at 2m/month in FY11 while further capacity expansions will be on hold for now. We note that 80% of the capex has already been spent. For FY10, revenue has also been affected by the -7.7% YTD decline in the US against the ringgit. However, we note that we are still looking at the RM/US$ exchange rate coming back to around RM3.20-3.30 by year end.

    ♦ Risks to our view. 1) Recovery in demand if US economic growth strengthens earlier than expected; and 2) Fluctuations in RM/US$ exchange rate.

    ♦ Downgrade. Although the camera segment remains resilient and will provide some support to revenue growth, the focus will likely remain on the negative outlook for PC sales growth and the oversupply of HDDs. Our fair value has been cut to RM2.07 based on our new forecasts and a more conservative target FY9/11 PER of 8x (vs. 10x previously). Although yesterday’s share price fall suggests that the market has already factored in this negative view, we believe there is still downside risk given the uncertain earnings outlook. We thus downgrade our call on the stock to Underperform from Outperform.


Here's Notion Vtec numbers..


As it is Notion Vtec's most recent 4 quarters or trailing twelve months earnings is already some 50.553 million.

RHB's earnings forecast for Notion fy 2010 has been cut from 53.6 mil to just 41.25 mil.
RHB's earnings forecast for Notion fy 2011 has been cut from 72.4 mil to just 44.8 mil.

Of course the cuts are drastic.

RHB mentioned Western Digital itseself had been guiding lower earnings forecasts.

From yesterday posting: Some Comments On Notion Vtec

  • So Western Digital says it expects the coming quarter, Q1 eps to be around 80 to 90 sen.
    Wastern Digital Q4 EPS was 1.23. (Street was expecting 1.35)
    From an eps of 1.23 to an eps of just 80-90 sen is rather a huge decline, yes?

RHB also mentioned the following factors.

  1. higher costs incurred from the RM80m expansion of the 2.5” Hard-Disk Drive (HDD)
  2. revenue has also been affected by the -7.7% YTD decline in the US against the ringgit.
  3. Aggressive competition has thus resulted in falling prices and diminishing margins

Are the reasoning valid?

Yes, some would point out that they DID NOT like the TIMING of the downgrade!

On 16th July, which was not long ago, Notion Vtec was trading at 2.99. Why didn't RHB Research warn the investing public then? Why ONLY release the report when Notion Vtec had fallen to a low of 2.35? Notion closed yesterday at 2.11.

Isn't the timing of the downgrade way too late?

And the previous RHB Research report was made on 20th May 2010:hNotion Vtec Berhad : Set To Deliver - 20/5/2010

Yeah.. anothe massive complaint then because Notion price in May was 2.73 and RHB gave Notion an Outperform with a target price of 4.68!

Yes the grouse and utter frustration is understandable because the investing public were told by RHB Research that Notion Vtec is deemed to have a GREAT FUTURE on 20th May 2010. It's now only the beginning of August!

How can a company value diminish from 4.68 to 2.07 in just 2 months?

How can?

Here's the first two paragraphs of the RHB's report in May 2010.

  • ♦ On track to deliver 2.5’’ baseplate target. According to management, construction work on its new 150k sq ft plant is near completion. The new plant which is expected to house most of the base plate production capacity is set to commence production by Sep-10. Note that management expects capex of around RM80m to ramp up the base plate capacity to 1m/month, 5m/month, and 7m/month by FY10-12 respectively from 350-400k/month (currently) vs. 100k/month in Jan-10, pending the arrival of additional equipment and machinery i.e. die casting and computer numerical control (CNC) machines. Additionally, management is planning to increase the total workforce to 3,000 by 2011 (vs. 1,900 currently).

    ♦ Riding on volum e loading for Western Digital (WD). The company expects stronger volume loading in 2H2010 from WD on the back of strong demand for HDD components i.e. antidisks, disc clamps, and spacers as well as WD’s market share gain. Recall that WD overtook Seagate as the number one HDD vendor in 1Q10. WD now expects to increase its total HDD shipments by more than 20%. While Notion’s current capacity for these components is 800-900k/month, management is expecting to increase capacity to 1.5-2.0m/month by end-2010....

Ah... apparently RHB Research was guided by Notion's management notes in May.

And the warrants issue. Sorry but let me repeat this again.

  • Did you see OSK's report on Notion Vtec dated 16th July 2010. Notion then was 2.99 and since the conversion price for the warrants was priced at 2.55, OSK shouted out very loud that one was getting free warrants that was 'in the money'! It's now 3rd August 2010, and the warrants are no longer in the money! :P), perhaps one should use 169 million shares as the potential share base for Notion Vtec. This is to prevent the investor from being shocked by the dilution in earnings.

Putting the quality issue of OSK aside ( LOL! Yeah, what's new mate? :P) these warrants went ex yesterday, 3 Aug 2010. Entitlement is based on a 1 for 5. And some 34,003,503 were issued. With the conversion price at 2.55, some might want to account for the possible dilution in eps caused by conversion of the warrants.

Ok, let's take Western Digital's guidance numbers as a guide. Western Digital says it expects its earnings per share to drop from 1.23 to around 80-90 sen. Now the worse case 80 sen eps would represent a decline of 34.9%!!

And we do have to factor in the current strength in the Ringgit versus USD (is the Ringgit really strong or the USD really weak? :P ). What would be your guesstimate of the impact on Notion since Notion's products are priced in the USD? Would you say maybe a 5% impact caused by the exchange rate? Fair assumption? Or perhaps the impact is minimal? ( Why? Because if you look at the latest report pdf file from Notion, Notion currently has an existing USD50 million hedged to its USD receivables. )

But then ... some might argue that perhaps RHB is being far too negative. Why? Notion Vtec does NOT cater to HDD segment only!

From Notion's last earnings report.

  • In Q2FY2010, HDD parts revenue recorded RM26.9 million (Q1FY2010: RM19.1 million), camera parts recorded RM20.4 million (Q1FY2010: RM26.7 million) whilst the industrial/automotive revenue was at RM9.2 million (Q1FY2010: RM10.5 million). The product mix for the Q2FY2010 was HDD:Camera:Industrial/Automotive of 48%:36%:16% compared to previous quarter's mix of 34%:47%:19%. The HDD revenue increased by 40% whilst the camera sector was lower by 24% compared to Q1FY2010.

Hmmm.... HDD revenue increased by 40% in Q2Fy2010!

And what about me?

If I have to throw in a dart, I would say perhaps an earnings of 32 million for Notion for its fiscal year 2011. LOL! Yes, that low. :P

LOL! Stop starring la. I am NOT a Sotong and that's my darts figure and surely I could be dead wrong. :P

Now RHB's earnings per share is based on just 154 million. The last approved placement share of 15.4 million shares, which has not been placed out yet, has been currently discounted by RHB.

Let's see two scenarios. One with 154 million share base and the other with 169 million shares.

  1. With 154 million share base, an earnings of 32 million equates to an eps of 20.7 sen.
  2. With 169 million share base, an earnings of 32 million equates to an eps of 18.9 sen.

And what would be the fair PEx multiple you would use?

And so far, apparently RHB is the ONLY research house to downgrade Notion's Vtec earnings.

Now in the posting Update On Notion VTec. on 4th May 2010, I noted some of the other earnings forecast made on Notion Vtec.

  • RHB's 2011 net earnings forecast for Notion is 56 million. (LOL! Downgraded since then)
  • Kenanga's 2011 net earnings forecast for Notion is 62 million.
  • CIMB's 2011 net earnings forecast for Notion is 80.8 million.
  • And here comes the champion... OSK... OSK's 2011 net earnings forecast for Notion is 95.0 million.

How?

You want to BUY Notion now because you think Notion has dropped a lot?

Or you want to do a wait and see. Yeah, wait for Notion's quarterly earnings notes, which should be announced this month, first.

How?

Tuesday, August 03, 2010

Some Comments On Notion Vtec

Notion the shares has been plunging and since I had made several postings on it, I thought perhaps it's best I make some comments or two on the stock.


The first thing I would always refer to is if there exist any negative news that might impact the stock.

On the Edge Financial Daily yesterday, there was this article HDD makers continue to fall

  • Written by Koo Jie Ni
    Monday, 02 August 2010 11:33

    KUALA LUMPUR: JCY International Bhd and Notion VTec Bhd continued their downward trend last Friday, as Western Digital’s dour quarterly forecast warning sent stocks of hard-disk drive (HDD) manufacturers reeling.

    JCY and Notion VTec are fellow manufacturers of HDD components, although the latter has also diversified into production of camera and automotive parts.

    News reports on July 21 had it that international HDD maker Western Digital attributed its forecast profit dip to laggard spending patterns, European debt worries and lower prices....

I find it rather ironic. :D

Of course, as an investor, one would regard Western Digital's profit warning as important BUT in May 2010, Notion Vtec management did warned too regarding future profits. See posting Update On Notion VTec.

  • Management warned that there is some risk that capacity ramp-up and product testing costs for its 2.5” base plate and spindle motor lines could dampen earnings in the next two quarters

And in April 2010, I blogged on the potenial earnings dilution caused by the continous share placements.

  1. Honey, My Notion's Earnings Per Share Has Shrunk!
  2. Reply To Notion's EPS Dilution Caused By Share Placements

And my concern as stated in the second posting was:

  • However, let me stress that we are now looking at an increase of 29.270 million new shares, which works out to a 20.8% increase from the initial share base of 140.717 million.

    And in my opinion, this is simply way too much in such a short time frame. January 2010, share base increase by 10%. Now Notion wants to increase by another 10%.

    If one is a minority shareholder, what would one expect?

    Which means, after these two share placements, Notion Vtec earnings has to increase by more than 20.8%, in order for the minority shareholders to see 'real growth' in their earnings per share.

    Would this be possible?

Now something had happened... on the 27th July, ECM Libra ups target price for Notion Vtec

  • We hosted a corporate luncheon recently for Notion VTec which was attended by a good crowd of buy-side analysts and fund managers. Management gave some good insights and outlook for the HDD business which will be the main growth driver in the coming years.
    We understand from management that due to pricing issues, debt financing will be used instead. Nonetheless, the 1-for-5 free warrants exercise will proceed as planned.

So apparently, there's a chance that the second share placement would not happen.

Management said it was due to pricing issues.

But from an investing perspective or from a conservative perspective, shouldn't one question why?

Yes, besides pricing, why wasn't Notion Vtec able to perform this share placement? Why can't Notion Vtec able to attract new investors? Are the investors sceptical? Do they know something we don't?

But then of course, the 'opportunist' might say that perhaps this sell down is a 'strategy' to push down Notion Vtec's shares so that it could be able to priced out these share placements.

Well, frankly, I do not discount that. Yes, I think it's possible but if that was the case and I am the minority shareholder now, how could I possibly be happy if this was the case?

But as it is.... it's mere speculations.

Hmm... Notion Vtec was supposed to announced its earnings in July 2010. (Its previous quartely earnings was posted on 29th April 2010)

Anyway from a dilution point of view, since Notion Vtec has NOT officially announce on Bursa website in regards to the second batch of placements, I guess perhaps from an earnings dilution perspective, it's best one to remember the following table..


Discounting the warrants (lol! Did you see OSK's report on Notion Vtec dated 16th July 2010. Notion then was 2.99 and since the conversion price for the warrants was priced at 2.55, OSK shouted out very loud that one was getting free warrants that was 'in the money'! It's now 3rd August 2010, and the warrants are no longer in the money! :P), perhaps one should use 169 million shares as the potential share base for Notion Vtec. This is to prevent the investor from being shocked by the dilution in earnings.

So what did Western Digital warned about? Western Digital warns of weak Q1, shares slide

  • * Q4 EPS excluding items $1.23 vs Street view for $1.35
  • Western Digital executives warned that heightened competition from companies like of Hitachi and Seagate Technology (STX.O) will pressure margins, while demand in the current quarter is expected to stay weak amid economic turmoil in Europe and lackluster U.S. consumer demand
  • For the current quarter, Western Digital expects revenue of $2.35 billion to $2.45 billion and earnings per share of between 80 cents and 90 cents. That is sharply below analyst expectations of $2.6 billion in revenue and earnings per share of $1.47 for the current quarter, according to Thomson

So Western Digital says it expects the coming quarter, Q1 eps to be around 80 to 90 sen.

Wastern Digital Q4 EPS was 1.23.

From an eps of 1.23 to an eps of just 80-90 sen is rather a huge decline, yes?

So that was a massive profit warning from Western Digital, yes?

And so how for Notion Vtec?

Surely there's going to be an impact yes?

And unfortunately, Notion Vtec at this moment of time, Notion VTec shares has increased and if Western Digital profit warning holds true, then do you think that there's a strong chance that Notion Vtec's EPS could see a bigger decline?


ps: This posting is as it is. I do not know if Notion will continue to fall or make a rebounce. Please contact your nearest Sotong if you really require such information.

Tuesday, May 04, 2010

Update On Notion VTec.

Simple quesion.

Is Notion capex via share placement justifiable?

I will not use my reasoning but I would explore and attempt to interpret the comments made by our local pros after their analyst meeting with Notion's management.

Here are some comments from RHB.

  • Forecasts. While we are positive on Notion’s long-term earnings outlook, we are maintaining our forecasts for now. Management warned that there is some risk that capacity ramp-up and product testing costs for its 2.5” base plate and spindle motor lines could dampen earnings in the next two quarters. Nevertheless, longer term, we believe there is potential upside to our FY11-12 forecasts arising from: 1) stronger-than-expected sales of spindle motor hubs and 2.5’’ base plates; 2) stronger contribution from its Thailand and Klang operations, capitalising on the rapid expansion of key customers, Alphana Tech and Samsung; and 3) Higher contribution from the auto segment.

    ♦ Investment case. We maintain our indicative fair value of RM4.64 based on a target FY09/11 PER for now although we note that after adjusting for the potential dilution arising from the proposed 10% private placement and 1-for-5 rights issue of free warrants,
    our fair value would fall to RM3.87.

    Nevertheless this would still imply 22.1% upside. Maintain Outperform.

RHB are positive on the long term outlook, yeah they understand that ther managment had warned on future profits BUT nevertheless they are maintaining their earnings forecasts on Notion.

And when one adds in the potential dilutions, RHB's fair value for Notion would fall by 16.6% to rm 3.87.

RHB's 2011 net earnings forecast for Notion is 56 million.

From Kenanga Research:

  • Tweaking our FY10 numbers with net 6.6% lower factoring higher depreciation and interest charges on the back of higher than guided capital expenditure. FY11 revenue is revised up 19% on assumed 1.9m monthly run rate for base plates but net is only up 2.4% due to skew towards lower margin HDD components. Taking into account possible 15.5m new shares from the coming placement exercise, new EPS of 36.4sen is derived. Applying a 10x multiple to FY11F will yield a new target price of RM3.64 (RM3.84 previously). Our numbers carry upside risk should management ramp up guidance of 5m pieces / m onth is achieved for FY11. We continue to like the group for its strong execution track record and opportunistic move to capture a larger HDD market share. Current weakness on possible arbitraging from the coming placement exercise represent good buying opportunity. BUY maintained.

So Kenanga is optimistic but as optimistic as they are, the net earnings expectations for FY10 is lowered by 6.6% and fy11 is only revised up by 2.4%.

End result? Target price is lowered to rm 3.64.

Kenanga's 2011 net earnings forecast for Notion is 62 million.

CIMB Research:

  • The key takeaways from Notion’s 2QFY9/10 results briefing were i) its robust FY11 guidance, ii) confirmation of the Alphana contract, iii) more clarity on its proposed corporate exercises, iv) the clearing up of the quality issue and) the increase in its capex and debt guidance. The positive surprise was the significantly higher FY11 guidance and new camera revenue while the negative surprise was the higher capex and borrowings associated with it. The net effect of higher earnings for the Alphana contract and the increase in the share base from the placement and warrants issue is a 1% increase to a 13% decline in our EPS forecasts for FY10-FY12. Our target price falls from RM4.46 to RM4.05, still based on a 20% P/E discount to its peers or 9.3x CY11 P/E but now pegged to the fully enlarged share base. We retain our OUTPERFORM recommendation in view of the catalysts of i) new customers, ii) production of higher value-added parts, iii) strong earnings contribution from Factory 3, and iv) supply of more components to a wider audience.

A 13% decline in EPS forecast. Target price is adjusted to rm4.05.

CIMB's 2011 net earnings forecast for Notion is 80.8 million.

And here comes the champion.... OSK. :P

  • Tweaking up FY11 earnings. Based on management’s FY11 revenue guidance for 2.5” HDD base plates of RM228m and assuming a 12% net profit margin from this particular program as well as 25% organic FY11 earnings growth from its existing business, we are increasing our FY11 earnings forecast by 12%. For the 2.5” HDD business, we have assumed a low 12% net profit margin in case Notion experiences high yield loss in the course of manufacturing these new components and to factor in the initial start-up losses for the third factory. Having said that, the start-up losses could be potentially mitigated by lower plating costs in FY11.

    32% dilution from corporate exercises. Based on our estimates, Notion’s FY11 net profit is expected to soar by 71% in FY11 on an expected 54.3% earnings growth in FY10. However, its FY11 EPS growth is estimated at 18% on factoring in a maximum 49.4m shares to be issued from the proposed private placement exercise and free warrants issue.

Huhuhu... Notion’s FY11 net profit is expected to soar by 71% in FY11 on an expected 54.3% earnings growth in FY10.

So target price is increased from 3.55 to 3.88!

ps: in the posting Honey, My Notion's Earnings Per Share Has Shrunk! one would have noted that I said OSK Target price for Notion was 3.38. Yes that is correct. On April 30th, after Notion released its earnings, OSK increased its target price from rm 3.38 to rm 3.55. (maybe they saw it looked strange and maybe they saw my remarks "( err... target price is 3.38, Notion was trading at 3.26. - seriously wonder how on earth they can call it a buy with the target price a mere 12 sen or a mere 4% upside. But then.. what can I expect.. it's OSK! LOL!)

See this is not about me picking on OSK. LOL! But only they can make such upgrades. On 30th April 2010, they upgraded Notion from 3.38 to rm 3.55. On 3rd May, or the next trading day, OSK upgrade Notion again to rm 3.88!!! Upgrades are so easy, huh? :P

OSK's 2011 net earnings forecast for Notion is 95.0 million.

So how?

Let's chuck OSK's report to the other side and look at the comments made by RHB, CIMB and Kenanga. All their target prices are revised lower, no thanks to the dilutions in earnings per share.

How?

Did the share placements helped?

And if the share placements are good, why are the target prices lowered?

On the other hand, what if a rights issue was made instead of the placements?

Would that not be a better option?

Friday, April 30, 2010

Reply To Notion's EPS Dilution Caused By Share Placements

Got the following reply on my posting Honey, My Notion's Earnings Per Share Has Shrunk!

  • Shien Yang said...

    Hi there,the EPS is definitely going to get diluted this year. But u need to understand what the private placement is for. They need the money for the huge capex that they are going to incur this year for their capacity expansion.

    The result for all these money spent u will see it in FY11 when their net profit will jump again due to more than 3x increase in their production capacity for HDD parts.

Hello.

Regarding what the private placement is for... err.. well, I could actually write something like this ....

Let's have a look at recent events. ( Ok, I won't stretch it so far back.)

Let's look and assume that one bought Notion in mid Nov 2009. Why? Based on impressive earnings.

This was the earnings announced on 10th Nov 2009. Quarterly rpt on consolidated results for the financial period ended 30/9/2009

Notion then reported a sales revenue of 54.339 million and an earnings of 13.029 million. Previous quarter it made some 11.087 million only. An impressive jump in earnings.

Earnings then was based on 703.583 million shares.

In the very same month, Notion did a share consolidation. 5 into 1. Meaning the number of shares will be consolidated into 140.717 million shares.

Notion has 20.470 million in its cash balances and some 58.274 million in total loans.

The share placement of 10% was announced a month earlier. Announcement - Proposed Private Placement.pdf

Rationale of the placement explained in the pdf link above.

  • NVB announced on 2 October 2009 that its wholly-owned subsidiary, Notion (Thailand) Co. Ltd has entered into an agreement to acquire a parcel of land with a factory located thereon. The proceeds from the Proposed Private Placement will be utilised for the extension of the existing factory, purchase of machinery and to defray expenses incidental to the Proposed Private Placement. The plant in Thailand is expected to commence operations during the 1st quarter of 2010.

    After due consideration of the various methods of fund raising, the Board is of the view that the Proposed Private Placement is currently the most appropriate method of fund-raising as it would enable the Company to raise the funds required which would otherwise have to be financed through bank borrowings thereby resulting in interest savings to NVB and its subsidiaries (“Group”).

And then on 19th Jan 2010. NOTION VTEC BERHAD (“NVB” or “Company”) Private placement of up to ten percent (10%) of the issued and paid-up share capital of the Company (“Private Placement”)

  • HwangDBS Investment Bank Berhad, on behalf of the Board of Directors of NVB (“Board”), wishes to announce that the Private Placement has been completed with the listing of 13,844,694 new ordinary shares of RM0.50 each in NVB (“Placement Shares”) on the Main Market of Bursa Malaysia Securities Berhad on 18 January 2010. The Placement Shares were placed to Nikon Corporation (“Nikon”), which has a global standing in the manufacture and sale of camera-related products, such as digital cameras, as well as binoculars and other optical products for consumers, such as ophthalmic lenses.

Nikon Corporation was the buyer of the placement of shares.

The placement raised...


  • The proceeds raised approximately RM33.78 million.

And the strange thing was ...

  • The proceeds raised approximately RM33.78 million which will be used for the NVB Group’s expansion plans in Thailand which will add an extra floor space of 200,000 sq ft to the Group's facilities and defraying expenses incidental to the Private Placement. The Thailand plant will, in the initial stage, mainly cater for Nikon (Thailand) Co Ltd which has indicated that there will be more orders for the cam barrels and possible sub assemblies in the near future.

So Notion Vtec placed 10% shares to Nikon and the proceeds is then used in Notion's expansion plans in Thailand. This adds an extra floor space of 200,000 square feet. And this expansion caters for Nikon's orders.

Feb 2010, Notion announced this earnings. Quarterly rpt on consolidated results for the financial period ended 31/12/2009

On a q-q basis, sales increased from 54.339 million to 56.329 million. Net earnings improved from 13.029 million to 14.185 million.

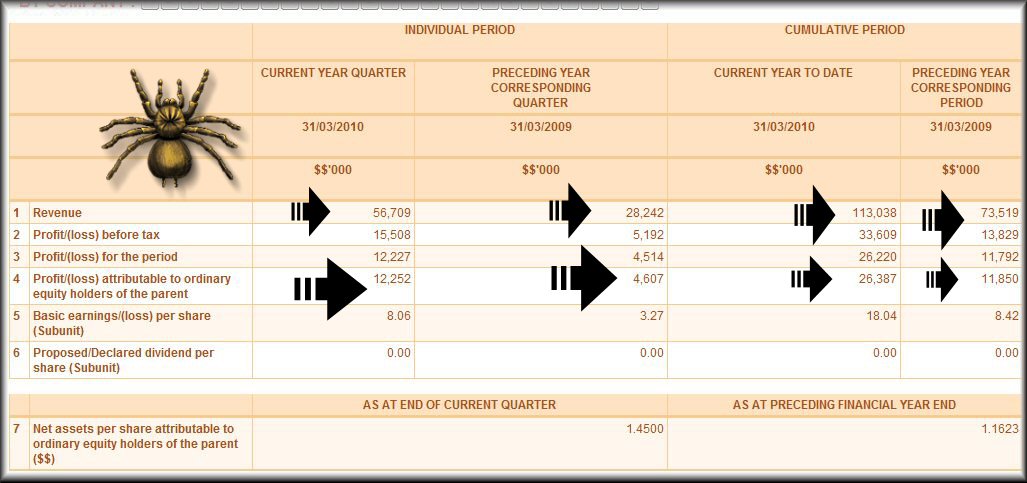
Yesterday's earnings. Notion's sales were rather flat at 56.709 million. Net earnings slipped to 12.522 million.

The cash raised from Notion's placement to Nikon can be seen in Notion's cash balances indicating clearly that Notion had yet to deploy the proceed from its placement to Nikon. Which is understandable.

Now the rationale of the placement yesterday.

  • The Placement Shares are intended to be placed out to long-term institutional investors and/or strategic investors and will enable NVB to raise gross proceeds of up to RM46.06 million (based on the indicative issue price per Placement Share of RM2.98) to fund future capital expenditure for its centralised 2.5” HDD baseplate manufacturing facility in Klang, working capital and to defray expenses incidental to the Proposals. The Board is of the view that the Proposed Private Placement is the most appropriate method of raising funds as the funds required would otherwise have to be financed through bank borrowings which would result in the NVB Group incurring interest cost.

So two placements. One to Nikon and another in the works.

How?

Now all that would have been extremely tedious and so long winded, yes? :D

So for your question on whether I do understand what the private placements for. Well I do understand and I did read Notion Vtec's explanation for the need of the placement of shares.

Frankly, IF I were a shareholder, I would have preferred a rights issue, where all the minority shareholders are given an EQUAL and FAIR chance to participate in the company's expansion program. Yes, if all the minority shareholders reckon that the expansion plans are justifiable, why aren't they given a chance to participate? Why exclude them?

And in certain cases, certain private placements have a history of being shady (not saying that this is case with Notion).

A share placement sale or a private placement excludes and it prevents the minority shareholder the chance to participate EQUALLY.

Yes, if I were asked to vote, I would always VOTE AGAINST private placements. (I do hope you understand that this is my flawed personal preference, ok?)

  • They need the money for the huge capex that they are going to incur this year for their capacity expansion....

    The result for all these money spent u will see it in FY11 when their net profit will jump again due to more than 3x increase in their production capacity for HDD parts.

Now needless to say, since Notion claimed that all these money raised will be used for capex, surely one would imagine that the money spend should result in more net profit growth. That's the logical expectation and assumption. I have no problems with such reasoning.

However, let me stress that we are now looking at an increase of 29.270 million new shares, which works out to a 20.8% increase from the initial share base of 140.717 million.

And in my opinion, this is simply way too much in such a short time frame. January 2010, share base increase by 10%. Now Notion wants to increase by another 10%.

If one is a minority shareholder, what would one expect?

Which means, after these two share placements, Notion Vtec earnings has to increase by more than 20.8%, in order for the minority shareholders to see 'real growth' in their earnings per share.

Would this be possible?

Well those that really know me understand that I always feel that anything is possible.

So I let you be the judge and if you think the placement and the future prospects derived from the share placements is justifiable, do please buy more shares of Notion. :D

Who knows right? After all the plant expansions, Notions earnings could double or even triple, yes? That's a possibility yes?

But what if this does not happen? This is also a possibility, yes?

Me? Well I am only highlighting the issue of the dilution impact caused by these share placements. Whether the share goes up or down, it's beyond me. Really.

Honey, My Notion's Earnings Per Share Has Shrunk!

Notion reported it's earnings last night. On a q-q basis, it showed some weakness.

Here are some brief comments from the 'pros' on Notion recently.

The 'poor earnings' is expected said RHB Research!

  • 2QFY10 results preview . Notion Vtec (NVB) will release its 2QFY10 results on 29 April. We estimate net earnings to fall marginally 5-7% qoq (vs. +9.2% qoq) to around RM13m due to: 1) seasonal factors; 2) strengthening of RM against the USD (+4.3% qoq); and 3) higher expenses stemming from the capacity ramp up in 2Q. This would bring 1HFY10 net profit to around 54-55% of our FY10 previous net profit forecast and around 53-54% of consensus estimates. However, we expect a strong qoq growth in 3Q-4Q10, driven mainly by: 1) higher volume loading of base plates from Samsung and strong contribution from higher margin spindle motor hub

However they still insist that it's a BUY.

  • Investment case. We are maintaining our indicative fair value of RM4.59 based on a target PER of 10x FY 11 EPS. Hence, we reiterate an Outperform call on the stock.

On the Edge Financial Daily last week: Inter-Pac: Notion Vtec forging ahead

  • We remain positive on Notion on the back of strong growth coming from both the HDD and SLR camera segments. Nevertheless, Notion is exposed to currency fluctuation as most of their HDD sales are carried out in the US dollar. The strengthening of the ringgit versus the US dollar will bite its bottom line slightly. Our fair value of RM3.78 is based on FY11 earnings per share (EPS) of 36 sen and PER of 10.5 times. — Inter-Pacific Research, April 20

KN in its most recent notes:

  • Maintain forecast with unchanged target price of RM3.60 based on 11x CY2010F. Outlook for HDD remained robust with HDD majors including Seagate and Western Digital continuing to guide positively for the June quarter. BUY.

OSK had a trading buy call on 28th April ( err... target price is 3.38, Notion was trading at 3.26. - seriously wonder how on earth they can call it a buy with the target price a mere 12 sen or a mere 4% upside. But then.. what can I expect.. it's OSK! LOL!)

  • Maintain Trading Buy and earnings forecasts. In the meantime, we do not expect Notion
    to lose the other two antidiscs programs. The affected antidiscs program should have minimal impact on its FY10 and FY11 earnings.

However, this is not what I want to talk about.

Here is a snapshot of Notion's earnings. It's IMPRESSIVE.


Sales is now on a different level and the jump in net profit can be clearly seen.

It's a wonderful set of results.

However... there's an issue.

Here's Notion's previous quarterly earnings:
Quarterly rpt on consolidated results for the financial period ended 31/12/2009

Net earnings was 14.185 million. This quarter is only 12.252 million. Ah..yes the weakness in earnings as suggested by RHB.

Yes but this is NOT my issue.

Let's have a look at the earnings per share.

Now if one open the earnings notes on Notion's previous earnings, ( here
is the link to the pdf file ), and look at page 8, one would see that Notion has stated it's earnings was based on 140.717 million. So from an earnings of 14.185 million, Notion's earnings per share is some 10.1 sen.

Notion's earnings reported last night was 12.252 million. Now if based on 140.717 million, Notion's earning per share should be some 8.7 sen.

But if you look at the screen shot, Notion's earnings per share stated was only 8.06 sen. An error?

No it was not. In yesterday earnings notes, Notion's earnings per share is based on 151.946 million.

And if I open my live quotes, here is what I am looking at.


Notion share base is now some 154.561 million.

Increased yet again.

Last night, beside reported its earnings, Notion announced the following:

  • On behalf of the Board of Directors of NVB, Hong Leong Investment Bank Berhad wishes to announce that the Company proposes to undertake the following:

    (a) Proposed issue of new ordinary shares of RM0.50 each in NVB (“NVB Shares”) not exceeding 10% of the issued and paid-up share capital of the Company through a private placement exercise;

    (b) Proposed issue of up to 34,003,503 free warrants in NVB (“Free Warrants”) on the basis of 1 Free Warrant for every 5 NVB Shares held by the shareholders of the Company; and

More placements (Actually this is an OLD issue. See this OLD blog posting Notion Special Issues of Shares ) but this placement is sweetened by 'free warrants'.

Now if I open the pdf file attached, this is what I am looking at.


So before the warrants are given free... Notion's share base is to be enlarged to some 169.987 million.

Let's look at the impact.

From the earnings snap shot, we see Notion's earnings for 2 quarters was some 26.387 million.

Based on last quarters number of shares of 140.717 million, Notion's eps would equate to some 18.8 sen.

However, if based on this enlarged share base of 169.987 million, Notion's eps would be only 15.5 sen.

Now keeping it simple, let's assume that this was Notion's total fiscal earnings and that the market assigns a fair value earnings multiple of 12x to the stock. Yeah, a PE of 12. (Ass-u-me only, ok?)

Now based on an eps of 18.8 sen, Notion's fair value should be 12x18.8 ~ 2.26.

Now based on an eps of 15.5 sen, Notion's fair value should be 12x15.5 ~ 1.86.

See the difference?

The earnings per share has shrunk and so has the assumed target price!

How?

Do you like such share 'placements'?

And can you see how these share placements dilute your earnings?

Here's Notion's charts..


Tuesday, October 27, 2009

Regarding Notion Vtec

Got the following comments:

  • ronnie said...

    Dear Mr Moola,Notion has been in the news lately. It is an engineering subcontractor that enjoys profit margins that exceed 20%. The people in the company must be engineering wizards because when work is outsourced, the profit margins are usually controlled by the customers. The input and output are controlled by customers. This is a major reason for outsourcing the work in the first place. Other investors familiar with this industry may be able to shed more light on this.

    The other issue that puzzles me is why does the company buy back its shares in the millions and sell its shares aggressively?

Just for the record. Last blogged: Notion Vtec II

Issue 'then' was some decline in earnings + that 'Special Issues of Shares' issue.

Now.. present day, present time.

How now? Are you a trader or an investor?

If you are a trader, all it matters is the stock is IN the news and from the charts, it look as if there is some happening stuff. Whether it's good or it's bad, it's your own interpretation. Sorry I cannot guide you here.

But if you are an investor.

The past Special Issues of Shares tells you a lot of the company. Could you trust a company like this? It's like how could one invest or a be a business partner with parties you cannot trust? Does it make sense?

Now in regards the issues you are addressing.

  • The people in the company must be engineering wizards because when work is outsourced, the profit margins are usually controlled by the customers. The input and output are controlled by customers. This is a major reason for outsourcing the work in the first place.

You doubt the margins. If you doubt it, why bother? Why seek to be convinced for the sake of it?

  • The other issue that puzzles me is why does the company buy back its shares in the millions and sell its shares aggressively?

Again WHY?

Why is it doing stuff like this?

As an investor can you trust such a company?

If you cannot trust, why bother talking about value?

How?

Why the interest now? Should you be an 'investor' just because the stock is hot in the news?

How?

Sorry but I have no answers for you?

Thursday, August 23, 2007

Notion Vtec II

Notion announced its earnings, Quarterly rpt on consolidated results for the financial period ended 30/6/2007

Have a look at this table which shows its quarterly earnings since listing.


There is a drastic drop in earnings and there was drastic erosion in its earnings margins.

The company explained in its earnings notes.

  • COMPARISON WITH PRECEDING QUARTER'S RESULTS

    The Group recorded lower revenue of RM22.23 million in the quarter under review (“Q3 2007”) as compared to RM28.28 million achieved in the previous quarter (“Q2 2007”). PBT decreased from RM10.01 million in Q2 2007 to RM2.23 million in Q3 2007. PBT margin also decreased from 35.4% in Q2 2007 to 10.0% in Q3 2007.

    The comparatively weaker performance in Q3 2007 was mainly attributed to the following:

    (a)Lower contribution from the camera components business segment due to significantly lower sales orders from the major SLR camera manufacturers. The poor performance of the camera segment was mainly attributed to high camera inventory levels experienced by the industry, which generally is the norm as seasonally the camera market tends to be soft during this time of the year.

    For Q3 2007, the Group achieved a product mix ratio (HDD: Camera: Industrial segments) of 53%: 22%: 26% compared to 54%: 29%: 17% ratio achieved in Q2 2007.

    (b)The HDD segment was also adversely affected by increased competition, resulting in its margins being squeezed coupled with lower volume orders from some of its major customers.

    (c)Impact of the strengthening Ringgit (RM) against the US Dollar (USD), particularly, for export orientated companies. Consequently, the Group suffered foreign exchange losses which arose from the difference in book RM/USD rate compared to the realized RM/USD rate.

How?

You have the lower earnings and then you have the Special Issues of Shares to consider.

Monday, August 06, 2007

Notion Special Issues of Shares

My Dearest Alvan,

  • Recently, if you read the announcement properly, Notion's major shareholders sold off portion of their shares to comply with with NEP requirement (i.e. 30% bumiputra spread). So, they are not diposing it because of the change in prospect or fundamental. Furthermore, there is no new share issued, so there is no dilution of share value. Correct me if I am wrong.
Subject: NOTION VTEC BERHAD ("NOTION" or "Company") I. PROPOSED BONUS ISSUE II. PROPOSED SPECIAL ISSUE III. PROPOSED INCREASE IN AUTHORISED SHARE CAPITAL IV. PROPOSED AMENDMENTS TO THE COMPANY'S MEMORANDUM OF ASSOCIATION (COLLECTIVELY REFERRED TO AS THE "PROPOSALS")

If you read that announcement,


  • 1. (b) special issue of 103,500,000 new NOTION Shares ("Special Issue Shares"), representing 17.65% of the enlarged issued and paid-up share capital of NOTION (after the Proposed Bonus Issue), to Bumiputera investors to be approved by the Ministry of International Trade and Industry ("MITI") at an issue price to be determined later ("Proposed Special Issue");
If you open up that Wordfile attached, you will see a table which clearly states what is happening.

Or you can see the screenshot below.


At the end, AFTER the proposed special issue, Notion was supposed to have an enlarged share capital of 689.819 million shares.

So correct me if I am wrong, after the special issue, the share based is enlarged. Is this not a dilution of earnings?

Some interesting links which shows the extension of time and the revisions made on this special issue of shares.

30th Nov 2006, Notion made a revision to this special issue:
NOTION VTEC BERHAD ("NOTION" or "Company") Revisions to the Special Issue

22nd Jan 2007. Notion made an extension.
NOTION VTEC BERHAD ("NOTION" or "Company") Extension of time to comply with the 30% Bumiputera Equity Condition

27th March 2007. Another extension.
NOTION VTEC BERHAD ("NOTION" or "Company") Extension of time to comply with the 30% Bumiputera Equity Condition

17th May 2007. Another extension.
NOTION VTEC BERHAD ("NOTION" or "Company") - Revision to the Promoters' Placement; and - Extension of time to comply with the 30% Bumiputera Equity Condition

  • On behalf of the Board of Directors of NOTION, HWANGDBS Investment Bank Berhad (formerly known as Hwang-DBS Investment Bank Berhad) (formerly known as Hwang-DBS Securities Berhad), is pleased to announce that the Ministry of International Trade and Industry ("MITI") has, vide its letter dated 15 May 2007 (which was received on 16 May 2007) taken note and has no objections to the following:

    (i) Revision to the collective placement of existing ordinary shares of RM0.10 each in NOTION ("Notion Shares") by the promoters of NOTION, from 125,895,000 to 147,500,000 NOTION Shares to Bumiputera investors to be approved by the MITI ("Promoters' Placement"); and

    (ii)
    Out of the 147,500,000 NOTION Shares, the remaining balance of 51,000,000 NOTION Shares will be allocated by the MITI to Bumiputera investors to be identified later.

    MITI is agreeable to the above, provided that the Company obtains the approval of the Securities Commission ("SC") for the Promoters' Placement, and complies with the Guidelines on the Acquisition of Interests, Take-Overs and Mergers by Local and Foreign Interests.

    In this regard, the SC's approval was obtained on 4 April 2007.

    This announcement is dated 17 May 2007.

Quote: Out of the 147,500,000 NOTION Shares, the remaining balance of 51,000,000 NOTION Shares will be allocated by the MITI to Bumiputera investors to be identified later.

How?

Saturday, August 04, 2007

Notion Vtec

My Dearest Newbie,


  • I would like to seek your second opinion on Notion Vtec as this stock is currently trade at RM0.45 which i would think it's strongly under-valued. I realized the recent sell-off by it's major shareholder and directors was due to complying listing rules, would this cause the temporary down-trend? Although it's listing history is only two years but the fast growth was impressive, together with the healthy financial status.

Regarding shareholders transactions. Let me repeat what I had mentioned the other day.

  • In my opinion, tracking shareholding transactions is one of the most complex things an investor could do.

    I for one could not make heads or tails in most transactions.

    Are the shareholders right or are they wrong in each of their purchase/disposal transactions?

    Me? I always have no idea.

    Could never make any consistent intelligent decisions in such matters.

Regarding its earnings.

Here is an extremely simplistic Notion Vtec earnings track record. At this moment of time, Bursa website is down, hence I can get no verification of the numbers posted and also I cannot go much more in details. However, gauging from what you have written, I am assu-u-ming that you are interested in Notion due to its earnings growth.

And as can be seen from the earnings table above, the current trailing twelve months earnings (TTM) showed that Notion earned a whopping 29.299 million for the last 12 months, which gives a solid indication that fiscal 2007 will simply be grand for Notion. (Do note, I am discounting the quality of these reported earnings since the Bursa website is down)

Anyway, ass-u-ming a rough estimate earnings of some 32 million for Notion, and with a share based of some 586 million, this translates to an eps of 5.5 sen.

Now if you use the stock price reference of 45 sen, it would appear that Notion is selling at an awfully cheap valuation in the stock market given the current track record (the spectacular earnings growth) of what Notion has achieved since listing and more so given Notion extremely healthy earnings margin. (ps. again this is too simplistic for the assumption is that Notion earnings growth can be maintained!)


Possible events to note.

Notion has YET to comply with the 30% Bumiputera Equity Condition. Out of memory, if not mistaken, Notion had already been granted an extension and has to comply with this ruling before the end of this year. Meaning Notion has to place out 30% new shares to Bumiputera investors.

Couple of things comes to mind and the most obvious one is that given the quality of Notion's track record, why is this an issue? Surely selling 30% new shares to new investors would be easy, right? Why the difficulties? No takers? And for what reason the lack of interest? Is there something wrong with the company orr perhaps the company simply does not know how to market themselves in the equity market? How? Sorry but I do not have any answers.

Next is the most important issue is the dilution effect caused by this placement of new shares. 30% is heck a lot.

Here is why.

Using the earlier assumption of 32 million earnings eastimate, one is looking at Notion with an eps of 5.5 sen. With these new placements, Notion share base will explode to some 760 million shares. Which means Notion EPS will dilute or shrink to only 4.2 sen.

Taking this issue into perspective, say if one is a prospective investor now, should one buy at 45 sen?

Without the dilution of placement shares, Notion is trading at 8.1x fy 2007e earnings multple.

With the dilution of the new shares, Notion would be trading at 10.7x earnings multiple.

How?

Is this issue acceptable or not?

Hope these second opinions help.