Showing posts with label IOI. Show all posts

Saturday, November 12, 2011

Dutaland's Reason

And Dutaland finally gives its reason why it rescinded the S&P with IOI.

  • Dutaland: deal rescinded to avoid prolonged legal tussle
    Written by theedgemalaysia.com
    Friday, 11 November 2011 20:04

    KUALA LUMPUR (Nov 11): DUTALAND BHD [] and IOI CORPORATION BHD [], which mutually rescinded the sale and purchase agreement over the disputed RM830 million oil palm PLANTATION [] deal, had done so with a view not to prolong the legal dispute arising from the termination of the deal.
    In a reply to a query from Bursa Malaysia Securities Bhd on Friday, Nov 11, Dutaland said the Deed of Rescission entered by the parties on Nov 9 would avoid protracted litigation, the outcome of which can be uncertain and this may have adverse implications on the company.

    “Moreover a prolonged litigation would hinder any potential sales of the PROPERTIES [] in future,”
    it said.

    Dutaland said that by entering into the Deed of Rescission, Sri Mayvin had retracted all its allegations and assertions made against Pertama Land.

    It said Pertama Land had consistently maintained that Pertama Land has complied with and is not in breach of the SPA as alleged or at all by Sri Mayvin.

    “In the absence of the sale proceeds from the Proposed Disposal, the Group may obtain bank borrowings and/or internally generated funds to fund/support the items stated in the intended utilisation of sale proceeds (i.e. purchase of Irredeemable Convertible Bonds, settlement of debts, funding of Kenny Heights project, etc),” said Dutaland.

    To recap, IOI Corp and Dutaland on Nov 9 said they had agreed to mutually rescind the sale and purchase agreement over the disputed RM830 million oil palm plantation deal.

    IOI Corp said on Wednesday that its unit Sri Mayvin Plantation Sdn Bhd and Dutaland’s Pertama Land & Development Sdn Bhd had entered into a deed of rescission in a move to resolve all issues and disputes relating to the SPA that involved 11,977.91 ha (29,597.42 acres).

    “With immediate effect whereupon the parties are released from all obligations and liabilities in connection with the SPA and neither party shall have any further claim against the other in respect thereto,” it said.

    IOI Corp said following from the execution of the deed of rescission, OSK Trustees Bhd, being the stakeholder jointly appointed by the parties, will proceed to refund the deposit earlier paid by Sri Mayvin pursuant to the terms of the SPA together with all interest accrued thereon to Sri Mayvin.

    On Oct 25, IOI Corp terminated its proposed acquisition of the land from Dutaland, citing the cancellation was “due to non-compliance of certain terms and conditions”.

    However, Dutaland had then said it did not accept the reasons for termination of the sales and purchase agreement and directed the stakeholder, OSK Trustees Bhd not to remit the deposit of RM83 million, which was the 10% deposit paid.

    In a separate statement on Nov 9, Dutaland said that with the rescission, Sri Mayvin has retracted all its allegations and assertions made against Pertama Land as contained in Sri Mayvin’s letters dated Oct 4, 20 and the 21.

    "Pursuant to the deed, Sri Mayvin has further confirmed that it has not lodged and will not lodge any private caveat(s) or any encumbrances(s) over the properties," it said.

    Dutaland also said its board having sought legal advice and after taking into consideration all relevant aspects of the termination of the SPA, was of the view that protracted litigation would hinder any future sales of the properties.

    "Furthermore, the outcome of litigation can be uncertain and this may have adverse implications on the group. In the meantime, the group shall continue to manage the properties to generate positive returns," it added.
Source: http://www.theedgemalaysia.com/business-news/196041-dutaland-deal-rescinded-to-avoid-prolonged-legal-tussle-.html

Thursday, November 10, 2011

And Dutaland and IOI Both Rescind Their 830 Million Ringgit Deal

Posted last month: Yet Another Multi Million Screw Up From IOI Corp? and And IOI Corp Gave Its 83 Million Reasoning Why It's Cancelling The Deal With Dutaland

On the Edge: IOI Corp, Dutaland rescind RM830m oil palm estate deal

  • IOI Corp, Dutaland rescind RM830m oil palm estate deal
    Written by Joseph Chin of theedgemalaysia.com
    Wednesday, 09 November 2011 19:34

    KUALA LUMPUR (Nov 9): IOI Corp Bhd and DUTALAND BHD [] have agreed to mutually rescind the sale and purchase agreement over the disputed RM830 million oil palm PLANTATION [] deal.

    IOI Corp said on Wednesday that its unit Sri Mayvin Plantation Sdn Bhd and Dutaland’s Pertama Land & Development Sdn Bhd had entered into a deed of rescission in a move to resolve all issues and disputes relating to the SPA that involved 11,977.91 ha (29,597.42 acres).

    “With immediate effect whereupon the parties are released from all obligations and liabilities in connection with the SPA and neither party shall have any further claim against the other in respect thereto,” it said.

    IOI Corp said following from the execution of the deed of rescission, OSK Trustees Bhd, being the stakeholder jointly appointed by the parties, will proceed to refund the deposit earlier paid by Sri Mayvin pursuant to the terms of the SPA together with all interest accrued thereon to Sri Mayvin.

    To recap, on Oct 25, IOI Corp terminated its proposed acquisition of the land from Dutaland, citing the cancellation was “due to non-compliance of certain terms and conditions”.

    However, in a separate statement, Dutaland said it did not accept the reasons for termination of the sales and purchase agreement and directed the stakeholder, OSK Trustees Bhd not to remit the deposit of RM83 million, which was the 10% deposit paid.
Huh?

That's it?

WTH!

Comeon... this is a 830 million ringgit transaction. Surely, both companies have a duty to show some respect to the investing public by explaining why the deal was rescinded. Mind you, when the deal was first announced, Dutaland shares soared. The investing public chased the stock because they speculated that there could be a potential cash windfall arising from this sales and purchase agreement. And Dutaland minority shareholders would like to know why the company is NOT fighting for the 83 million deposit paid.

Here's Dutaland announcement on Bursa.

  • We refer to the announcements made by the Company dated 28 July 2011, 26 September 2011, 11 October 2011, 25 October 2011 and 27 October 2011, in relation to the Proposed Disposal. (Unless otherwise defined, all terms used in this announcement shall have the same meaning ascribed to them in the aforementioned announcements)

    The Board of Directors of the Company (“Board”) wishes to inform that the Company’s wholly-owned sub-subsidiary, Pertama Land as Vendor and Sri Mayvin as Purchaser have, on 9 November 2011, entered into a Deed of Rescission (“Deed”) to rescind the SPA and to record the arrangements consequential to the rescission (“Rescission”). Pertama Land had vide its letter dated 25 October 2011 disputed Sri Mayvin’s termination of the SPA on 25 October 2011. The primary objective of the Deed is to resolve all issues and disputes relating to the termination of the SPA by Sri Mayvin.

    The salient terms of the Rescission are as follows: -

    1. With the execution of the Deed, the SPA has been rescinded whereby both Pertama Land and Sri Mayvin have been released from all obligations and liabilities in connection with the SPA and neither party shall have any claim against the other in respect thereof.

    2. With the Rescission, Sri Mayvin has retracted all its allegations and assertions made against Pertama Land as contained in Sri Mayvin’s letters dated 4 October 2011, 20 October 2011 and 21 October 2011.

    3. Pursuant to the Deed, Sri Mayvin has further confirmed that it has not lodged and will not lodge any private caveat(s) or any encumbrances(s) over the Properties.

    4. The Stakeholder shall, simultaneous with the execution of the Deed, refund the Deposit of 10% of the Sale Consideration amounting to RM83 million together with all interest accrued thereon to Sri Mayvin.

    The Board having sought legal advice and after taking into consideration all relevant aspects of the termination of the SPA, is of the view that protracted litigation would hinder any future sales of the Properties. Furthermore, the outcome of litigation can be uncertain and this may have adverse implications on the Group.

    In the meantime, the Group shall continue to manage the Properties to generate positive returns.

    After considering the above, the Board is of the view that the Rescission is in the best interest of the Company.

    The Rescission is not expected to have a material effect on the earnings, net assets and gearing of the Company and the Group for the financial year ending 30 June 2012 as well as the issued and paid up share capital of the Company and the shareholdings of the Company’s substantial shareholders.
What's the main reason to rescind?

Why the lack of transparency?

This is from IOI.
  • Reference is made to the Company’s announcements dated 25 October 2011 and 27 October 2011 relating to the termination of sale and purchase agreement ("SPA") entered into between Sri Mayvin Plantation Sdn Bhd (“Sri Mayvin”) and Pertama Land & Development Sdn Bhd (“Pertama Land”) for the Proposed Acquisition.

    To resolve all issues and disputes relating to the termination of the SPA, both Pertama Land and Sri Mayvin have on 9 November 2011 entered into a Deed of Rescission to mutually rescind the SPA with immediate effect whereupon the parties are released from all obligations and liabilities in connection with the SPA and neither party shall have any further claim against the other in respect thereto.

    Following from the execution of the Deed of Rescission, OSK Trustees Berhad, being the stakeholder jointly appointed by the parties, will proceed to refund the deposit earlier paid by Sri Mayvin pursuant to the terms of the SPA together with all interest accrued thereon to Sri Mayvin.

    This is announcement is dated 9 November 2011.
Just like that?

Case closed?

Here's Dutaland chart...


See how Dutaland, with the announcement of this 830 million transaction, soared from 50 sen to a high of 68 sen?

Yeah, see how Dutaland crash and burned once IOI said it was pulling out from this deal?

How?

Is this acceptable?

Look at the bigger picture. One of the bigger Malaysia corporate signed a S&P to make a 830 million land purchase. Deposit is even paid but yet..... such a deal can have be 'GOSTAN-ED' ..........

If this is going to be the normal practice amongst corporate Malaysia, can you wonder the future of investment in Malaysia stocks? How's Malaysia going to attract foreign investors when our corporations behave so unprofessional? One buys and signs the agreement but the next minute, the agreement is cancelled.

Yeah and what good is signing an S&P?

Could investors trust the signing of any S&P in the future when IOI and Dutaland have shown how easily the S&P could be rescinded?

WTH!

Ok, assuming IOI reasoning to withdraw from the deal is valid. However, the main question is why didn't IOI make a thorough inspection before they sign the S&P? Why sign and pay deposit then only say they want to withdraw? Very unprofessional isn't it? And they put their 83 million deposit at risk.

Friday, October 28, 2011

And IOI Corp Gave Its 83 Million Reasoning Why It's Cancelling The Deal With Dutaland

Last night, IOI Corp explained in detail on why they are pulling out from the deal to buy the plantation land from Dutaland.

I find it very unacceptable how IOI is handing this whole saga.

Their first announcement made on 25 Oct 2011:

  • Reference is made to the Company’s announcement on 28 July 2011 pertaining to the sale and purchase agreement ("SPA") entered into between Sri Mayvin Plantation Sdn Bhd ("Sri Mayvin"), an indirect wholly-owned subsidiary of the Company with Pertama Land & Development Sdn Bhd (“Pertama Land”), a wholly-owned subsidiary of Duta Plantations Sdn Bhd, which in turn is a wholly-owned subsidiary of Dutaland Berhad ("DutaLand") to acquire 11,977.91 hectares (or equivalent to 29,597.42 acres) of oil palm plantation land ("Plantation Land"), for a total cash consideration of RM830 million ("Proposed Acquisition").

    The Company wishes to announce that Sri Mayvin had on 25 October 2011 issued a notice to Pertama Land to terminate the SPA due to non-compliance of certain terms and conditions which had been communicated to Pertama Land. Under the provision of the SPA the rights and obligations of the parties shall lapse and be of no further effect from the date of termination notice, save and except that OSK Trustees Berhad, being the stakeholder shall within a period of seven (7) days from the notice of termination refund to Sri Mayvin the deposit of RM83 million which is equivalent to 10% of the purchase consideration and interest accrued thereon.
That was it.

They terminated the S&P to purchase the land because "non-compliance of certain terms and conditions".

This is a 830 million ringgit transaction that they are terminating and at stake is a 83 million ringgit deposit paid.

The lack of detail was utterly disappointing. Surely, as one of Malaysian leading corporates, IOI Corp, could have shown the decency and respect to the investing public by explaining in detail what exactly was happening.

Now given what happened three years when IOI Corp forfeited 73 million ringgit when they pulled out of a deal to buy Menara Citibank, IOI Corp should have realised that it's absolutely crucial that they explain in full detail to the market what exactly was happening.

But no, they decided not to.

Was it an act of arrogance? I dunno...

Last night, 27 Oct 2011, IOI made another announcement. I was shocked at IOI Corp's inefficiency. Why can't they just announce it on the 25th? Why the need to make another separate announcement? Gosh! I just find it so unacceptable. Why the utter lacking in professionalism?

Anyway, this is what they said.
  • We refer to the Company’s announcement dated 25 October 2011 pertaining to the termination of sale and purchase agreement ("SPA") entered into between Sri Mayvin Plantation Sdn Bhd (“Sri Mayvin”) and Pertama Land & Development Sdn Bhd (“Pertama Land”) for the Proposed Acquisition.

    The Company wishes to announce that Sri Mayvin has communicated incidences of non-compliance/ breach of the SPA to Pertama Land vide letters dated 4 October 2011, 20 October 2011 and 21 October 2011. In summary, the incidences of non-compliance/ breach by Pertama Land of the terms and conditions of the SPA may be, among others, categorised as follows:

    1. Adherence to the obligation for the continued upkeeping/ maintenance of the properties in accordance with accepted agronomic practices;
    2. Discrepancies in the particulars relating to the properties; and
    3. Integrity of the title of Pertama Land in relation to one of the properties.
Finanlly.... a proper reasoning is given to the investing public.
How?

Are these three reasoning valid for IOI to pull out for the deal?

And at a stake, a 83 million ringgit deposit. Huge money at stake here!

How?

On Business Times today, IOI Corp was featured again.

  • IOI maintains stand on deal turned sour

    By June Ramlee Published: 2011/10/28

    KUALA LUMPUR: IOI Corp Bhd, which stands to lose an RM83 million deposit to Dutaland Bhd from a deal turned sour, yesterday insisted that the latter had breached their sale and purchase agreement (SPA).


    Dutaland, however, maintained that it had not acted in breach of the SPA relating to a piece of plantation land.

    IOI previously announced that it had terminated the SPA to buy 11,977.91ha of oil palm plantation land in Sabah from Dutaland for RM830 million.

    IOI then said the cancellation was "due to non-compliance of certain terms and conditions".

    On July 28 this year, IOI's unit Sri Mayvin Plantation Sdn Bhd had signed the deal with Dutaland's unit Pertama Land and Development Sdn Bhd.

    Yesterday in a filing to Bursa Malaysia, IOI maintained that Dutaland, among others, had failed to continue upkeeping and maintaining the properties. It also claimed that there were discrepancies in the particulars relating to the properties, and that Sri Mayvin had communicated the alleged breaches to Pertama Land.

    Dutaland, in its latest filing to the stock exchange, said Pertama Land had consistently maintained that it was not in breach of the SPA as alleged.

    There had also "been non-compliance on the part of Pertama Land under the SPA as alleged or at all by Sri Mayvin", it added.

    Meanwhile, analysts said there will be a minimal impact on IOI's overall earnings if it loses its RM83 million deposit from the deal inked with Dutaland Bhd a few months ago. This is because IOI is a cash-rich company with profits of close to RM2 billion to RM3 billion a year.

    Losing the RM83 million deposit on that deal would not make a big difference as the potential loss will only lower its earnings by three to four per cent, said several analysts when contacted by the Business Times yesterday.
    "It's too early to say (if the deposit will not be returned) but if they can prove that it is non-compliance, then they should be able to get their money back.

    "But if they lose their deposit, then there would be minimal impact on the company as it makes RM2 billion in profits in a year, so it won't hurt much," said one analyst.

    It will not be the first time IOI will lose its deposit. In 2008, the company had forfeited its deposit of RM73.4 million after it walked away from buying Menara Citibank.

    Analysts, however, said the Citibank and the Dutaland deals cannot be equated, given that the company had decided to walk away from the former deal.
    Dutaland earlier said it was seeking legal advice and had notified OSK Trustees Bhd not to remit to Sri Mayvin the deposit of RM83 million being the 10 per cent deposit paid by Sri Mayvin under the SPA and any interest accrued.
 I do not agree some of the points mentioned.
  • Losing the RM83 million deposit on that deal would not make a big difference as the potential loss will only lower its earnings by three to four per cent, said several analysts when contacted by the Business Times yesterday.
  • "But if they lose their deposit, then there would be minimal impact on the company as it makes RM2 billion in profits in a year, so it won't hurt much,"
Errr.... I am simply lost.

How could these analysts take the 83 million and compare it against what IOI Corp is making as whole? Yeah, IOI Corp could be making rm 2 billion a year but goodness me, 83 million ringgit is 83 million ringgit is 83 million ringgit. This is money way beyond most of us Malaysians.

Well, what if everyone starts having such an attitude and mindset such as  'hey we make 2 billion a year, it's ok to blow away 83 million... it's just a bloody spit in the ocean....' ?

How?

Is that acceptable behavior?

No, that's not for me. Not in a million years.

But then ... looking at recent losses from IOI Corp - the 300 million forex losses, the 73 million forfeited deposit and now this.... you begin to wonder.....

And last but not least...
  • Analysts, however, said the Citibank and the Dutaland deals cannot be equated, given that the company had decided to walk away from the former deal.
Huh?

How could it not be equated?

Tell me.... sigh.

In the Citibank debacle, IOI Corp pulled out 3 months after signing and the S&P. For this Dutaland purchase, IOI is again pulling out 3 months after signing the S&P.... how are they not the same?

Two of the reasons given last night by IOI...
  • 2. Discrepancies in the particulars relating to the properties; and

    3. Integrity of the title of Pertama Land in relation to one of the properties.
The discrepancies and the integrity of the title... shouldn't this be thoroughly examined by IOI Corp themselves before they sign the S&P?

Hey, it's a 830 million deal... surely you want to examine everything in full detail... before you sign, yes? Why sign and paid the deposit only to now claim discrepancies and integrity? Why risk losing the deposit paid? Is 83 million ringgit small change?

Now? It looks like the fate of the 83 million ringgit lies in the hands of the court.

On Star Biz: IOI, Dutaland in war of words over termination of RM830mil deal

Wednesday, October 26, 2011

Yet Another Multi Million Screw Up From IOI Corp?

I was shocked when I read the following set of news last night:

IOI Corp had signed a deal on 28 July 2011 to purchase 11,977.91 ha (29,597.42 acres) of plantation land from Dutaland. A 83 million deposit had already been paid.

Last night, just 3 months after signing the deal, IOI Corp said it's cancelling this deal.

And of course, Dutaland quickly responds by saying it's taking legal advice since it's not accepting IOI's reason for termination.

And as you can guess, Dutaland has asked that the deposit of 83 million not be remitted back to IOI Corp.

And this looks like yet another woeful corporate exercise from IOI Corp.

Just what on earth are they doing?

This is a 830 million transaction. You just don't sign any 830 million corporate deal without making thorough due diligence before agreeing to purchase. And IOI explanation on why it's cancelling this deal is simply a " non-compliance of certain terms and conditions".

This is simply pathetic and it reminds me of the recent Citibank debacle that happened back in Nov 2008.

Here's an article on Star Biz back then.

  • Saturday November 29, 2008
    IOI Corp should better explain why it’s losing its RM73mil deposit
    By P. Gunasegaram

    REALLY, listed companies should be a lot more careful before they pay a deposit for their proposed acquisitions. If they can’t complete their deals for any reason, they can lose hefty sums of money and raise needless suspicion over board integrity.
    Boards of listed companies and CEOs should realise that they have a statutory duty not only to their major shareholders but also to each and every shareholder – and there are many minority shareholders to consider.

    The least that listed companies should do when they abort their deals is to offer a full and fair explanation of why it was aborted, what were the events that had changed and why these things had not been anticipated in the first place.
    Take the deal called off inexplicably by IOI Corp after having signed on the dotted line less than three months ago and losing over RM73mil in deposits paid in the process.

    It had announced on Aug 28 the effective acquisition of Menara Citibank in Kuala Lumpur for RM586.7mil through the purchase of Inverfin Sdn Bhd which owned the building. Inverfin is owned in turn by Citigroup unit Citi Holding (50%), Singapore’s CapitaLand (30%) and Amsteel Corp (20%).

    On Thursday, Nov 27, IOI Corp, just a day short of three months of the earlier announcement, told Bursa Malaysia that it has decided not to proceed with the acquisition.

    The reason in IOI Corp’s own words: “However, due to the recent sudden adverse developments in the global economic environment which have spread to this region and impacted negatively on business sentiments, the Company has, after due and careful deliberations, decided that it would be in the overall best interests of the Company and its shareholders not to proceed with the Proposed Acquisition.”
    It further announced that the vendors were forfeiting the deposits paid of RM73.4mil together with interest and added that it was “seeking legal advice as to the propriety and quantum of the aforesaid forfeiture”.

    It is instructive to note what IOI Corp said in its original acquisition announcement: “The Proposed Acquisition will provide IOI with an immediate substantial rental income stream. With its choice location at the heart of Kuala Lumpur and well served by the surrounding infrastructure and amenities, Menara Citibank is presently enjoying close to 100% occupancy rate with quality tenants consisting of multinational companies and reputable companies in their respective industries.

    “In addition, the 50-storey Menara Citibank is well-maintained and well-equipped with high quality mechanical and electrical equipment and good security system. Its distinctive design and quality also distinguish itself from the competing office buildings in the vicinity.

    “On the whole, the Proposed Acquisition is a strategic move which augurs well for the IOI Group as it accords the Group with the golden opportunity to own one of the few available high-rise Grade A office buildings in Kuala Lumpur with first class location and prestigious address.”

    So, why is that changed in three months? Was there an exodus of tenants from Menara Citibank? Did the rental income drop? Was there a collapse in office space prices? Why is the acquisition not strategic anymore?

    Why could not IOI Corp have foreseen these problems earlier? After all, the subprime crisis was already upon us. Why did it pay the deposit which it now has most likely lost if it had felt there could be problems?


    IOI Corp’s explanation is poor at best and we really don’t know what it is at worst. Investors certainly expect a lot more from this company, once the darling of the stock market. And so should regulators. Minority shareholders certainly have a right to be seriously upset.

    Coming so soon after its recent debacle where it reported foreign exchange losses of over RM312mil for the quarter to end-September, the latest episode will put another dent in its reputation, largely unsullied until the forex episode.
See the similarities?

IOI Corp back in 2008, had also terminated a deal 3 months after signing the deal!!!!

And IOI lost its 73 million deposit back then. Me? I won't be surprised one bit if IOI loses 83 million ringgit this time for cancelling its deal with Dutaland.

It's simply embarrassing and if I am a minority shareholder in IOI Corp, I would be deeply annoyed to see what's happening. IOI Corp is supposedly one of our country's biggest corporation. In 2008, IOI lost 73 million by rescinding a deal to buy Citibank. 3 years later, IOI could now lose 83 million by cancelling this deal to buy land from Dutaland. What the hell? Does IOI have so many million ringgit to give away???

Would you blame any minority shareholder for asking 'Is IOI Corp the biggest water fish in corporate Malaysia?'

Good grief!

ps: Looks like Dutaland could get 83 million ringgit free!
ps: I got some barn yard. Does IOI want to agree to buy and then cancel to buy from me? :P

Saturday, May 15, 2010

WOW! Did IOI Net Profit Increased 15-Fold?

Seriously.

Yeah, I did said seriously.

Does our financial newspapers thinks we are kiddies? Or what?

Yeah, or what.


Take a look at this childish reporting: IOI's Q3 net profit increases almost 15-fold


And the main reason?

  • In a statement yesterday, the diversified group said the higher profit is also attributable to unrealised translation gain on US dollar-denominated borrowings of RM231.5 million compared with a loss of RM232.4 million in the third quarter of 2009.

A forex gain of 232.4 million!!!

That's a lot of forex gain, yes?

And if you minus this out, from IOI's net earnings, how impressive is IOI's earnings????

The first thing that struck my mind was last year, I remember, IOI suffered huge losses. And everyone highlighted the issue of the forex losses, implying that the earnings is better if one excludes the losses. So how come... it doesn't work the other way around? Why shouldn't one exclude these forex gains from IOI earnings?

Well.. if one doesn't... then isn't it so clear...what the market wants to tell the investing public?

How?

See past posting (exactly a year ago) Quick Look At IOI Quarterly Earnings and IOI Earnings Results And Flashback On What Has IOI Done The Past One Year

Friday, July 31, 2009

So Why Is IOI Corp Raising RM 1.2 Billion?

Posted this morning: IOI Corp: If Investors Are Not Happy

Saw some extra comments made on the Financial Edge Daily's version: IOI’s Lee: Dividend payouts not in jeopardy

  • On the use of the RM1.2 billion proceeds, Lee said, “The funds will be kept for investment opportunities.”

    On whether any investment targets had been identified, he said: “Not yet. When we have, we’ll let you know.”

Huh?

Raise fund so that they can have extra cash?????

Holy cow!

What if they do another Menara Citibank fiasco and lose rm 73 million???

Not possible????

Is such corporate practise even acceptable?

Can they do a corporate fund raiser without knowing their investment targets???

Sigh!

Why can't they decide their investment target and let their minority shareholders know first????

Yeah, and if IOI investors are not happy.....

I wonder what award they got last night!

Sigh!

Where is MSWG?

Sigh!

You know, when you were small, not too long ago, and you wanted some extra pocket money for that new ______ , you would ask your parent yes?

And would our parent just hand us the moolah, without asking why?

And if our parents asked us why... can we turn around and tell our parents "Well Dad, if you are not happy........ "

Can you ever imagine this happening?

IOI Corp: If Investors Are Not Happy

Posted a few days ago: Comments On IOI's Right Issue: Version II

Now from an investor point of view, we all knew that IOI said it made huge profits the last year. More precisely from quarterly earnings ended 31/12/2007 to quarterly earnings ended recently on 31/3/2009, IOI said it made some 2.276 Billion in net earnings.

And yet the company said it wants to raise some 1.2 billion in a new rights issue.

Surely, it's not logical and neither is it any comforting for its shareholders.

Why the rights issue? What happened to all the big money made?

And then there was the Menara Citibank fiasco.
Article entitled: IOI Corp wins bid for Menara Citibank? A rm586 million to buy an office building. And it ended up in a horror story. Yup, it lost some rm73 million when IOI abruptly decided NOT to proceed with the deal. Yes, the press was not impressed at all. IOI Corp should better explain why it’s losing its RM73mil deposit.

The following comments were raised in that article.

  • So, why is that changed in three months? Was there an exodus of tenants from Menara Citibank? Did the rental income drop? Was there a collapse in office space prices? Why is the acquisition not strategic anymore?

    Why could not IOI Corp have foreseen these problems earlier? After all, the subprime crisis was already upon us. Why did it pay the deposit which it now has most likely lost if it had felt there could be problems?

    IOI Corp’s explanation is poor at best and we really don’t know what it is at worst. Investors certainly expect a lot more from this company, once the darling of the stock market. And so should regulators. Minority shareholders certainly have a right to be seriously upset.

    Coming so soon after its recent debacle where it reported foreign exchange losses of over RM312mil for the quarter to end-September, the latest episode will put another dent in its reputation, largely unsullied until the forex episode.
And needless to say there wasn't any clear explanation till this very day.

And on Business Times
IOI Corp chief says rights plan won't affect dividend payout
  • IOI Corp Bhd does not expect its proposed rights issue to affect its ability to pay dividends in the short term and says its major shareholder is ready to pick up shares that are not taken up.

    "Not really. Well, if they (investors) are not happy, then we (Progressive Holdings Sdn Bhd) can take it up," IOI Corp (1961) executive chairman Tan Sri Lee Shin Cheng said yesterday.

Did not like what I read at all.

Sorry... just me.

This rights issue is not about it affecting its ability to pay dividends.

It's all about IOI Corp being transparent on why such a huge rights issue coming on the back of a period where IOI made a lot, lot of money. Where did the money go? Why does IOI need the rights issue?

And to say.. if investors are not happy, they will take up the rights issue ... is simply lacking in taste.

How can he say like this? I mean this is rather arrogant, yes?

So if investors are not happy, should they sell their shares?

Monday, July 27, 2009

More On IOI Corp

Posted yesterday. Comments On IOI's Right Issue: Version II

In that posting I highlighted one simple issue.

From Feb 2008 quarterly earnings (for period ended 31/12/2007) to Feb 2009 quarterly earnings (31/12/2008), IOI announced it made some 2.2 Billion in earnings. And despite making so much money, rm2.276 Billion in this period, IOI's net debt actually increased by 1.918 billion.

My inquisitive mind, asked where did the money go.

Got the following comment.

  • jitseng said...
    The money to stock buys back.The used about 1.6b

Now if I search Bursa website, I would find this announcement dated 22/6/2009. Notice of Shares Buy Back - Immediate Announcement

In it, it states that the cumulative shares bought back was 291,244,500.

Now I give it a benefit of a doubt, and make a simple goofy assumption that all the shares bought back was during this period and I would also assume what jitseng is saying is correct.

So assuming IOI spend some 1.6 billion in share buybacks.

Now I am more dumbfounded because I would look at it in an even more simplistic manner.

This company made some 2.2 Billion in profits and then it spends some 1.6 billion in share buybacks.

Errr..... wazzap doc?

Does this sound like a good business economics at all?

Does such a corporate exercise makes business sense at all?

Sunday, July 26, 2009

Comments On IOI's Right Issue: Version II

Posted Comments On IOI's Rights Issue yesterday.

Got the following comments...

  • 棕油网 said...
    moola, please refer to three items into one,

    there are short term fund 1,905,639
    short term deposit 268,556
    cash and bank 341,407

    just look back to Humeind, their piggy cash slump after exchange with Evergreen Fibreboard, but later the director gave a clue to the cash position.

Yeah, I goofed up. :p2

I missed out the short term fund and my attempt in the corrections looks so freakingly messy.

Hence this posting.

Let me start over again.

Feb 2008, Quarterly rpt on consolidated results for the financial period ended 31/12/2007

Total cash should be 427.109 + 531.574 + 692.897 = 1651.580 million (or 1.65 Billion)

Short term + long term borrowings = 205.697 + 3363.589 = 3569.186 million (3.569 Billion!)

Which means from a cash/debt position, IOI's is in a net debt position of 3.569 - 1.651 = 1.918 Billion.

Now let's look at the money earned during this period

1. Quarterly rpt on consolidated results for the financial period ended 31/12/2007
Net earnings: _______________ 581.191 million

2. Quarterly rpt on consolidated results for the financial period ended 31/3/2008
Net earnings: _______________ 601.639 million

3. Quarterly rpt on consolidated results for the financial period ended 30/6/2008
Net earnings: _______________ 597.284 million

4. Quarterly rpt on consolidated results for the financial period ended 30/9/2008
Net earnings: _______________ 290.500 million

5. Quarterly rpt on consolidated results for the financial period ended 31/12/2008
Net earnings: _______________ 168.586 million

6. Quarterly rpt on consolidated results for the financial period ended 31/3/2009
Net earnings: _______________ 37.362 million

Adding it all up (did you note the drastic decline in earnings?), I got 2276.562 million (or 2.276 Billion) (hope I did not goofed up again. )

So during this period, IOI made 2.276 Billion.

However, as per IOI's last reported quarterly earnings was on 15th May 2009, Quarterly rpt on consolidated results for the financial period ended 31/3/2009, it showed that IOI cash balances were 268.556 + 341.407 + 1905.639 = 2515.602 million (or 2.515 Billion)

Short term + long term borrowings = 37.771 + 5682.610 = 5721.381 million (5.721 Billion!)

Which meant, from a cash/debt position, IOI's net debt = 5721.381 - 2515.602 = 3205.779 million (or 3.205 Billion!).

Compare to 31/12,2007, IOI was in a net debt of 1.918 billion.

Which means despite earning 2.276 Billion in this period, IOI's net debt increased by 1.918 billion.

Where did the money go?

Yes, I am aware that during a major acquisition or in IOI's case, the privatisation of IOI Properties, cash position does weaken.

Would this be the case?

Now IOI Properties privatisation was completed in April 2009. Now I would use Feb 2009 earnings as a reference point (would I be goofing up here?). Quarterly rpt on consolidated results for the financial period ended 31/12/2008

Total cash = 1005.374 + 397.354 + 445.530 = 1848.258 million or 1.848 Billion.

Short term + Long term borrowings = 73.453 + 3816.098 = 3889.551 million or 3.889 Billion.

Net debt = 3.889 - 1.848 = 2.041 billion.

Ahh...

Which meant that IOI's cash/debt position did not deteriorate as suggested.

However, if we minus the May's earnings, IOI still made a lot of money.

How much? Try 2276.562 - 37.362 = 2.239 Billion.

Yet again... despite making sooooooooooo much money, IOI's balance sheet did NOT reflect the richness gained from the CPO bull run.

Another issue, as seen in May 2009 earnings, IOI was in a net debt of 3205.779 million. In Feb 2009, it was 2.041 billion.

Which meant IOI net debt increased by some 1.164 Billion.

And all this from IOI's Privatisation. (Would I be a goofer to say this?)

Now isn't it ironic that IOI's proposed rights issue amounts to some 1.2 billion?

Would I be goofy to suggest that this rights issue is paying for the privatisation of IOI Property?

How?

Would you be happy?

Saturday, July 25, 2009

Comments On IOI's Rights Issue

On Star Business. in the article, Report: New IOI debt sign of ‘more subdued outlook’, several research houses gave their opinions.

I was not impressed with the last few passages.


  • ........... A local brokerage said while the rights issue might not be ideal, it was probably the easiest and fastest way to raise the required funds in the current tight capital market.

    IOI was likely to use the proceeds to refinance some of its convertible bond issues, of which one is due in 2011 and another in 2013, it said.

    A bank-backed research house, meanwhile, believed IOI was building its war chest for major acquisitions given that it was in a healthy financial position.

    IOI’s free cashflow for FY10 is estimated at about RM1.5bil versus capex needs of RM500mil. As at May 8, unutilised proceeds from the third exchangeable bonds totalled RM732mil.

    Regional plantation companies also seemed to be on a fund-raising spree, the research house said, noting that Wilmar International Ltd was listing its China operations in Hong Kong while Indofood Agri-Resources was mulling a 1 trillion rupiah bond issue.

Not too impressed with this un-named bank-backed research house.

Which research house is this?

Why give such comments and chose to be an unknown?

How accurate is the healthy financial position mentioned by this unknown bank-backed research house?

Me?

I would question the healthy financial position.

Let me prove what I am saying.

Earlier this year, I wrote the following posting. IOI Earnings Results And Flashback On What Has IOI Done The Past One Year

Let me re-cycle some stuff.

Here's the objectivity of this simple exercise. Since 2008, the CPO had the mother of all bull runs. All planters made insane profit. Money were like falling from the sky. Yes?

So a comparison from a quarterly reports then and compare to present day, and see how healthy is IOI's financial position.

Would this not be logical?

Anyway, from that posting... , I want to use the quarterly earnings reported on Feb 2008.

:: ..... I start with looking at what was on IOI's books back exactly a year ago, Feb 2008, Quarterly rpt on consolidated results for the financial period ended 31/12/2007

Short term funds+cash and bank balances = 427.109 + 531.574 = 958.683 million.

*** Errata !!! ***.

Missed out the short term funds. Looks like my eyes are short! :p2

Total cash should be 958.683 + 692.897 = 1651.560 million.

Short term + long term borrowings = 205.697 + 3363.589 = 3569.186 million (3.569 Billion!) ( you can verify this on this screenshot here )

Net debt position = 3569.186 - 1651.560 = 1917.626 million

IOI's last reported quarterly earnings was on 15th May 2009. Quarterly rpt on consolidated results for the financial period ended 31/3/2009

Short term funds+cash and bank balances = 268.556 + 341.407 = 609.963 million.

*** Erata !!! ***

Total cash should be 609.963 + 1905.639 = 2515.602 million

Short term + long term borrowings = 37.771 + 5682.610 = 5721.381 million (5.721 Billion!)


Net debt = 5721.381 - 2515.602 = 3205.779 million

How?

*** Errata ***

Cash balances of 958.683 million had diminished to 609.963 million!
Loans ballooned from 3.569 Billion to 5.721 Billion!!

IOI as at 31/12/2007 was in a net debt of 1917.626 million. IOI latest earnings as at 31/3/2009 saw IOI having net debt of 3205.779 million.

I do not know but would this be the definition of a healthy financial position when cash had diminished and loans ballooned? when during a period when IOI saw CPO crude prices hit record highs, their net cash position actually deteriorated?

Now consider this also.

Anyone want to count the 'money' made by IOI during this period?

1. Quarterly rpt on consolidated results for the financial period ended 31/12/2007
Net earnings: _______________

2. Quarterly rpt on consolidated results for the financial period ended 31/3/2008
Net earnings: _______________

3. Quarterly rpt on consolidated results for the financial period ended 30/6/2008
Net earnings: _______________

4. Quarterly rpt on consolidated results for the financial period ended 30/9/2008
Net earnings: _______________

5. Quarterly rpt on consolidated results for the financial period ended 31/12/2008
Net earnings: _______________

6. Quarterly rpt on consolidated results for the financial period ended 31/3/2009
Net earnings: _______________

So where all the money go when IOI was making big money?

Dividends? Maybe IOI paid out a lot of dividends?

Second interim dividend
Interim Dividend
Interim Dividend
Interim Dividend

And then there was the privatisation of their listed subsidiary, IOI Properties. ( see Big Ouch For IOI Properties! )

How?

If you are an IOI Corp shareholder, how would you evaluate your investment?

Don't you find it incredible that after the biggest ever bull run in the CPO prices that IOI Corp want to raise some 1.22 billion in a rights issue?

How my dearest?

***************************
Many thanks to 棕油网 for pointing out that I had made some error. :D

Saturday, May 16, 2009

Quick Look At IOI Quarterly Earnings

Posted Saturday, February 21, 2009 IOI Earnings Results And Flashback On What Has IOI Done The Past One Year

This morning I caught this news.
IOI third quarter net profit down 94pc to RM37.3m

  • The profit plunge for Malaysia’s No 2 palm oil producer by market value is attributed to translation losses on its foreign debt and lower crude palm oil prices

    IOI Corp Bhd's net profit in the third quarter ended March dived 94 per cent to RM37.3 million from RM601.6 million in the comparable quarter a year ago, due to foreign exchange losses on its foreign denominated loans and lower crude palm oil (CPO) prices.

    In a statement yesterday, Malaysia's most valuable planter said revenue dipped to RM3 billion from RM3.5 billion, dragged by an unrealised translation loss on its US dollar denominated borrowings of RM232.4 million and weaker product prices.

    "The global economic slowdown, which is now affecting Malaysia, will no doubt make the current year a challenging one for business corporations.

    "Operating profit from the plantation segment is 46 per cent lower than the previous quarter, due mainly to lower fresh fruit bunches production and lower CPO prices realised," said IOI directors.

    The company said CPO prices averaged RM2,932 a tonne for the nine months to March compared with RM2,705 a tonne in the same period last year.

Not doing that well, eh?

My oh my, oh quickly the good times end!

I was more interested in what was stated in their quarterly earnings notes.

  • In tandem with the global economic slow down, the Group reported a 58% lower pre-tax profit of RM937.4 million for Q3 YTD FY2009 as compared to RM2,239.1 million for Q3 YTD FY2008. The lower profit is due mainly to unrealised translation losses on long term USD denominated borrowings as well as lower contribution from both the manufacturing and property segments. After excluding the unrealised translation loss on long term USD denominated borrowings of RM482.0 million (Q3 YTD FY2008 - gain of RM226.8 million), the pre-tax profit for Q3 YTD FY2009 is RM1,419.3 million or 30% lower than Q3 YTD FY2008, which is reasonable in light of the challenging economic conditions. The ringgit has been strengthening against the USD since 31 March 2009 and should this trend continues, it is likely that part of the unrealised translation loss on long term USD denominated borrowings will be written back.

    The plantation segment reported a 6% increase in operating profit, i.e. RM1,380.5 million for Q3 YTD FY2009 as compared to RM1,302.4 million for Q3 YTD FY2008. The better performance is due mainly to higher CPO prices realised from the forward sales entered into during the second half of FY2008. Average CPO prices realised for Q3 YTD FY2009 was RM2,932/MT as compared to RM2,705/MT for Q3 YTD FY2008.

    The resource-based manufacturing operating profit of RM169.1 million for Q3 YTD FY2009 is significantly lower as compared to RM457.4 million for Q3 YTD FY2008. The lower profit is attributable mainly to realised foreign exchange losses and customer defaults on high priced contracts incurred during the first half of the financial year and lower sales volume due to the unfavourable global economic conditions.

    The property segment’s operating profit of RM200.5 million for Q3 YTD FY2009 is 35% lower than Q3 YTD FY2008. The decrease is due mainly to the soft property market conditions and lower margins.

    In the opinion of the Directors, the results for the financial period under review have not been affected by any transaction or event of a material or unusual nature which may have arisen between 31 March 2009 and the date of this announcement.

The following caught my attention.

  • After excluding the unrealised translation loss on long term USD denominated borrowings of RM482.0 million (Q3 YTD FY2008 - gain of RM226.8 million), the pre-tax profit for Q3 YTD FY2009 is RM1,419.3 million or 30% lower than Q3 YTD FY2008, which is reasonable in light of the challenging economic conditions.

I chuckled.

As mentioned in the previous posting, IOI Earnings Results And Flashback On What Has IOI Done The Past One Year, back in May 2008, IOI earnings clearly was boosted by huge forex gains of over 226 million.

I am wondering. Why did they NOT include statements like 'excluding our forex gain.. our profits would have been lesser..'?

Anyway let's look at their group borrowings. Anyway from that posting, I posted this table from IOI last reported quarterly earnings.


And the table below is from IOI's earnings last night.


How the loans have increased, especially the US Denominated!


I would assume that the company is hoping and praying very hard that USD plunges!

Saturday, February 21, 2009

IOI Earnings Results And Flashback On What Has IOI Done The Past One Year

Posted last night Comments And Views On Ringgit Fall To Two Year Low

How would a low ringgit impact Malaysian companies? Who would be impacted?

IOI Corporation came up instantly.

There were issues about its forex losses before and I knew that IOI has massive borrowings denominated in USD.

So I thought it would be a good simple exercise to have a brief look at some older earnings report for IOI.

I start with looking at what was on IOI's books back exactly a year ago, Feb 2008,
Quarterly rpt on consolidated results for the financial period ended 31/12/2007


Under the long term borrowings, USD denominated loans totals 656.488 million and IOI values these borrowings at 2.170 billion. This should works out to an exchange rate of around 3.31.

3 months later, in May 2008, IOI announced the following
Quarterly rpt on consolidated results for the financial period ended 31/3/2008


USD denominated loans now totals 1.112 BILLION and IOI values these borrowings at 3.547 BILLION. My calculator shows that this works to an exchange rate of 3.19.

Now I know this is a LOT but I do agree that it's hard to criticise IOI Corporation for what it did here.

Crude palm oil was booming and IOI Corporation were making totally insane profits. And with IOI able to obtain borrowing rates at 3.19, surely there were some justifications to borrow more in USD, yes?

Think about it.

The money in USD were getting cheaper and cheaper and with the US housing crisis the smartie pants reasoning was that the USD were going to plummet into the deep blue sea.

And what's better way to ride the USD weakness by borrowing more in that currency?

Was that not a justifiable reasoning?

Maybe.

This is what the company said back in May 2008 in its earnings notes.

  • Group revenue for YTD Q3 FY2008 is 58% higher than last year’s corresponding period. All major business segments reported increase in revenue as a result of higher palm oil prices, increased volume for resource-based manufacturing, as well as higher sales of properties.

    The Group's pre-tax profit for YTD Q3 FY2008 is RM2.24 billion , an increase of 61% as compared to the RM1.39 billion reported for YTD Q3 FY2007, contributed by better performances from all major business segments.

    Plantation earnings of RM1,302.4 million for YTD Q3 FY2008 is about twice the earnings generated for YTD Q3 FY2007, boosted by significantly higher CPO prices. Average CPO prices realised for YTD Q3 FY2008 is RM2,705 per MT as compared to RM1,649 per MT for the same period last year. The resource-based manufacturing segment continued to perform well for YTD Q3 FY2008 with an increase in operating profit by 47% at RM457.4 million with the inclusion of profit from Pan Century Group as well as volume and margin growth from all three sub-segments.

    The property segment’s operating profit is about previous year’s level at RM310.6 million. Overall, the Group achieved net earnings of RM1.63 billion for YTD Q3 FY2008, a 59% increase over the RM1.03 billion recorded for YTD Q3 FY2007. The percentage increase of the Group’s net earnings level is slightly lower than the percentage increase of the Group’s pre-tax level due mainly to higher tax expense as a result of the expiry of certain tax incentives granted by the tax authority at the end of FY2007.

    In the opinion of the Directors, the results for the financial period under review have not been affected by any transaction or event of a material or unusual nature which may have arisen between 31 March 2008 and the date of this announcement.

Now I know very well that the above statement left out one important note. Quarterly earnings were boosted by gains in forex gains of 226 million (hey IOI borrowings in USD in Feb 2008 were valued at 3.31 and 3 months later the rates fell to 3.19.). Do look under segmental reporting and you can see it. ( link: Quarterly rpt on consolidated results for the financial period ended 31/3/2008 )

Three months later, Quarterly rpt on consolidated results for the financial period ended 30/6/2008.

Despite the now falling crude palm oil prices, the following was a sample news clip trumpeting IOI fiscal year success, IOI shines with RM2.23bil profit. Do note that the non-existent mention of the forex gains, one have to read the finer details in the earnings report to see it.

Huge success for IOI.

Everything it had was gold.

Rm2.23 billion in net profit. Record earnings. They borrowed more and due to the weakening USD dollar, what they borrowed is now less.

Success.

Time to venture more.

Then came August 2008. Article entitled: IOI Corp wins bid for Menara Citibank?

  • We wish to inform that IOI Corporation Berhad has succeeded in its bid for the purchase of Menara Citibank and has reached an agreement with Inverfin Sdn Bhd and its shareholders to enter into a definitive agreement in due course.

A RM586 million deal of buy an office building!

I was shocked.

But like many others, who are we to question when IOI Corp had the winning hand? Everything they touched were turning into gold literally.

Then came October. It was a hell of a month. The US housing crisis had turned into a global crisis. And worse still the street got wind of IOI plunging on forex losses! IOI share price then plunges on these forex losses newss

And the most incredible article then was Citigroup makes buy call on IOI Corp

  • Citigroup has fairly valued IOI Corp’s share price at RM7.46 on the basis that it would trade at 22.7 times of its price to earnings ratio from its current financial year forecast profits of RM2.1 billion.

That was a bold valuation in my flawed opinion. It was based on a forecast of a net profit of rm2.1 billion. I found it absurd. Crude palm oil prices were falling off the cliff. Was it right to project such a high profit forecast?

So how much was the forex losses? Forex announcement.pdf

The sum of all fears

  • IOI Corp had closed at RM3.02 on Oct 23. Over the next two trading days, it was in a downhill roll that pushed the share price to a 52-week intraday low of RM2.08. That’s a 31% plunge in a period when the KL Composite Index was never more than 10% down.

    The counter has clawed its way back to RM2.74 last Thursday and it looks like the painful streak has ended, thanks partly to the company’s explanation on its forward foreign currency contracts. Nevertheless, the episode has raised some questions. (do read the article in full)

Then came November. Everything was falling apart fast.

Quarterly rpt on consolidated results for the financial period ended 30/9/2008

Snippet from a Dow Jones news clip.

  • IOI Corp 1Q Net Profit Down 36%; Expects Weaker Fiscal 2009

    KUALA LUMPUR (Dow Jones)--IOI Corp. (1961.KU) said Friday
    first-quarter net profit fell 35.7% due to foreign exchange losses and poorer results from its property unit, and expects weaker results for the 2009 fiscal year.

    Malaysia's second-largest plantation group by acreage said in a filing to the stock exchange that net profit for the quarter to Sept. 30 fell to MYR290.5 million from MYR451.5 million a year earlier.

    The company said it had a foreign exchange loss of MYR100.6 million from its resource-based manufacturing business segment and from the partial conversion of proceeds from U.S. dollar-denominated borrowings.

I was thinking out loud fast. During the good times, it was just in May's quarterly earnings, it had forex gains of over 226 million in its book. But it kept quiet on how this forex gains did boost its earnings. Now they have a forex losses, they start using it as an excuse for their poor earnings.

And later that month, came another shocker.

IOI CORPORATION BERHAD ("the Company") - Proposed Acquisition of the entire equity interest in Inverfin Sdn Bhd ("Proposed Acquisition")

IOI Corp’s RM73m deposit for Menara Citibank forfeited

Shocking! Everyone was simply shocked!

In the following article on bizweek,IOI Corp should better explain why it’s losing its RM73mil deposit, the following issues were raised!

  • So, why is that changed in three months? Was there an exodus of tenants from Menara Citibank? Did the rental income drop? Was there a collapse in office space prices? Why is the acquisition not strategic anymore?

    Why could not IOI Corp have foreseen these problems earlier? After all, the subprime crisis was already upon us. Why did it pay the deposit which it now has most likely lost if it had felt there could be problems?

    IOI Corp’s explanation is poor at best and we really don’t know what it is at worst. Investors certainly expect a lot more from this company, once the darling of the stock market. And so should regulators. Minority shareholders certainly have a right to be seriously upset.

    Coming so soon after its recent debacle where it reported foreign exchange losses of over RM312mil for the quarter to end-September, the latest episode will put another dent in its reputation, largely unsullied until the forex episode.

It was shambolic in my flawed opinion. As mentioned the global crisis was a known issue then. Why did IOI still insist on a deal worth 586 million to buy Menara Citibank? Did the success of the insane profits got to their heads? Did it?

And sad to say this is so embarrassing for IOI. Losing 73 million makes them such a 'water fish'!

A day after IOI lost its 73 million, Flitch announces that it is lowering IOI credit rating and cites higher risk. Few days later Moody's cuts IOI Corp's credit rating

  • IOI Corp , Malaysia's second-largest palm oil producer, had its credit rating cut by Moody's Investors Services, which said the company's share buyback and "hefty" capital distributions have increased its debt.

Ouch!

Yesterday IOI Corp announced its earnings.

Quarterly rpt on consolidated results for the financial period ended 31/12/2008

Net earnings is now only 168 million. Last quarter it had 290.50 million. A year ago same period, it had 581 million in profits! (Citigroup's profit forecast of rm2.1 billion for IOI is now really looking absurd now!)

Ouch!

With the recent strength of the USD, coupled with the weakness in the Malaysian Ringgit ( Comments And Views On Ringgit Fall To Two Year Low ) , I was naturally not shocked to see that IOI is saying that its Q2 net hit by forex losses, IOI Q2 net profit falls

  • IOI Corp Bhd’s second-quarter ended Dec 31 net profit plunged 71% to RM168.6mil from RM581.2mil in the previous corresponding period on falling palm oil prices, huge foreign exchange losses and a weak property market.

    The drop in profit also calls for a lower dividend for shareholders. For the period under review, IOI Corp proposes to pay out 3 sen per share compared with 7 sen per share paid a year earlier.

The news of the lower dividend is not going to be well received! (edit: On Star's Bizweek Is dividend under threat? - time to re-evaluate one's opinion on the safety of investing for a stock's dividends. Reason is simple. If earnings falls drastically, companies COULD cut their dividends as seen in IOI's example here!!! )

How?

Here I sit wondering again the same issue as I had written earlier.

  • I was thinking out loud fast. During the good times, it was just in May's quarterly earnings, it had forex gains of over 226 million in its book. But it kept quiet on how this forex gains did boost its earnings. Now they have a forex losses, they start using it as an excuse for their poor earnings.

Same issue yes? Last time they mention nothing when they book some 226 million profits from forex gains. Now they have this forex losses, they make such a big fuss over them.

Am I wrong to point this issue out?

The following is a screen shot of their total borrowings from their earnings report last night.


Under the long term borrowings, USD denominated loans totals 1.100 Billion and IOI values these borrowings at 3.816 billion. This should works out to an exchange rate of around 3.43.

Yesterday at 5pm, the ringgit was traded at 3.6770/6790 against the dollar.

Let's reflect back on the earlier point made on IOI taking more USD denominated loans!

The assumed collapse in USD has not happened!

And IOI borrowed more!

And now what they had borrowed equates to them owing more money!!!!

And the longer the ringgit remains weaker against the USD, the greater the pain for IOI Corp!

Here's the USD vs MYR one year chart again. (see Charts Of USD Vs Other Currencies On a One Year Time Frame )


Does the ringgit looks like it's going to strengthen against USD anytime soon?

Ouch!

And double Ouch!

How?

In my flawed opinion, it looked like IOI Corp made several bad moves during their record breaking year last year.

They assumed the USD was going to tank, so they borrowed more in USD. ( Yes, one day the USD could tank but hey don't ask me, I do not know when!)

They got itchy and went into an agreement to buy an office tower. They lost 73 million!

They lost huge money with their forex hedging (sorry to complicated for me to comment on what exactly they did!)

Ouch! Ouch! Ouch!

I do not know but on hindsight now, do you think that they should have been more prudent during their great times last year?

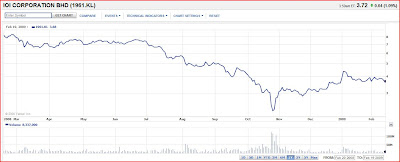
Here is the one year chart for IOI Corp. Ouch!