Showing posts with label Scomi. Show all posts

Thursday, November 11, 2010

Scomi Squashes That According To Sources Article...

Posted yesterday: And According To Sources......

Well according to that piece...


  • Scomi Group Bhd was among the most active counters on Bursa Malaysia yesterday, with some 24.8 million shares changing hands.

    Market talk has it that there could be new substantial shareholders in the form of Indonesian investors and Middle Eastern funds surfacing in the company quite soon.

    The new shareholders, according to sources, have been accumulating Scomi Group shares on the open market for sometime now and are close to surfacing in the company.

    Details, however, were not available at press time....

It begs the question how this can be considered journalism.

Everything is all based on 'market talk'.

So what's market talk? Gossip? Rumours? Hot air?

And despite, the details, not available at press time... that reporter decide it was fit to be considered a financial news and published it.

And the end result?

On today's Business Times:

  • Scomi: No change in shareholding

    Published: 2010/11/11

    SCOMI Group Bhd has clarified that there is no change in the shareholding of its major shareholders or any change to the indirect interests of Datuk Kamaluddin Abdullah.

    Scomi also said there is no change in the shareholding structure of Kaspadu Sdn Bhd, its major shareholder which is controlled by Kamaluddin.

    It added that Kamaluddin’s effective stake in it continued to be 50 per cent that of Kaspadu, or 89.26 million shares representing a 7.65 per cent stake.

So how?

------------------------- update 5:22 pm --------------------------------

And just on the Daily Edge:

  • Scomi Group yet to receive notice on shareholdings
    Written by Jose Barrock
    Thursday, 11 November 2010 10:57

    KUALA LUMPUR: The Scomi Group Bhd counter continued its active trade on Bursa Malaysia yesterday with some 59.6 million shares changing hands, gaining four sen to close at 45.5 sen, its highest level for the day.

    An article from yesterday reported that there could be new shareholders in the form of Indonesian investors and Middle Eastern funds surfacing in the company, and also the possible exit of Datuk Kamaluddin Abdullah, who partly owns substantial shareholder Kaspadu Sdn Bhd. ( LOL! Yo Jose! How about the fact you wrote that article yourself?)

    Scomi Group yesterday said it has yet to receive any official notification on the matter
    . Under the listing requirements, shareholders have a grace period of up to seven days from the share transactions before they inform the company and the stock exchange. When queried by Bursa Malaysia, Scomi Group said “it has not received any notification of interest of substantial shareholders (Form 29A) from any party not presently a substantial shareholder of the company”.

    Scomi Group added it has not been notified of any change to the indirect interests of Kamaluddin and that there has been no change in the shareholding structure of Kaspadu, with Kamaluddin’s effective interest in Kaspadu at 50%, or 89.26 million shares representing 7.65% equity interest in the company.

    The company added: “In the event that there are any new developments in this matter, we will make appropriate and complete disclosure in a timely manner in accordance with the requirements of the exchange.”

    As at end of May this year, Kaspadu had 178.52 million shares or 15.44% equity interest in Scomi Group. In April last year, Kaspadu and its unit Onstream Marine Sdn Bhd had 34.23% or 345.33 million shares. However in September 2009, Kaspadu commenced selling small blocks of shares in the open market.

    Scomi Group has its mainstay in the provision of mud drilling fluids, a water-based drilling fluid used to reduce friction.

    Scomi Engineering Bhd, a 69.31% unit of Scomi Group, closed at RM1.10, gaining five sen, while Scomi Marine, a 42.71% subsidiary of Scomi Group, inched up one sen to close at 54 sen.

Too cartoonic!

Makes a whole mockery of 'journalism'.

Simple question: Why the need to jump the gun and publish this story when there is no confirmation of details?

ps: Where is JS? LOL!


Wednesday, November 10, 2010

And According To Sources......

I was reading the following article.

I LOL-ed like crazy!


  • New shareholders to surface in Scomi Group?
    Written by Jose Barrock
    Wednesday, 10 November 2010 14:03

    KUALA LUMPUR: Scomi Group Bhd was among the most active counters on Bursa Malaysia yesterday, with some 24.8 million shares changing hands.

    Market talk has it that there could be new substantial shareholders in the form of Indonesian investors and Middle Eastern funds surfacing in the company quite soon.

    The new shareholders, according to sources, have been accumulating Scomi Group shares on the open market for sometime now and are close to surfacing in the company.

    Details, however, were not available at press time.... ( rest of article: here )

I nearly felli off the chair when I got to that part!

Let me get this correct...

So 'according to dunno what sources' some 'new' shareholders have been accumulating Scomi Group.

However.... details were not available at press time.

Wakaka!

I suggest the Edge ask the reporter to submit this lovely piece of article to the journalism school.

:=)

Yeah... only in the financial world....

Friday, July 16, 2010

Huge Payday For Scomi Engineering Investors And...... Scomi Group

Yeah I SAW Scomi Engineering's Special Dividend announcement. Yummy! A special dividend payment of 29.5 sen. (well to be more precise it is 23.5 sen tax exempt and 6 sen less tax of 25% or 28 sen nett)

Then something just clicked.


Aha Scomi Group.

Why? I recalled the posting on Scomi Group posted last month: Scomi Creditors Allows Scomi To Postpone Repayment Of 630 Million.

Well posted on that posting, as per Scomi Group's last reported earnings, at end March, Scomi Group had 135.191 million in cash and total debts of 1.303 billion and Scomi Group had some 630 million medium-term notes that needed to be redeemed but somehow its creditors were kind enough to allow Scomi Group postpone the payments.

630 million medium-term notes to be redeemed.

Big bucks.

And yeah, it's nice to know there are still kind creditors around. :D

Now Scomi Group, as per Scomi Engineering's 2009 Annual Report, Scomi Group owns 69.31% of Scomi Group or some 192,567,567 shares of Scomi Engineering. A 28 sen dividend from Scomi Enginerring should work out to close to 54 million! (Do correct me if I am wrong or flawed in my calculations. :D )

Now I had written on Scomi Engineering before, in Nov 2009, I posted
A Quick Look At Scomi Engineering's Quarterly Earnings.

Anyway, fast forward to present day. Scomi Engineering's last reported earnings was on May 2010:
Quarterly rpt on consolidated results for the financial period ended 31/3/2010. A quick check would show that cash balances is around some 49 million and total debts is about 225.468 million.

Now Scomi Engineering had announced earlier about its disposal of assets plans, ie the disposal of Machine Shop Business for USD101 million. See announcement here:
Announcement_SEB.pdf

Sounds familiar?


No?

And then .... what about all them postings on its recent disposals of assets?

Hmmm.... doesn't it 'suddenly' not fall nicely into the small picture?

Just posted the other day: Do You Think Scomi Marine Is Doing A Fire Sale?

Oh... gosh... that 'the other day'... was just two days ago! Oh my! How time flies so quickly.... when there is no FIFA. :D

Anyway after the disposals of assets , as per my flawed calculations, Scomi Marine should be net cash of around 486 million. The experts thinks it should be around 522 million. Ok, say I am wrong and let's use that 522 million. Ya.. the more the better. :D

Now as per the 'according to source' theme mentioned in that news article highlighted in the posting, Do You Think Scomi Marine Is Doing A Fire Sale?, Scomi Marine is speculated (they use the word 'may' :P ) to make a capital repayment.

Huhu... capital repayment.


I wonder how small Scomi Group shareholding in Scomi Marine.

Well, according to Scomi Marine's 2009 annual report, Scomi Group owns some 42.71% of Scomi Marine or 313,043,478 shares.

Hmm... 42.71% of 522 million.... is how much?


Hmm... that should be around 222 million.

But ... but.. but... I don't see Scomi Marine making a full capital repayment of 522 million... I just don't see.... lol... unless I am blind of course. LOL!

Anyway... IF Scomi Marine do make a capital repayment... ya... Scomi Group would get the bulk of the money.... how much? I dunno. It depends on the IF and HOW BIG is the capital repayment.

And this is where it all clicked in...... let me see if I can get it correct... but if I am wrong... lol... I am wrong. Don't bash me up for it. :D

Let's see.... the chain of events here....

Scomi Engineering announces disposal of asset... then .... Scomi Engineering announces NICE special dividend.

Scomi Marine announces disposal of asset... err... Scomi Marine... speculated to make capital repayment.


And oh yeah.. Scomi Group is the largest shareholder....


Oh.. Scomi creditors just recently allowed Scomi Group to postpone its loan payment due...


Hmmmm........ mmmmm...... mmmmmmmmmmmmm


PS: THIS IS NOT A STOCK TIP!

LOL!

How many times need I say that I am NOT a SOTONG? :P

Tuesday, June 15, 2010

Scomi Creditors Allows Scomi To Postpone Repayment Of 630 Million

This one news clip on Business Times caught my attention.


  • Scomi unit creditors agree to deferment

    Published: 2010/06/15

    SCOMI Group Bhd said creditors of wholly-owned unit Scomi Oilfields Ltd have agreed to defer the repayment of its RM630 million medium-term notes by three years and put in place new profit rates.

    The notes will now mature between December 2013 and December 2016.

    They have also agreed that between 2010 and 2013, pre-determined amounts of the notes would be redeemed by Scomi, the group said in a statement to Bursa Malaysia.

Here is the announcement on Bursa: Scomi Final 140610.pdf

  • CIMB Investment Bank Berhad wishes to announce, on behalf of SGB, that the noteholders of KMCOB Capital Berhad’s RM630 million nominal value Murabahah medium term notes have approved the Debt Rationalisation Exercise. The Debt Rationalisation Exercise has been completed on 14 June 2010.

Now I remember Scomi. I had blogged few times on it before. My last posting was on Nov 2009: A Look At Scomi's Earnings which was a mere update to the posting more than a year ago in May 2009, A Quick Look At Scomi Group's Latest Earnings.

Now I want to compare Scomi latest earnings reported in May 2010 to what I wrote on May 2009.

Let me paste what I wrote....

--------------------

For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.
For its fiscal year 2005, Scomi Group announced an earnings of 151.692 million.
For its fiscal year 2006, Scomi Group announced an earnings of 84.545 million.
For its fiscal year 2007, Scomi Group announced an earnings of 257.149 million.*
For its fiscal year 2008, Scomi Group announced an earnings of 116.553 million.

*note 2007, see q2 earnings. Earnings was distorted in a positive manner due to disposal of its holdings in Scomi Oilfield limited*

On Feb 2009, Scomi announced it made some 40 million.
Quarterly rpt on consolidated results for the financial period ended 31/12/2008

Last night.
Quarterly rpt on consolidated results for the financial period ended 31/3/2009. Scomi announced its earnings were only some 9.5 million!! (Same quarter a year ago, it made some 21 million) oO

I was also curious on some of the key balance sheet issues mentioned last time. I would mark the current numbers in green.

1. Cash is at 87.595 million. (Cash now is at 301.518 million.) Cash is now 135.191 million.

2. Trade receivables has increased to 438.430 million. (Trade receivable is now at 497.968 million.) Trade receivables is now at 862.085 million!!!!!!!!!!!!

3. Group's borrowings is now at 918.363 million. (Group borrowings is now at 1.330 BILLION!!) Group's borrowings is now at 1.273 Billion.

---------------

Those were the 3 yardsticks I had focused on. Cash, Receivables and Borrowings.

Here is Scomi's earnings reported last month, May 2010: Quarterly rpt on consolidated results for the financial period ended 31/3/2010

1. Short-term deposits, cash and bank balances

Current Short-term deposits, cash and bank balances totals 211.449 million.

Scomi cash was at 135.191 million so this looks like a massive improvement, yes?

However, if one looks at the cash flow statements, in Feb 2010, cash flow showed that cash was boosted by 151.580 million thanks to 'Proceed from ICSLS'. Cash balance in Feb quarterly earnings showed Scomi had some 315 million in cash balances.

So cash is up, thanks to Scomi's issuance of new ICLS shares.

2. Trade receivables

Receivables is now at 849.566 million. A year ago, it was 862.085 million. A slight improvement.

However, the question that really begs to be answered is why is Scomi's receivables so extremely high? Can we have an audit to check if any of these receivables need to be reclassified as doubtful debts? Surely, this is a reasonable request yes? These receivables have been in Scomi's book for sometime now. Can it be collected? If not, it needs to be classified as bad debts (And when it does happen, Scomi will be hit hard with huge provisions!)

3. Borrowings.

Scomi's total borrowings is at 1.303 billion! A year ago it was 1.273 billion.

ps: in the posting Regarding Scomi, in Scomi's fiscal year 2003 Q2 earnings, its total loans were only some 18.617 million! (ps: that posting Regarding Scomi would be a good reference on Scomi's performance since listing.)

How?

How would you describe Scomi's current financial position? Huge debts, poor cash flow and poor collection of receivables?

Would that be a flawed assessment?

Now let's put the Business Times article into perspective...

  • SCOMI Group Bhd said creditors of wholly-owned unit Scomi Oilfields Ltd have agreed to defer the repayment of its RM630 million medium-term notes by three years and put in place new profit rates.

    The notes will now mature between December 2013 and December 2016.

    They have also agreed that between 2010 and 2013, pre-determined amounts of the notes would be redeemed by Scomi, the group said in a statement to Bursa Malaysia.

Ahem... Scomi had 630 million medium-term notes that needed to be redeemed. It's now postponed...

Isn't it so nice that Scomi's creditors are allowing Scomi to postpone the repayment?

How?

Friday, November 06, 2009

A Look At Scomi's Earnings

Since I blogged on Scomi Engineering's Quarterly Earnings I was interested to read on how its holding company, Scomi Group, performed. More so since I had blogged on it many times before ( see here )

Firstly, a Business Times news brief.


  • SCOMI Group Bhd’s third quarter net profit was up 19 per cent to RM23 million mainly due to contributions from the energy and logistics engineering divisions.

    Revenue for the quarter to September 30 2009 was 19 per cent higher to RM424.1 million mostly generated by the oilfield services division and the energy and logistics engineering division.

    Scomi said its oilfield services division will continue to be hit by the global recession this year but its rail unit would lead its performance this year.

Net profit up 19 percent.

But it doesn't state HOW the numbers were up! It's like, what are the comparison figures used? Time to dig out DJ Tables for a better picture.


Ah.. comparison was made versus previous year same period.

However, as one can also clearly see, the 9 months comparison, showed that Scomi's current 9 moth fiscal earnings total of 53.338 million showed a decline of 22.35 million or a decline of around 29 percent!

Hmm.. decided to highlight the positive only? (Isn't this so typical nowadays?)

Anyway, in May 2009, I wrote the following: A Quick Look At Scomi Group's Latest Earnings

In that posting I highlighted the key balance sheet issues. Let me repaste here and I will add in this quarterly earnings numbers in red font and new comments in brown.

Back to May 2009 >>>>>

I was also curious on some of the key balance sheet issues mentioned last time. I would mark the current numbers in green.

1. Cash is at 87.595 million. (Cash now is at 301.518 million.) Cash is now 135.191 million. Cash is now 138.616

Cash balances did increased but the increase is so minute. Now I am wondering. In Aug, Scomi said it had net profit of some 20.853 million and yesterday its net profit was some 22.975 million. Adding them up, since May 2009, Scomi had some net profit of 43.828 million. So why hasn't the cash balances reflect these much improved net earnings? Where the Moola go?

2. Trade receivables has increased to 438.430 million. (Trade receivable is now at 497.968 million.) Trade receivables is now at 862.085 million!!!!!!!!!!!! Trade receivables is now at 868.648 million.

And needless to say, why are these receivables so high and for so long? Why hasn't Scomi Group made an attempt to collect these receivables? Could they not be collected? If no, then shouldn't these receivables be re-classified as bad debts?

3. Group's borrowings is now at 918.363 million. (Group borrowings is now at 1.330 BILLION!!) Group's borrowings is now at 1.273 Billion. Group's borrowings is now at 1.308 Billion!!!!!

>>>>

How?

Since receivables to a company equates to what is owed to the company, does it make sense for Scomi to owe the bank a staggering 1.308 billion when other people owe them some 868.648 million?

Owe bank, one need to pay interest.

Others owe you, do you get interest for amount owed?

I wonder.

Oh, needless to say, some would be extremely quick to point out the rights issue!

Yeah, Scomi wants the local market help ease their financial burden. Yeah, Scomi wants the local market to 'invest' more money in them! LOL!

(ps: Silly me, why can't Scomi collect those receivables, ah?)


How?

You want or not? You want to 'invest' or not? Shares that had rights issue and warrants had been so popular recently mah. It's the IN thing, no?

No need to talk fundamentals, just buy!

LOL!

Oops... where's my disclaimer?

DO NOTE THAT I HAVE NO IDEA IF YOU CAN LOSE MONEY IF YOU DECIDE TO LISTEN TO MY FLAWED COMMENTS!

That should do it!

:D

Friday, May 15, 2009

A Quick Look At Scomi Group's Latest Earnings

Had not posted an update on Scomi Group for a long time.

Here are some older postings done on Scomi Group.

From that last posting, Update on Scomi Group

  • Scomi group announced its earnings last night. Now I will add in Scomi latest earnings to my comments in bold blue.

    For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
    For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.
    For its fiscal year 2005, Scomi Group announced an earnings of 151.692 million.
    For its fiscal year 2006, Scomi Group announced an earnings of 84.545 million.

    ( And its fiscal year 2006 earnings is achieved on the back of its sales revenue increasing from 1.067 BILLION to 1.575 BILLION. WOW! Incredible. Despite an increase of its sales revenue by as much as 500 million, its earnings fell from 151 million to 84.545 million!!)

    Let's compare some key balance sheet items mentioned before. New comments in bold blue.

    Cash is at 87.595 million. (Cash now is at 301.518 million.)
    Trade receivables has increased to 438.430 million. (
    Trade receivable is now at 497.968 million.)
    Group's borrowings is not at 918.363 million. (Group borrowings is now at 1.330 BILLION!!)

Scomi announced its earnings last night. ( Yeah, some would insist that I am nuts to talk about fundamentals when the current sentiments clearly indicates a trading market! Yes, screw them fundamentals! :p2 )

Anyway let's have a look again.

For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.
For its fiscal year 2005, Scomi Group announced an earnings of 151.692 million.
For its fiscal year 2006, Scomi Group announced an earnings of 84.545 million.
For its fiscal year 2007, Scomi Group announced an earnings of 257.149 million.*
For its fiscal year 2008, Scomi Group announced an earnings of 116.553 million.

*note 2007, see q2 earnings. Earnings was distorted in a positive manner due to disposal of its holdings in Scomi Oilfield limited*

On Feb 2009, Scomi announced it made some 40 million.
Quarterly rpt on consolidated results for the financial period ended 31/12/2008

Last night.
Quarterly rpt on consolidated results for the financial period ended 31/3/2009. Scomi announced its earnings were only some 9.5 million!! (Same quarter a year ago, it made some 21 million) oO

The following is a newsclip on Business Times.


  • Scomi Group Q1 net profit drops

    Published: 2009/05/15

    OIL and gas services provider Scomi Group Bhd(7158) said its first-quarter net profit dropped by more than half from a year ago, due to higher financing, raw material and personnel costs.

    Net profit for the January-March quarter was RM9.5 million, compared with RM21.8 million in the same period last year.

    In its filing to Bursa Malaysia yesterday, the group said the decline in net profit of RM12.3 million, or 56 per cent, was mainly attributable to the higher cost of raw materials, higher personnel costs with additional manpower especially in the energy and logistics engineering division and increase in finance costs.

    Revenue was RM528.2 million, up 10.8 per cent from RM476.7 million a year ago.

    The major contribution came from its oilfield services and the energy and logistics engineering divisions, which collectively generated 93 per cent to the group's revenue.

    Scomi Group said the uncertainty surrounding global markets, weaker consumer demand and tightening credit will continue to impact its performance in 2009.

    Recognising the challenges ahead, the group said it will continue to practice prudent cash and risk management together with measures to improve cost savings and productivity.

I was also curious on some of the key balance sheet issues mentioned last time. I would mark the current numbers in green.

1. Cash is at 87.595 million. (Cash now is at 301.518 million.) Cash is now 135.191 million.

2. Trade receivables has increased to 438.430 million. (Trade receivable is now at 497.968 million.) Trade receivables is now at 862.085 million!!!!!!!!!!!!

3. Group's borrowings is now at 918.363 million. (Group borrowings is now at 1.330 BILLION!!) Group's borrowings is now at 1.273 Billion.

How now my dearest Brown Cow?

ps... I have no idea how Scomi Group stock will trade. If you make or don't make money, you do not have to thank me. :D

Tuesday, February 27, 2007

Update on Scomi Group

Last May 2006, I wrote the following posting: Regarding Scomi

  • So let's look at how did Scomi do since its listing...

    For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
    For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.
    For its fiscal year 2005, Scomi Group announced an earnings of 151.692 million.

    And there you have it mate, yes it is true that Scomi has an astonishing growth rate!

    But how about them points again? Well, as at its last reported earnings...

    Cash is at 87.595 million.
    Trade receivables has increased to 438.430 million.
    Group's borrowings is not at 918.363 million.

    And yes, I do understand your issue that leverage can be used to generate a much higher revenue but on the other hand, I do hope you realise that this leverage issue is a matter of personal views and opinions. Me, for one, believe that too much leverage can turn deadly if one is not prudent enough.

Scomi group announced its earnings last night. Now I will add in Scomi latest earnings to my comments in bold blue.

For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.
For its fiscal year 2005, Scomi Group announced an earnings of 151.692 million.
For its fiscal year 2006, Scomi Group announced an earnings of 84.545 million.

( And its fiscal year 2006 earnings is achieved on the back of its sales revenue increasing from 1.067 BILLION to 1.575 BILLION. WOW! Incredible. Despite an increase of its sales revenue by as much as 500 million, its earnings fell from 151 million to 84.545 million!!)

Let's compare some key balance sheet items mentioned before. New comments in bold blue.

Cash is at 87.595 million. (Cash now is at 301.518 million.)
Trade receivables has increased to 438.430 million.
(Trade receivable is now at 497.968 million.)
Group's borrowings is not at 918.363 million. (Group borrowings is now at 1.330 BILLION!!)

WOW!!!

Incredible isn't it.

Last fiscal year, Scomi Group was at a net debt position of 830.768 million. A year later, Scomi Group is now at a ned debt position of 1.028 BILLION.

WOW!


Saturday, November 18, 2006

Compelling Reasons to Privatise Scomi

The Star Bizweek has an article on Scomi Group, To privatise or not? , in which it states the compelling reasons why Scomi Group should be privatised. ( Refer recent blog posting: Privatisation of Scomi? and Update on Scomi )

I find it rather strange the need for this article.

Really.

After all, if you look at the blog posting, Privatisation of Scomi? , you would note that the whole 'story' is based on nothing but speculation and of course the in famous 'according to sources'.

This was what printed by the Business Times article on November 15.

  • SPECULATION is rife that major shareholders of Scomi Group Bhd may take the integrated oil services firm private in a bid worth as much as RM1 billion.

    Sources said the main shareholders, who include the son of Prime Minister Datuk Seri Abdullah Ahmad Badawi, are considering this as an option as Scomi's market price does not reflect its true value.

SPECULATION is rife and SOURCES said.

Ever wonder why can't our financial report news based on facts and nothing but facts?

Do you want to read news based on SOURCES?

Let me repeat a thousand times again. Anyone can be a source. Anyone. You, me, the makcik or the Ah So cleaning the toilet. The driver. The office boy. They all can be a source.

So today we have an article posted in The Star Bizweek which ATTEMPTS to JUSTIFY this speculation. And they even have TA Securities head airing out his compelling reasons to privatise the stock.

  • First off, the timing is right. TA Securities' head Kaladher Govindan is just one of those many who perceive Scomi as being undervalued.

    “Going by current prices, it's advisable to take it private,” he says, pointing out that the company is ripe with future growth potential, as evinced by such developments as its recent penetration of the US market. Indeed, Scomi has gone on record as stating that it expects to more than triple its sales to US$1bil by 2009.

    The upshot of this is that keeping Scomi listed would mean sharing those future profits with the public. Conversely, privatising the company would largely benefit its major shareholders.

    Such a move would also provide the company with a greater deal of flexibility by removing the need to keep up with the regulatory framework, in addition to obtaining shareholders' approval for certain decisions.

    Second, Scomi is now susceptible to what is known as holding company discount. Buying into a conglomerate that has a number of subsidiaries engaged in diverse activities under their umbrella is often a bit of a mixed bag, as investors may not want to be exposed to each of these individual companies.

    In this instance, especially when a holding company has successfully listed a number of its subsidiaries, buying directly into a subsidiary may represent a better way to get direct exposure. From the perspective of the company itself, analysts feel there is sufficient reason to de-list Scomi as funding for expansion can be raised at the subsidiary company level.

    To illustrate the former point, Scomi Engineering Bhd was trading almost 50% higher than its parent two weeks ago. Even after the recent uptrend in Scomi's price, following the recent spate of news, it is still trading 25% lower than its subsidiary.

    Financials and elephants

    Third, Scomi can afford it. The company's announcement some months ago that it would undertake a restructuring exercise to streamline its subsidiaries was viewed favourably by analysts, along with the proposed listing of KMC Oiltools Bermuda Ltd on the Singapore Stock Exchange under the name Scomi Oilfields Ltd (Oilfields).

    With the exercise expected to raise up to half a billion ringgit for Scomi, a privatisation exercise was among the many methods mooted to prevent the cash burning a hole in Scomi's deepened pockets.

    As major shareholders, Datuk Kamaludin Abdullah and CEO Shah Hakim Zain own about 34.7% of the company between them. TA Securities reckons they would have to cough out between RM787mil and RM984mil based on the speculated price range of between RM1.20 and RM1.50.

    “We believe the major shareholders could obtain part of the funding from the group’s possible capital repayment exercise with the listing of Oilfield Services on the Singapore exchange that could raise up to RM700mil (inclusive of the RM130mil from settlement of inter-company loans),” says the house.


How?

Let's take a look at Scomi Group again.

Here is the link to their last reported quarterly earnings:

Quarterly rpt on consolidated results for the financial period ended 30/6/2006

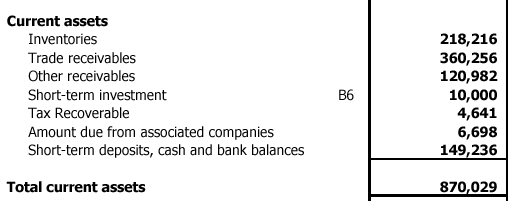
let's look at the balance sheet. It's current assets.


And the below is their group borrowings.

Well, group loans totals 1.053 BILLION. Groups piggy bank cash is only 149.236 million, which gives one a nett debt of ONLY 903. 946 million.

My simple question again.. once Scomi Group is privatised, who owns this debt?

Thursday, November 16, 2006

Update on Scomi

Update to earlier blog psoting: Privatisation Of Scomi

Just saw this earnings announcement:

SCOMI GROUP BERHAD
ARTICLE ENTITLED: "Scomi to be taken private?"

  • Reference is made to a query from Bursa Malaysia Securities Berhad dated 15 November 2006 in relation to the article appearing in The New Straits Times (Business Times, page 39) on Wednesday, 15 November 2006 and in particular pertaining to the statement which is reproduced as follows:
    -"…major shareholders of Scomi Group Bhd may take the … firm private in a bid worth as much as RM1 billion."

    The Board of Directors of Scomi Group Bhd wishes to advise that, the Company is not aware of any plan or intention by its major shareholders relating to the issues highlighted in the said article and has not received any notice from its major shareholders relating thereto.
    In addition, the Company has made due enquiry with its largest shareholder, Kaspadu Sdn Bhd, and has been informed that although Kaspadu has received a number of preliminary proposals relating to its stake in the Company, no decision with respect thereto has been made that warrant announcement by the Company.

So who COOKED UP the story??

:P

Privatisation of Scomi?

Yesterday, there was an article stating that Scomi could be taken private.

Scomi was a stock that I had blogged a couple of times before. See
regarding scomi , regarding scomi group again. (recommended reading :D ) and scomi again

  • Scomi to be taken private?
    By Shahriman Johari
    ashahriman@nstp.com.my

    November 15 2006

    SPECULATION is rife that major shareholders of Scomi Group Bhd may take the integrated oil services firm private in a bid worth as much as RM1 billion.

    Sources said the main shareholders, who include the son of Prime Minister Datuk Seri Abdullah Ahmad Badawi, are considering this as an option as
    Scomi's market price does not reflect its true value.

    Taking it private could also in a way address unwarranted criticism that the group was favoured in bidding for government contracts because its major shareholder, Datuk Kamaludin Abdullah, is the son of the Prime Minister.

    Officials of Scomi, which makes drilling fluids that cool drilling heads and provides drilling waste management services, could not be reached for comment.

    Scomi's chief executive officer, Shah Hakim Zain, did not answer calls made to his handphone.

    Major shareholders could bid for the rest of Scomi at a price range of RM1.20 to RM1.50 a share, bankers said, citing swirling market speculation. The stock closed 6.2 per cent up at RM1.03 yesterday.

I am a strong believer that no corporate will embark on a corporate exercise if there is no monetary benefit to the corporation.

Is it profitable to take Scomi Group private? Have a look at this blog posting (scomi again )

Yes, Scomi made a remarkable record high earnings of 23.657 million for its last announced quarterly earnings.

But..

look at the bottom-line.

This company is in a NETT DEBT position of 903.946 million.

Let's look at what the article said next.

  • "Scomi has a very strong cash flow. And based on what's been said about it, it makes sense for them to do it," said an executive close to the group.

    The major shareholders of Scomi are Kamaludin and Shah Hakim. Both hold 34.66 per cent of the company through Kaspadu Sdn Bhd as at May 11 2006.

    French insurance group AXA is the second biggest shareholder with 6.3 per cent, followed by the Employees Provident Fund with 5.73 per cent.

    This means that if the main shareholders were to make a bid for the rest of the shares, they might have to fork out some RM976.6 million based on an offer of RM1.50 a share.

    In September, Scomi said it expected to more than triple its sales to US$1 billion (RM3.64 billion) by 2009, helped by organic growth and new technology.

    "We are growing at a very fast pace, and certain markets this year will have between 50 per cent and 80 per cent growth," Shah Hakim said at the time.

Strong cash flow said an executive close to the group???

Could this EXECUTIVE define STRONG CASH FLOW????

Remember, back in Scomi's fiscal year 20003 Q2, Scomi Group was a simple stock earning 4.037 million for the quarter. But it's net debt was a mere 7.515. Very manageable. Look at it now. In a nett debt position of 903.946 million!

Is this the STRONG CASH FLOW?

How very strange!

I wonder which EXCUTIVE said that statement.

In today's Star, there's an artilce entitled "Scomi up on privatisation talk".

  • “The possibility of Scomi being taken private is high as the group’s shares are grossly undervalued and, with all of its subsidiaries listed (after the listing of its oil field services division (OSD) on the Singapore Stock Exchange next year), it makes sense to take it private,” TA Securities said in a note.

Grossly undervalued? LOL!!!

  • Meanwhile, sources said an announcement on a proposed privatisation of the group could be made soon.
    The TA Securities note said based on an indicative price of RM1.20 to RM1.50 per share, the privatisation deal could cost the group’s major shareholders, Datuk Kamaludin Abdullah and Scomi chief executive officer Shah Hakim Zain, RM787mil to RM984mil.

As, I was saying earlier, "I am a strong believer that no corporate will embark on a corporate exercise if there is no monetary benefit to the corporation."

So do you think it make sense to partake in a deal worth rm787 to rm984 million to fully own a company that has a nett debt of RM903.946 million???

Doesn't make much sense to me.

What say you?


Tuesday, August 29, 2006

Scomi again

Scomi reported a record earnings of 23.657 million. It's highest ever.

Problem?

Its nett debt position is now at 903.946 million.

Ahem!

Compare that to what I just wrote the other day... Regarding Scomi Group Again

  • Yes, the sales and net profit has increased a lot but do you see any creation of wealth?

    Back then, 03 Q2, Scomi Group was a simple stock earning 4.037 million for the quarter. But it's net debt was a mere 7.515. Very manageable.

    Today Scomi? 06 Q1, Scomi Group is now a complex Godzilla, earnings some 16.069 million for the quarter, which is about 4 times more than it earned back in 2003 Q2. Fantastic. Bravo. But just look at the cost of such engineering of wealth. Scomi Group is now in a nett debt positiion of $846.778 million.

    How?

There are some articles on The Edge Weekly.

Cover Story: Close to tipping point

Stories By Lim Ai Leen

Cover Story: Shah Hakim speaks
The Scomi Group CEO talks candidly about earnings, shareholder returns and Kamaluddin Abdullah

Cover Story: How it all started

Saturday, August 19, 2006

Regarding Scomi Group again.

Dedicated to The Killer! :-)

On 6th May 2006, I wrote the following:

I had actually made a posting on Scomi Group before. Let me reproduce what I have written on it. ( Sorry dude, it's just have gottabe long! )

<<==>>

Firstly, I have to say this. IPO subsribers to SCOMI would be really darn please with their investment if they held the stock from the start to now!

Scomi was offered to the public at a price of 1.38. Listed on May 2003.

In April 2004, there was a 3 for 5 bonus issue and then a 1 into 5 stock split.

  • 08/04/2004 Entitlement - Others

    For illustrative purposes, a shareholder holding 100 ordinary shares of RM0.50 each in SCOMI on the Entitlement Date shall be entitled to 60 ordinary shares of RM0.50 each in SCOMI pursuant to the Bonus Issue. Subsequently, his/her entire 160 ordinary shares of RM0.50 each shall be subdivided into 800 new ordinary shares of RM0.10 each in SCOMI.

So say, for simple illustrative purpose, someone subscribed to 5,000 shares of Scomi at 1.38 during Scomi's IPO, their capital outlay will be 1.38x5 = 6900.

So after the stock bonus, this investor would now hold 8 lots of Scomi. And after the stock split, the investor would be having 8x5 = 40 lots or 40000 shares.

So at closing price of 1.17 (this was the price of Scomi on 3rd Sept 2005), this investor's investment would be worth 46,800.00.

Which is really a darn good investment return!!!

And the picture below says it all!
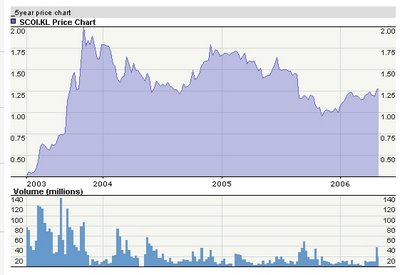
So how did Scomi do since its listing?

For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.

Absolutely commendable. In fact, some would call it as brilliant!

So for the IPO investor, buying the stock of Scomi is looking at his/her company's net profit grow from 14 mil for fy 2003 grow to a very impressive 61.4 million for fy 2004.

Basically, isn't this what we all want in a company when we invest in it?

The company is making more and more moola each year!

Rite?

Now the question is or rather the issue is, we all know that Scomi is growing explosively via acquisition of companies or some would cynically call it the engineering of profits via acquistions.

Anyhow, I guess it would do no harm and it would makes sense if we dig deeper, rite?

And this can be done via some simple observation of its quarterly performance. Just some simple comparison of some key figures.
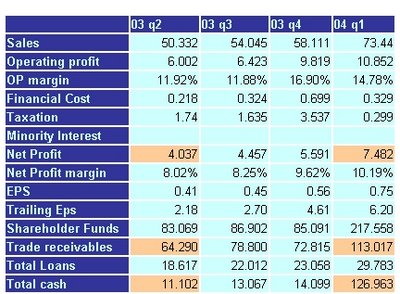


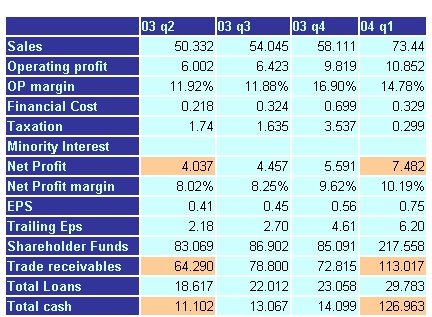
At the start (03 Q2 ), we were looking at a company with the following characteristics...

  1. Company was making about a quarterly net profit of 4 million.
  2. Cash was 11.102 million versus Total loans of 18.617 million. (a net debt position of 7.515 million)

Next we look at 04 Q1...

  1. Company is now making around 7.4 million per quarter. Fantastic.
  2. Cash is now 126.963 million with loans of 29.783. (net cash of 100.180 million). Fantastic.
  3. Slight worries. Trade receivables is now 113.017 million.

A very interesting footnote was found in the cash flow statemtent:

  • 125 million was generated VIA SHARE PLACEMENT EXERCISE and entered into the company's piggy bank.
Let's watch what happens next...


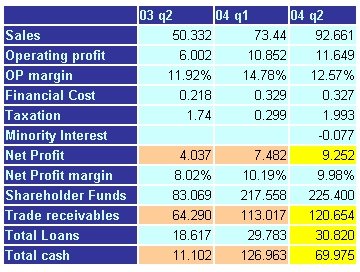
Now we are looking at 04 Q2.

Good points.
  1. Net profit is now 9.252 million. Just the same quarter, a year ago, Scomi was just a company making 4.037 million. Company is making more money isn't it?
  2. Cash stands at 69.975 million versus total loans of 30.820 million. (A net cash position of 39.155 million).
Fantastic isn't it?

But here comes the worrying part..

  1. Trade receivables is now at 120.654 million. (Hmmm... a worrying signal? Hard to say at this moment of time cos after all this quarter Scomi showed a sales revenue of 92.661 million.)
  2. Cash flow. Starting cash was at 126.963 million. A quarter after a share placement issue, in which Scomi generated 125 million in this fund raising exercise. At the end of the quarter, cash is only at some 69.975 million. Where ze Moola go???? (ah ze classical arguement of a company using leverage to expand and grow the company!)

Scomi reported that earnings on 11th Aug 2004.

Let's watch happens in Scomi's next quarter, 2004 Q3.

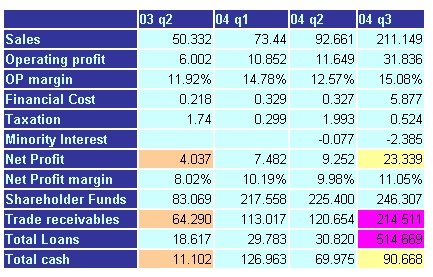
Good point:

  1. Net profit is now 23.339 million. 5 quarters ago, Scomi was just a company making 4.037 million. Company is making more money isn't it? Isn't this what u call explosive growth?

Fantastic isn't it?

And again, here comes the worrying part...

  1. Trade receivables is now at 214 million. (Hmmm... again a worrying signal? And again hard to say cos Scomi had sales revenue of 211 million for the quarter and since with the company made making more sales, more receivables is accumulated, rite?)
  2. Cash is now at 90.668 million but the loans is now 514.669 million. Scomi is now in debt of 424 million!!!! ( A huge worry? )

A flag has been raised, eh? Them same old worrying issues is getting more worrying, isn't it? Time to exit da bugger?

Scomi reported that set of arnings on 3rd Nov 2004.

Next quarter, 2004 Q4 was pretty dull. Pretty much the same old, same old. A neither here or there quarterly earnings report.

So fast forward to 2005 Q1 earnings. Which was really 'interesting'..
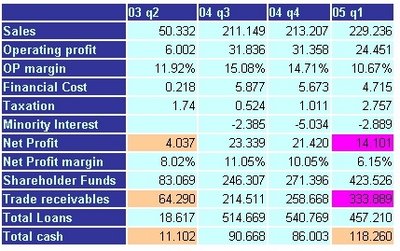

Soooooo many issues!!!

1. Net Profit is only 14 million? Big worry? Down from 20+ mil on a q-q basis...
(ahh.. again... some will argue cos on a y-y comparision.. this 14 million net profit is still much better than the 7 million it earned a year ago).

2. Trade receivables is now 333.889 million. Now this trade receivables is NOW a huge worry cos quarterly sales is now 229.236 million only. Where is that extra 100+ million of receivables coming from? What if a huge portion of these trade receivables turn bad? Bad debts then?

3. Loans? Loans is now 457 million. Down from 540 million a quarter ago.

4. Total cash increased to 118 million from 86 million a quarter ago.

5. Is 3 and 4 a good point? My answer is NO. If one looks at Scomi's Cash flow, Scomi's made yet another share placement to raise cash. A placement which saw Scomi raised 145.476 million.

So what we have is:

Scomi raised cash from placement of shares which is then used to pay off some of its loans....

But how does one evaluate Scomi's earnings performances? Surely if one is a buyer of Scomi's placement shares, one would probably not be too happy with it cos the bottom line is Scomi's net earnings declined from 20+ million to just 14+ million.

Now given 1,2, 3 and 4 and most importantly point 1, Isn't the time to really to exit this bugger?

Scomi reported this earnings on 25th May 2005.

Scomi closed at 1.40 on 25th May 2005.

And here comes the company most recent earnings (in Sept 2005)
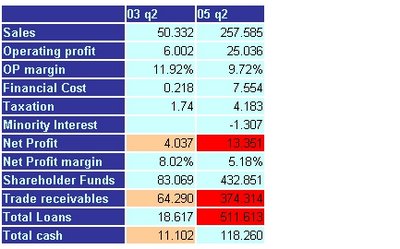

And how did Scomi do?

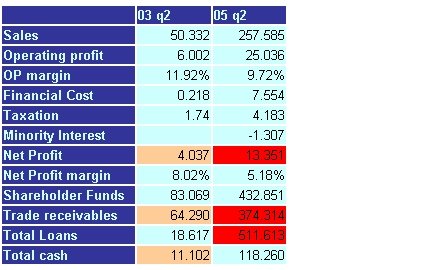
1. Net earnings came in at 13.351 million. Which was down from 20 million plus earnings it earn a couple of quarters ago...

Now why issit such a huge worry?

1. Trade receivables is now a whopping 374 million.

2. Loans. Total loans is now 511 million.Up from a total loans of 457 million a quarter ago. Hmmm.... if one looks at the bigger picture, Scomi did a placement, paid of some 80 million plus in loans but come the next quarter, it borrows yet again. Doesn't it mean that Scomi is now back at square one? At the peak, Scomi total loans once stood at 540 million!!!

How? Now Scomi has been on a sell-off since May. Down some 30% and it is not too surprising eh?

Let's re-examine what has been said.

At the start (03 Q2), we were looking at a company with the following characteristics...

  1. Company was making about a quarterly net profit of 4 million.
  2. Cash was 11.102 million versus Total loans of 18.617 million. (a net debt position of 7.515 million)

8 quarters later, after countless of acquisitions and 2 share placement and sooooooo many ESOS....

We are now looking at....

1. A company making 13 million per quarter.

Compare to the 03 Q2 in which Scomi made only 4 million. An increase of 9 million So company is making 3.25 times more moola.

2. Company cash balance is now 106.119 million. Total loans stand at 511.613 million. Company is now in a net debt of 405.494 million.

Comparison. In Q2, company net debt position was a mere 7.515 million. Now the net debt position has increased by a WHOPPING 53X.

Justifiable given its current earnings? (some would ask: Does it make sense to increase ur total debt position by 405 million to make that extra 9 million in profit???? )

how? how? how?

Would it be wrong to say that this is an insane strategy employed by Scomi????

Oh btw, Scomi now has 991,130,700 shares. How signifacnt is this? Well, back in 03 Q2, Scomi Group had just around 91 million shares! ;p

<<==>>

That was back in Sept 2005. Sorry mate to bore you with all those details but I do reckon that it is useful to understand why Scomi rose so high and why its share price was declining quite a lot late last year (Scomi traded as low as 0.95 back in Nov 2005!).

Anywayyyyyyyyy...

In Nov 2005, Scomi announced its Q3 earnings. Scomi quarterly net earnings increased to 16 million.

In Feb 2006, Scomi announced its Q4 earnings. Scomi quarterly net earnings increased to a whopping 109.539 million!!!

So let's look at how did Scomi do since its listing...

For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.
For its fiscal year 2005, Scomi Group announced an earnings of 151.692 million.

And there you have it mate, yes it is true that Scomi has an astonishing growth rate!

But how about them points again? Well, as at its last reported earnings...

  1. Cash is at 87.595 million.
  2. Trade receivables has increased to 438.430 million.
  3. Group's borrowings is not at 918.363 million.

And yes, I do understand your issue that leverage can be used to generate a much higher revenue but on the other hand, I do hope you realise that this leverage issue is a matter of personal views and opinions. Me, for one, believe that too much leverage can turn deadly if one is not prudent enough.

And by the way, from my live quotes, I do note that as of today, Scomi Groups' number of shares is now 996.208 million shares!!

Yup, it increased yet again. Which means based on this enlarged share base, Scomi's current eps is now 15.2 sen. Ok?

And yes, I had mentioned the perils of a company issued placement shares.

Currently, Scomi does have the earnings to justify its strategy but do remember what happened back then in Sept 2005. Look at how the share tumbled when the earnings wasn't there. Do take note of this issue. It could well happen yet again but then on the other hand, if the Scomi 'produce' those earnings, the market could well go ga-ga over the share again.

Cheers!

<===============>

19th Aug 2006

Scomi reported its 2006 Q1 Earnings on 25th May 2005.

Quarterly rpt on consolidated results for the financial period ended 31/3/2006

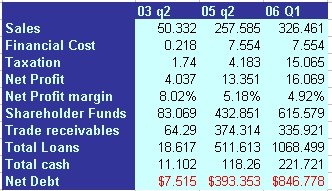
The following table simple table says it all. There different point of time to highlight the progress of Scomi Group as a company.
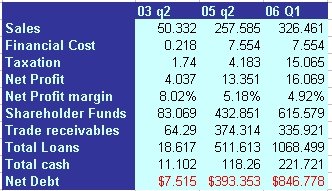

Look at the sales and net profit numbers.

Yes, the sales and net profit has increased a lot but do you see any creation of wealth?

Back then, 03 Q2, Scomi Group was a simple stock earning 4.037 million for the quarter. But it's net debt was a mere 7.515. Very manageable.

Today Scomi? 06 Q1, Scomi Group is now a complex Godzilla, earnings some 16.069 million for the quarter, which is about 4 times more than it earned back in 2003 Q2. Fantastic. Bravo. But just look at the cost of such engineering of wealth. Scomi Group is now in a nett debt positiion of $846.778 million.

How?

Saturday, May 06, 2006

Regarding Scomi

I had actually made a posting on Scomi Group before. Let me reproduce what I have written on it.

<<==>>

Firstly, I have to say this. IPO subsribers to SCOMI would be really darn please with their investment if they held the stock from the start to now!

Scomi was offered to the public at a price of 1.38. Listed on May 2003.

In April 2004, there was a 3 for 5 bonus issue and then a 1 into 5 stock split.

  • 08/04/2004 Entitlement - Others

    For illustrative purposes, a shareholder holding 100 ordinary shares of RM0.50 each in SCOMI on the Entitlement Date shall be entitled to 60 ordinary shares of RM0.50 each in SCOMI pursuant to the Bonus Issue. Subsequently, his/her entire 160 ordinary shares of RM0.50 each shall be subdivided into 800 new ordinary shares of RM0.10 each in SCOMI.

So say, for simple illustrative purpose, someone subscribed to 5,000 shares of Scomi at 1.38 during Scomi's IPO, their capital outlay will be 1.38x5 = 6900.

So after the stock bonus, this investor would now hold 8 lots of Scomi. And after the stock split, the investor would be having 8x5 = 40 lots or 40000 shares.

So at closing price of 1.17 (this was the price of Scomi on 3rd Sept 2005), this investor's investment would be worth 46,800.00.

Which is really a darn good investment return!!!

And the picture below says it all!

So how did Scomi do since its listing?

For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.

Absolutely commendable. In fact, some would call it as brilliant!

So for the IPO investor, buying the stock of Scomi is looking at his/her company's net profit grow from 14 mil for fy 2003 grow to a very impressive 61.4 million for fy 2004.

Basically, isn't this what we all want in a company when we invest in it?

The company is making more and more moola each year!

Rite?

Now the question is or rather the issue is, we all know that Scomi is growing explosively via acquisition of companies or some would cynically call it the engineering of profits via acquistions.

Anyhow, I guess it would do no harm and it would makes sense if we dig deeper, rite?

And this can be done via some simple observation of its quarterly performance. Just some simple comparison of some key figures.


At the start (03 Q2 ), we were looking at a company with the following characteristics...

  1. Company was making about a quarterly net profit of 4 million.
  2. Cash was 11.102 million versus Total loans of 18.617 million. (a net debt position of 7.515 million)

Next we look at 04 Q1...

  1. Company is now making around 7.4 million per quarter. Fantastic.
  2. Cash is now 126.963 million with loans of 29.783. (net cash of 100.180 million). Fantastic.
  3. Slight worries. Trade receivables is now 113.017 million.

A very interesting footnote was found in the cash flow statemtent:

  • 125 million was generated VIA SHARE PLACEMENT EXERCISE and entered into the company's piggy bank.
Let's watch what happens next...


Now we are looking at 04 Q2.

Good points.
  1. Net profit is now 9.252 million. Just the same quarter, a year ago, Scomi was just a company making 4.037 million. Company is making more money isn't it?
  2. Cash stands at 69.975 million versus total loans of 30.820 million. (A net cash position of 39.155 million).
Fantastic isn't it?

But here comes the worrying part..

  1. Trade receivables is now at 120.654 million. (Hmmm... a worrying signal? Hard to say at this moment of time cos after all this quarter Scomi showed a sales revenue of 92.661 million.)
  2. Cash flow. Starting cash was at 126.963 million. A quarter after a share placement issue, in which Scomi generated 125 million in this fund raising exercise. At the end of the quarter, cash is only at some 69.975 million. Where ze Moola go???? (ah ze classical arguement of a company using leverage to expand and grow the company!)

Scomi reported that earnings on 11th Aug 2004.

Let's watch happens in Scomi's next quarter, 2004 Q3.

Good point:

  1. Net profit is now 23.339 million. 5 quarters ago, Scomi was just a company making 4.037 million. Company is making more money isn't it? Isn't this what u call explosive growth?

Fantastic isn't it?

And again, here comes the worrying part...

  1. Trade receivables is now at 214 million. (Hmmm... again a worrying signal? And again hard to say cos Scomi had sales revenue of 211 million for the quarter and since with the company made making more sales, more receivables is accumulated, rite?)
  2. Cash is now at 90.668 million but the loans is now 514.669 million. Scomi is now in debt of 424 million!!!! ( A huge worry? )

A flag has been raised, eh? Them same old worrying issues is getting more worrying, isn't it? Time to exit da bugger?

Scomi reported that set of arnings on 3rd Nov 2004.

Next quarter, 2004 Q4 was pretty dull. Pretty much the same old, same old. A neither here or there quarterly earnings report.

So fast forward to 2005 Q1 earnings. Which was really 'interesting'..


Soooooo many issues!!!

1. Net Profit is only 14 million? Big worry? Down from 20+ mil on a q-q basis...
(ahh.. again... some will argue cos on a y-y comparision.. this 14 million net profit is still much better than the 7 million it earned a year ago).

2. Trade receivables is now 333.889 million. Now this trade receivables is NOW a huge worry cos quarterly sales is now 229.236 million only. Where is that extra 100+ million of receivables coming from? What if a huge portion of these trade receivables turn bad? Bad debts then?

3. Loans? Loans is now 457 million. Down from 540 million a quarter ago.

4. Total cash increased to 118 million from 86 million a quarter ago.

5. Is 3 and 4 a good point? My answer is NO. If one looks at Scomi's Cash flow, Scomi's made yet another share placement to raise cash. A placement which saw Scomi raised 145.476 million.

So what we have is:

Scomi raised cash from placement of shares which is then used to pay off some of its loans....

But how does one evaluate Scomi's earnings performances? Surely if one is a buyer of Scomi's placement shares, one would probably not be too happy with it cos the bottom line is Scomi's net earnings declined from 20+ million to just 14+ million.

Now given 1,2, 3 and 4 and most importantly point 1, Isn't the time to really to exit this bugger?

Scomi reported this earnings on 25th May 2005.

Scomi closed at 1.40 on 25th May 2005.

And here comes the company most recent earnings (in Sept 2005)


And how did Scomi do?

1. Net earnings came in at 13.351 million. Which was down from 20 million plus earnings it earn a couple of quarters ago...

Now why issit such a huge worry?

1. Trade receivables is now a whopping 374 million.

2. Loans. Total loans is now 511 million.Up from a total loans of 457 million a quarter ago. Hmmm.... if one looks at the bigger picture, Scomi did a placement, paid of some 80 million plus in loans but come the next quarter, it borrows yet again. Doesn't it mean that Scomi is now back at square one? At the peak, Scomi total loans once stood at 540 million!!!

How? Now Scomi has been on a sell-off since May. Down some 30% and it is not too surprising eh?

Let's re-examine what has been said.

At the start (03 Q2), we were looking at a company with the following characteristics...

  1. Company was making about a quarterly net profit of 4 million.
  2. Cash was 11.102 million versus Total loans of 18.617 million. (a net debt position of 7.515 million)

8 quarters later, after countless of acquisitions and 2 share placement and sooooooo many ESOS....

We are now looking at....

1. A company making 13 million per quarter.

Compare to the 03 Q2 in which Scomi made only 4 million. An increase of 9 million So company is making 3.25 times more moola.

2. Company cash balance is now 106.119 million. Total loans stand at 511.613 million. Company is now in a net debt of 405.494 million.

Comparison. In Q2, company net debt position was a mere 7.515 million. Now the net debt position has increased by a WHOPPING 53X.

Justifiable given its current earnings? (some would ask: Does it make sense to increase ur total debt position by 405 million to make that extra 9 million in profit???? )

how? how? how?

Would it be wrong to say that this is an insane strategy employed by Scomi????

Oh btw, Scomi now has 991,130,700 shares. How signifacnt is this? Well, back in 03 Q2, Scomi Group had just around 91 million shares! ;p

<<==>>

That was back in Sept 2005. Sorry mate to bore you with all those details but I do reckon that it is useful to understand why Scomi rose so high and why its share price was declining quite a lot late last year (Scomi traded as low as 0.95 back in Nov 2005!).

Anywayyyyyyyyy...

In Nov 2005, Scomi announced its Q3 earnings. Scomi quarterly net earnings increased to 16 million.

In Feb 2006, Scomi announced its Q4 earnings. Scomi quarterly net earnings increased to a whopping 109.539 million!!!

So let's look at how did Scomi do since its listing...

For its fiscal year 2003, Scomi Group announced an earnings of 14 million.
For its fiscal year 2004, Scomi Group announced an earnings of 61.4 million.
For its fiscal year 2005, Scomi Group announced an earnings of 151.692 million.

And there you have it mate, yes it is true that Scomi has an astonishing growth rate!

But how about them points again? Well, as at its last reported earnings...

  1. Cash is at 87.595 million.
  2. Trade receivables has increased to 438.430 million.
  3. Group's borrowings is not at 918.363 million.

And yes, I do understand your issue that leverage can be used to generate a much higher revenue but on the other hand, I do hope you realise that this leverage issue is a matter of personal views and opinions. Me, for one, believe that too much leverage can turn deadly if one is not prudent enough.

And by the way, from my live quotes, I do note that as of today, Scomi Groups' number of shares is now 996.208 million shares!!

Yup, it increased yet again. Which means based on this enlarged share base, Scomi's current eps is now 15.2 sen. Ok?

And yes, I had mentioned the perils of a company issued placement shares.

Currently, Scomi does have the earnings to justify its strategy but do remember what happened back then in Sept 2005. Look at how the share tumbled when the earnings wasn't there. Do take note of this issue. It could well happen yet again but then on the other hand, if the Scomi 'produce' those earnings, the market could well go ga-ga over the share again.

Cheers!