It's been a while since I last wrote something about Man United and how could I not given what had happened last week. Yes last week. Remember that six in the city?
Well, many would point out that United controlled the game pretty well in the first half and City scored from the only half chance they had. Yes, it was a half chance but that 'Why Always Me' dude, took the chance first time and the boy that finish was top class. There's no defending against that. It was not like our defence was poor but Balotelli did not take another touch on the ball, he just fired it first time. There was no time for the defenders to react and his shot was right on the sweet spot . No goalie in the world was going to save that. It was simply magical.
However, for me, despite United controlling much of the first half, I wasn't at ease. United was simply a step slower and they could not find the space. Without space, their wings were clipped and speed in their game went missing. Too many balls were played to the feet. Players retrieving these passes were waiting for the ball and not running into spaces for the balls. This took out the speed and it made defending against United rather easily. And many pases were missed too. This ain't cutting it and this ain't gonna to open up a team like City who came to Old Trafford happily to sit deep in their own half in the first half.
And yeah, Evans got send off.
And United got hammered. We lost. We got beaten.
The incredible thing was, this hammering made many people happy. It's not that their team won. It's simply that United got whipped badly at home in a derby match.
And no, I will still support Man United and I believe many will still do for a long time. We did not support United just because they were winning.
And I will be cheering for them against Everton later.
And no, I won't be cheering like a cow on steroid just because the other team lost.
Saturday, October 29, 2011
And so Manchester United Got Hammered By Citeh




Friday, October 28, 2011
And IOI Corp Gave Its 83 Million Reasoning Why It's Cancelling The Deal With Dutaland
Last night, IOI Corp explained in detail on why they are pulling out from the deal to buy the plantation land from Dutaland.
I find it very unacceptable how IOI is handing this whole saga.
Their first announcement made on 25 Oct 2011:
- Reference is made to the Company’s announcement on 28 July 2011 pertaining to the sale and purchase agreement ("SPA") entered into between Sri Mayvin Plantation Sdn Bhd ("Sri Mayvin"), an indirect wholly-owned subsidiary of the Company with Pertama Land & Development Sdn Bhd (“Pertama Land”), a wholly-owned subsidiary of Duta Plantations Sdn Bhd, which in turn is a wholly-owned subsidiary of Dutaland Berhad ("DutaLand") to acquire 11,977.91 hectares (or equivalent to 29,597.42 acres) of oil palm plantation land ("Plantation Land"), for a total cash consideration of RM830 million ("Proposed Acquisition").
The Company wishes to announce that Sri Mayvin had on 25 October 2011 issued a notice to Pertama Land to terminate the SPA due to non-compliance of certain terms and conditions which had been communicated to Pertama Land. Under the provision of the SPA the rights and obligations of the parties shall lapse and be of no further effect from the date of termination notice, save and except that OSK Trustees Berhad, being the stakeholder shall within a period of seven (7) days from the notice of termination refund to Sri Mayvin the deposit of RM83 million which is equivalent to 10% of the purchase consideration and interest accrued thereon.
They terminated the S&P to purchase the land because "non-compliance of certain terms and conditions".
This is a 830 million ringgit transaction that they are terminating and at stake is a 83 million ringgit deposit paid.
The lack of detail was utterly disappointing. Surely, as one of Malaysian leading corporates, IOI Corp, could have shown the decency and respect to the investing public by explaining in detail what exactly was happening.
Now given what happened three years when IOI Corp forfeited 73 million ringgit when they pulled out of a deal to buy Menara Citibank, IOI Corp should have realised that it's absolutely crucial that they explain in full detail to the market what exactly was happening.
But no, they decided not to.
Was it an act of arrogance? I dunno...
Last night, 27 Oct 2011, IOI made another announcement. I was shocked at IOI Corp's inefficiency. Why can't they just announce it on the 25th? Why the need to make another separate announcement? Gosh! I just find it so unacceptable. Why the utter lacking in professionalism?
Anyway, this is what they said.
- We refer to the Company’s announcement dated 25 October 2011 pertaining to the termination of sale and purchase agreement ("SPA") entered into between Sri Mayvin Plantation Sdn Bhd (“Sri Mayvin”) and Pertama Land & Development Sdn Bhd (“Pertama Land”) for the Proposed Acquisition.
The Company wishes to announce that Sri Mayvin has communicated incidences of non-compliance/ breach of the SPA to Pertama Land vide letters dated 4 October 2011, 20 October 2011 and 21 October 2011. In summary, the incidences of non-compliance/ breach by Pertama Land of the terms and conditions of the SPA may be, among others, categorised as follows:
1. Adherence to the obligation for the continued upkeeping/ maintenance of the properties in accordance with accepted agronomic practices;
2. Discrepancies in the particulars relating to the properties; and
3. Integrity of the title of Pertama Land in relation to one of the properties.
How?
Are these three reasoning valid for IOI to pull out for the deal?
And at a stake, a 83 million ringgit deposit. Huge money at stake here!
How?
On Business Times today, IOI Corp was featured again.
- IOI maintains stand on deal turned sour
By June Ramlee Published: 2011/10/28
KUALA LUMPUR: IOI Corp Bhd, which stands to lose an RM83 million deposit to Dutaland Bhd from a deal turned sour, yesterday insisted that the latter had breached their sale and purchase agreement (SPA).
Dutaland, however, maintained that it had not acted in breach of the SPA relating to a piece of plantation land.
IOI previously announced that it had terminated the SPA to buy 11,977.91ha of oil palm plantation land in Sabah from Dutaland for RM830 million.
IOI then said the cancellation was "due to non-compliance of certain terms and conditions".
On July 28 this year, IOI's unit Sri Mayvin Plantation Sdn Bhd had signed the deal with Dutaland's unit Pertama Land and Development Sdn Bhd.
Yesterday in a filing to Bursa Malaysia, IOI maintained that Dutaland, among others, had failed to continue upkeeping and maintaining the properties. It also claimed that there were discrepancies in the particulars relating to the properties, and that Sri Mayvin had communicated the alleged breaches to Pertama Land.
Dutaland, in its latest filing to the stock exchange, said Pertama Land had consistently maintained that it was not in breach of the SPA as alleged.
There had also "been non-compliance on the part of Pertama Land under the SPA as alleged or at all by Sri Mayvin", it added.
Meanwhile, analysts said there will be a minimal impact on IOI's overall earnings if it loses its RM83 million deposit from the deal inked with Dutaland Bhd a few months ago. This is because IOI is a cash-rich company with profits of close to RM2 billion to RM3 billion a year.
Losing the RM83 million deposit on that deal would not make a big difference as the potential loss will only lower its earnings by three to four per cent, said several analysts when contacted by the Business Times yesterday.
"It's too early to say (if the deposit will not be returned) but if they can prove that it is non-compliance, then they should be able to get their money back.
"But if they lose their deposit, then there would be minimal impact on the company as it makes RM2 billion in profits in a year, so it won't hurt much," said one analyst.
It will not be the first time IOI will lose its deposit. In 2008, the company had forfeited its deposit of RM73.4 million after it walked away from buying Menara Citibank.
Analysts, however, said the Citibank and the Dutaland deals cannot be equated, given that the company had decided to walk away from the former deal.
Dutaland earlier said it was seeking legal advice and had notified OSK Trustees Bhd not to remit to Sri Mayvin the deposit of RM83 million being the 10 per cent deposit paid by Sri Mayvin under the SPA and any interest accrued.
- Losing the RM83 million deposit on that deal would not make a big difference as the potential loss will only lower its earnings by three to four per cent, said several analysts when contacted by the Business Times yesterday.
- "But if they lose their deposit, then there would be minimal impact on the company as it makes RM2 billion in profits in a year, so it won't hurt much,"
How could these analysts take the 83 million and compare it against what IOI Corp is making as whole? Yeah, IOI Corp could be making rm 2 billion a year but goodness me, 83 million ringgit is 83 million ringgit is 83 million ringgit. This is money way beyond most of us Malaysians.
Well, what if everyone starts having such an attitude and mindset such as 'hey we make 2 billion a year, it's ok to blow away 83 million... it's just a bloody spit in the ocean....' ?
How?
Is that acceptable behavior?
No, that's not for me. Not in a million years.
But then ... looking at recent losses from IOI Corp - the 300 million forex losses, the 73 million forfeited deposit and now this.... you begin to wonder.....
And last but not least...
- Analysts, however, said the Citibank and the Dutaland deals cannot be equated, given that the company had decided to walk away from the former deal.
How could it not be equated?
Tell me.... sigh.
In the Citibank debacle, IOI Corp pulled out 3 months after signing and the S&P. For this Dutaland purchase, IOI is again pulling out 3 months after signing the S&P.... how are they not the same?
Two of the reasons given last night by IOI...
- 2. Discrepancies in the particulars relating to the properties; and
3. Integrity of the title of Pertama Land in relation to one of the properties.
Hey, it's a 830 million deal... surely you want to examine everything in full detail... before you sign, yes? Why sign and paid the deposit only to now claim discrepancies and integrity? Why risk losing the deposit paid? Is 83 million ringgit small change?
Now? It looks like the fate of the 83 million ringgit lies in the hands of the court.
On Star Biz: IOI, Dutaland in war of words over termination of RM830mil deal
Wednesday, October 26, 2011
Yet Another Multi Million Screw Up From IOI Corp?
I was shocked when I read the following set of news last night:
- IOI Corp cancels RM830m land purchase from Dutaland
- Dutaland rejects IOI Corp bid to cancel RM830m land purchase
Last night, just 3 months after signing the deal, IOI Corp said it's cancelling this deal.
And of course, Dutaland quickly responds by saying it's taking legal advice since it's not accepting IOI's reason for termination.
And as you can guess, Dutaland has asked that the deposit of 83 million not be remitted back to IOI Corp.
And this looks like yet another woeful corporate exercise from IOI Corp.
Just what on earth are they doing?
This is a 830 million transaction. You just don't sign any 830 million corporate deal without making thorough due diligence before agreeing to purchase. And IOI explanation on why it's cancelling this deal is simply a " non-compliance of certain terms and conditions".
This is simply pathetic and it reminds me of the recent Citibank debacle that happened back in Nov 2008.
Here's an article on Star Biz back then.
- Saturday November 29, 2008
IOI Corp should better explain why it’s losing its RM73mil deposit
By P. Gunasegaram
REALLY, listed companies should be a lot more careful before they pay a deposit for their proposed acquisitions. If they can’t complete their deals for any reason, they can lose hefty sums of money and raise needless suspicion over board integrity.
Boards of listed companies and CEOs should realise that they have a statutory duty not only to their major shareholders but also to each and every shareholder – and there are many minority shareholders to consider.
The least that listed companies should do when they abort their deals is to offer a full and fair explanation of why it was aborted, what were the events that had changed and why these things had not been anticipated in the first place.
Take the deal called off inexplicably by IOI Corp after having signed on the dotted line less than three months ago and losing over RM73mil in deposits paid in the process.
It had announced on Aug 28 the effective acquisition of Menara Citibank in Kuala Lumpur for RM586.7mil through the purchase of Inverfin Sdn Bhd which owned the building. Inverfin is owned in turn by Citigroup unit Citi Holding (50%), Singapore’s CapitaLand (30%) and Amsteel Corp (20%).
On Thursday, Nov 27, IOI Corp, just a day short of three months of the earlier announcement, told Bursa Malaysia that it has decided not to proceed with the acquisition.
The reason in IOI Corp’s own words: “However, due to the recent sudden adverse developments in the global economic environment which have spread to this region and impacted negatively on business sentiments, the Company has, after due and careful deliberations, decided that it would be in the overall best interests of the Company and its shareholders not to proceed with the Proposed Acquisition.”
It further announced that the vendors were forfeiting the deposits paid of RM73.4mil together with interest and added that it was “seeking legal advice as to the propriety and quantum of the aforesaid forfeiture”.
It is instructive to note what IOI Corp said in its original acquisition announcement: “The Proposed Acquisition will provide IOI with an immediate substantial rental income stream. With its choice location at the heart of Kuala Lumpur and well served by the surrounding infrastructure and amenities, Menara Citibank is presently enjoying close to 100% occupancy rate with quality tenants consisting of multinational companies and reputable companies in their respective industries.
“In addition, the 50-storey Menara Citibank is well-maintained and well-equipped with high quality mechanical and electrical equipment and good security system. Its distinctive design and quality also distinguish itself from the competing office buildings in the vicinity.
“On the whole, the Proposed Acquisition is a strategic move which augurs well for the IOI Group as it accords the Group with the golden opportunity to own one of the few available high-rise Grade A office buildings in Kuala Lumpur with first class location and prestigious address.”
So, why is that changed in three months? Was there an exodus of tenants from Menara Citibank? Did the rental income drop? Was there a collapse in office space prices? Why is the acquisition not strategic anymore?
Why could not IOI Corp have foreseen these problems earlier? After all, the subprime crisis was already upon us. Why did it pay the deposit which it now has most likely lost if it had felt there could be problems?
IOI Corp’s explanation is poor at best and we really don’t know what it is at worst. Investors certainly expect a lot more from this company, once the darling of the stock market. And so should regulators. Minority shareholders certainly have a right to be seriously upset.
Coming so soon after its recent debacle where it reported foreign exchange losses of over RM312mil for the quarter to end-September, the latest episode will put another dent in its reputation, largely unsullied until the forex episode.
IOI Corp back in 2008, had also terminated a deal 3 months after signing the deal!!!!
And IOI lost its 73 million deposit back then. Me? I won't be surprised one bit if IOI loses 83 million ringgit this time for cancelling its deal with Dutaland.
It's simply embarrassing and if I am a minority shareholder in IOI Corp, I would be deeply annoyed to see what's happening. IOI Corp is supposedly one of our country's biggest corporation. In 2008, IOI lost 73 million by rescinding a deal to buy Citibank. 3 years later, IOI could now lose 83 million by cancelling this deal to buy land from Dutaland. What the hell? Does IOI have so many million ringgit to give away???
Would you blame any minority shareholder for asking 'Is IOI Corp the biggest water fish in corporate Malaysia?'
Good grief!
ps: Looks like Dutaland could get 83 million ringgit free!
ps: I got some barn yard. Does IOI want to agree to buy and then cancel to buy from me? :P
Tuesday, October 25, 2011
And Genting Malaysia Rewards Its Shareholders With Yet Another RPT
And so Genting Malaysia announced its 4th RPT last night.

Snippet from CIMB report:
- What We Think
At first glance, the news of yet another RPT by Genting Malaysia is negative. Although Genting Malaysia expects to reap cost savings from the acquisition as it is E-Genting’s largest customer, the RPT might not sit well with investors. This is the fourth RPT in four years, the others being Walker Digital, Wisma Genting and Genting UK.
However, we take comfort in 1) the size of the acquisition, which is small at 3% of net cash and 0.4% of total shareholders’ funds, 2) fair pricing of 5.2x P/E and 2.0x P/BV for E-Genting, and 3) the profitability of E-Genting’s business. Genting Malaysia also accounts for close to 80% of E-Genting’s revenue. Ascend International only has minimal operations at this juncture.
What You Should Do
Any share price weakness from this news should be viewed as an opportunity to accumulate the stock. Genting Malaysia’s defensive earnings and strong operating cash flow are appealing in uncertain times like these.
It's the 4th RPT lah.
When will Genting Malaysia respect its minority shareholders and stop all these Related Party Transactions (RPT) nonsense?
Is it so difficult to respect?
CIMB said '.. we take comfort in 1) the size of the acquisition, which is small at 3% of net cash '
Gosh! This deal is worth 50 million ringgit. Is 50 million ringgit small? WTH? And how could CIMB insult the intelligence of its readers by comparing it versus the 'net cash'?
50 million ringgit is 50 million ringgit is 50 million ringgit!
And the last part... it's advice "What You Should Do - Any share price weakness from this news should be viewed as an opportunity to accumulate the stock.'
Oh yeah, as usual any share price weakness is an opportunity to accumulate the stock... but just what kind of stock is one accumulating? What kind of company is this? Does the investor looks smart investing in a company who only does nothing but RPTs? Does it make sense?
And if the minority does nothing, such transactions will keep on happening over and over and over again.
Past postings:
- 9 Dec 2009: Genting Malaysia Buys Properties From Genting Bhd
- 16 Dec 2009: MSWG Slams Genting Malaysia For Its RPT Land Deal!
- 2 Jul 2010: Genting Malaysia's UN Fortunate Entry Into UK Casino Business
- 25 Aug 2010: Shame On The 60.39% Who Voted For Genting Malaysia's UK Casino Purchase
Sigh!
Friday, October 21, 2011
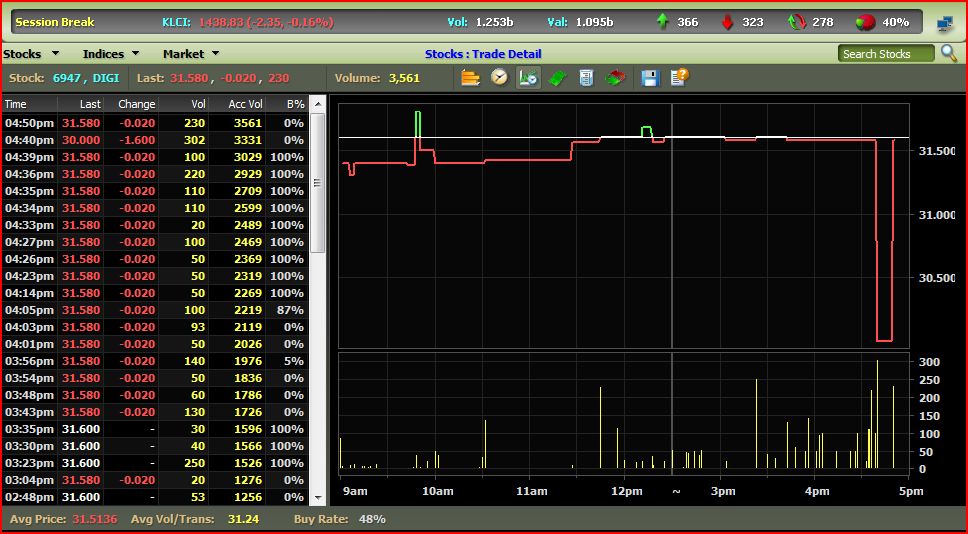
And FBM KLCI Decided To Have Its Own FLASH CRASH!
Say cheese!

Was that fun or was that fun?
The culprits?
Pick your poison.... in random order
Sime Darby

Petronas Dagangan

IJM

DIGI
MISC

KLK

IOI

TENAGA

PPB Group

HLFG

MHB

HL Bank

MISSED OUT....
PETGAS

AIRPORT

ps: see the volume..
ps: where's the calculator...
ps: did i miss out any stock?
ps: Wanna know more about flash crash? Click here: Flash Crash
------------------------
From the Edge Malaysia: KLCI plunges 70 pts due to trades keyed by broker
- An official from Bursa Malaysia Securities Bhd in an e-mailed statement confirmed that the drop of the index at 4.41pm on Friday was due to trades keyed in by the said broker.
Among the stocks that fell steeply before paring down losses were KLK, DiGi and PPB.
Err... is that all there is to say?
-----
This was on Business Times. ( Small piece -- it's like NOTHING happened.
- Bursa: Sharp fall due to broker deals
Published: 2011/10/22
KUALA LUMPUR: Malaysia's stock exchange operator, Bursa Malaysia Bhd said a sharp drop in the FTSE Bursa KLCI, its benchmark index, was due to trades keyed in on select index component stocks by a broker.
The KLCI dropped 4.8 per cent at 4:41pm to 1,371.92 points from 1,440.52 points before recovering 10 minutes later.
The benchmark index closed down 0.2 per cent for the day at 1,438.83 points.
Bursa did not say if the trades were made deliberately or by accident. - Reuter
Read more: Bursa: Sharp fall due to broker deals http://www.btimes.com.my/Current_News/BTIMES/articles/BURTA/Article/index_html#ixzz1bT5W6VQL
Here's Star Biz comments: KLCI down on cautious stance
Flash crash? What flash? ( I guess the flash must be really such a flash that they saw absolutely nuthin'! )
Tuesday, October 18, 2011
And Bursa Malaysia Gets Serious And Fines ex-Remiser Rm 60,000
And then there is the case of the ex-remiser who got fined rm 60,000.00.
RM 60,000?
Er... seriously... what kind of fine is that?
I mean if this fella is found guilty... then he's guilty... but the fine of rm 60,000???
Goodness me!
With such a MASSIVE fine.. this sure will stop any future shenanigans!
Comeon... who's insulting who?
Oh yeah... forgot to mention the fine was for 'unlawful trading'.
Gosh! What on earth is 'unlawful trading'?
Comeon!
How does one expect our stock exchange to improve and rid itself of such pathetic nonsense in the future?
On the Edge:
- Bursa Securities fines ex-remisier RM60,000 for unlawful trading Written by Joseph Chin of theedgemalaysia.com
Tuesday, 18 October 2011 17:51
KUALA LUMPUR: Bursa Malaysia Securities Bhd rapped and fined a former dealer’s representative Mohd Zahir Abd Manan RM60,000 for unlawful and unethical trading activities.
It said on Tuesday, Oct 18 that it had also ordered Mohd Zahir be struck off from the Register as a dealer’s representative in unlawful and unethical trading activities in the securities of H-DISPLAYS (MSC) BHD [] and HDM-Carlaw Corp Bhd.
It said Mohd Zahir, who at that time a commissioned dealer’s representative of PM Securities Sdn Bhd, triggered and breached the provisions of the Rules of Bursa Securities.
“Bursa Securities views misconducts that compromise the integrity or honesty of registered persons seriously as registered persons, including dealer’s representatives are required to uphold the interest of their clients and the investing public,” it said.
Bursa Securities said Mohd Zahir had carried out numerous unauthorised sale and purchase transactions in the securities of H-Displays and Carlaw over a period of time via two of his clients’ accounts.
His unauthorised transactions resulted in substantial contra losses which were disputed by the clients when they were subsequently informed of the losses.
It added he had colluded with a third party, who was not a person allowed and authorised, in writing, to trade on behalf of these clients. In this regard, instructions to trade via the two clients’ accounts were received from the identified third party and were carried out by Mohd Zahir. The commission generated from these trades was shared between Mohd Zahir and the third party.
“Mohd Zahir had also colluded with the identified third party to manipulate these two securities by maintaining their prices at certain levels. The manipulative trading activities had impacted the price of these securities during the relevant period.
“Mohd Zahir’s misconduct in carrying out these unauthorised trades and participating in unlawful activities, including price manipulation of these securities over a period of time, demonstrated his blatant disregard of his obligations as a responsible dealer’s representative,” it said.
Comeon... why can't Bursa just gets really tough on these buggers?
RM 60,000?
Bah!
Where got enough?
Monday, October 10, 2011
I Screwed UP My Earlier KNM Posting
Arrrghh....
I screwed up.
:P
KNM - Would Poor Corporate Governance Have A Negative Impact On The Stock?
That posting have one MASSIVE flaw.
What happened? Well, I relied on the little bells provided by RHB charting. I did not verify the data and if I did, I would realise that RHB missed out the events that happened on Aug 2004. Meaning to say there was a 1 into 2 share split ( see announcement:
Which means my entire posting is beyond repair.
LOL!
Excuse? I was too lazy and incompetent to check my facts.
Ok... please line up and aim all the rotten eggs over here!
ps: pls be gentle.
ps: I am too lazy to recount. hehe. But if anyone is kind enough, I welcome them to do the entire calculations for me. :P
ps: It is Monday, isn't it?
Saturday, October 08, 2011
KNM - Would Poor Corporate Governance Have A Negative Impact On The Stock?
******* EDIT 10/10/2011. The following posting is rather meaningless now because I realised that
I Screwed UP My Earlier KNM Posting ********
==========================================
Last month, I posted on the issue of the impact of corporate governance on a stock.
Do see Maybulk: Does poor corporate governance have a negative impact on a stock?
So this morning I was wondering about And KNM Directors Got Fined.... rm 25,000 Each!
( Yeah, tell me about it. A fine of rm 25,000 for a corporate director? I wonder who does the fine insult??? Really! )
Anyway, I was thinking about the impact of the poor corporate governance from KNM on its stock price.
I asked myself, what if an 'investor' bought KNM when it IPOed back in 2003 and held it till today.
Now that sounds like a fun exercise, no?
So, I opened up the chart of KNM from RHBInvest. This was KNM's chart since its listing in 2003.

Doesn't look too bad, yes?
But then I looked at all those little bells on the chart. And I made reference back to Bursa website and the result was rather interesting.
First, the IPO.
27 June 2003: PUBLIC ISSUE OF 6,680,000 NEW ORDINARY SHARES OF RM1.00 EACH AT AN ISSUE PRICE OF RM1.48 PER NEW ORDINARY SHARE PAYABLE IN FULL ON APPLICATION AND PLACEMENT OF 4,400,000 NEW ORDINARY SHARES OF RM1.00 EACH AT A PLACEMENT PRICE OF RM1.48 PER NEW ORDINARY SHARE PAYABLE IN FULL ON APPLICATION BY THE NOMINATED PLACEES
Ok, let's ass-u-me.... :)
IPO at 1.48 - 27 June 2003.
Assume 'investor' purchases 2,000 shares. This means an investment outlay of 2x1.48 = 2960.
(ps: if I do screw up with my calculations, please don't sue... just tell me and I will correct. :P )
A. 1 for 2 bonus issue Sep 2006 ( see announcement: Bonus Issue )
So total number shares becomes 3,000
B) 1 for 1 bonus issue and then share split 1 into 2 - June 2007. ( see announcement: Bonus Issue and Entitlement - Others )
Getting tricky. :P
Total number of shares held is now 3,000
After bonus issue, total number of shares becomes 6,000
After share split of 1 into 2, total number of shares becomes 12,000
Hope I have yet to screw up. :P
C) May 2008, rights issue of 1 for 4 at rm 4.00. ( see announcement: Rights Issue )
Getting even trickier. :P
(rights issue? LOL! Put more money in babe!)
With 12,000 shares, 'investor' will be eligible for 3,000 new shares at a price of 4.00 each.
Assuming 'investor' agrees and takes up the rights issue, 'investor' puts in extra outlay of rm 12,000.
Total outlay + original cost of investment = 12000 + 2960 = rm 14,960
Number of shares held becomes 15,000
( no screw yet, I hope! )
D) 2 for 1 bonus issue. July 2008 ( see announcement Bonus Issue )
Waaaahhh! so generous! 2 for one bonus issue woh!
Aha! Made a mistake here. :P
Investor had 15,000 shares. A 2 for 1 bonus would see investor get 30,000 new shares.
So investor would now have 45,000 shares. ( Sorry.. sorry... and thanks for the correction!)
E) 4 into one share split!! ( see announcement: Entitlement - Others )
( Hehe... KNM back then... faced thunder, lightning woh! ... let's see there were ... forced selling on CEO shares, share buybacks, MBOs.... errr... such a happening stock.... and yeah KNM was a penny stock then! 4 into 1 .... would make KNM... appear more expensive. Hohoho! )
4 into 1 reverse share split...hmmm...
45,000 shares would be consolidated into 11,250 shares. ( how did I pass my maths? :P )
Ok so far?
Remember original outlay + original cost of investment = rm14,960.00 and the number of shares held is 11,2500 shares.
KNM today is 1.23
If investor cashes out today, investor gets back 11.25 x 1230 = 13,837.50
But.... cost of investment = 14,960!!!!
Arrrrrrrrrrrrrrghhhhhhhhhhhhhhh!!!!
See the wonders of holding an investment in a stock that has poor corporate governance?
But.... but..... it looks like I have screwed up!!!
Oh.... no..... oh yeah!
I left out all dividends. *&^^:$%^#^%%#@@
hey but if you are interested to know how huge the dividends were... and lol.. if you think too huge... please skip the tedious counting below... :P
- June 2004: Final Dividend
- May 2005: First and Final Dividend
- June 2006: First and Final Dividend
- June 2007: First and Final Dividend
- Feb 2008: Interim Dividend
- Feb 2009: Interim Dividend
- March 2011: Interim Dividend ( I don't see any for 2010. :P )
June 2004, 5 sen tax exempt. In this case, investor had 2000 shares then. This means 10 sen collected.
May 2005. 3 sen less tax of 28%. ( 3 sen also want to less tax? :P ) Investor had 2,000 shares. So dividend collected this year would be 4.32. Total dividend collected = 14.32 sen.
June 2006. 5 sen less tax of 28%. Still 2,000 shares. So dividend collected this year would be 7.2 sen. Total collected = 21.52 sen.
July 2007. 5 sen less tax of 28%. Now have 3,000 shares. So dividend collected this year would be 10.8 sen. Total collected = 32.32 sen.
Feb 2008. 4 sen less tax of 27%. Now have 12,000 shares.So dividend collected this year would be 35.04 sen. Total collected = 67.36 sen.
Feb 2009. 1 sen less income tax of 25% and 0.5 sen tax exempt. Now have 45,000 shares. So dividend collected this year would be
March 2011. 3 sen tax exempt. Number of shares now held
So total dividends collected (assuming me calculations is not screwed up) since 2003 is
Let's add this figure to the earlier calculations...
Cost of investment - 14,960
Shares worth today - 13.837.50 *** corrected figure ***
Dividends collected - 1423.60 ** corrected figure ***
How?
* hehe... got profit woh! *
Popular Posts
-
 On the EdgeMalaysia: http://www.theedgemalaysia.com/business-news/279915-reports-by-financial-journalists-must-be-fair-accurate-and-respons...
-
Exactly. :) Let me try something new. This is an open post. Got an idea or stock tip to share? Everyone who is willing to share thei...
-
 From the Edge. http://www.theedgemalaysia.com/business-news/198283-envair-holdings-active-down-in-afternoon-session.html Envair Holdings ac...
-
Posted yesterday: Why Is Bursa CEO Getting Such A Pay Increase? I have always insisted that because Bursa Malaysia is a listed entity, it ...
-
On theEdgeMalaysia.com Bursa CEO's 57% pay rise spurs questions Business & Markets 2013 Written by Lee Wen Ai of theedgemalays...
-
On theSunDaily Business: http://www.thesundaily.my/news/645150 MBf take-over offer not fair but reasonable Posted on 25 March 2013 - 10:12...
-
 On 31 July 2008, I wrote about Axis Inc . The stock was trading at 2.00 on 11 July 2008. By 30 Jul 2008, the stock price collapsed to 35 sen...
-
 My last update of AirAsia's earnings was done on May 2011 : Update On AirAsia Earnings . Last night AirAsia reported its earnings. It...
-
Dear Ah sam, It was a change to see that you finally have the guts to post under your own blogger profile Samgoss .You certainly caught me...
-
 Got this in my comments: newbie has left a new comment on your post " MaeMode Defaults Its Loan Payments And Enters PN17... ":...


Subscribe To Where Is Ze Moola


 Posts
All Comments